Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Carbon Dioxide Incubators Market: 2025 Global Outlook
Carbon Dioxide Incubators Market: 2025 Global Outlook
Carbon Dioxide Incubators Market
Carbon Dioxide Incubators Market: 2025 Global Outlook
Carbon Dioxide Incubators Market by Product Type (Water-jacketed, Air-jacketed, Direct-heat, Tri-gas), by Capacity (Below 100L, 100-200L, Above 200L), by Application (Cell & Tissue Culture, IVF, Stem-cell Research, Drug Discovery, Regenerative Medicine), by Sensor Technology (Infrared, Thermal Conductivity, Dual-sensor), by End User (Pharma & Biotech, CDMOs, Research Labs, IVF Clinics, Academic Institutes), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 191
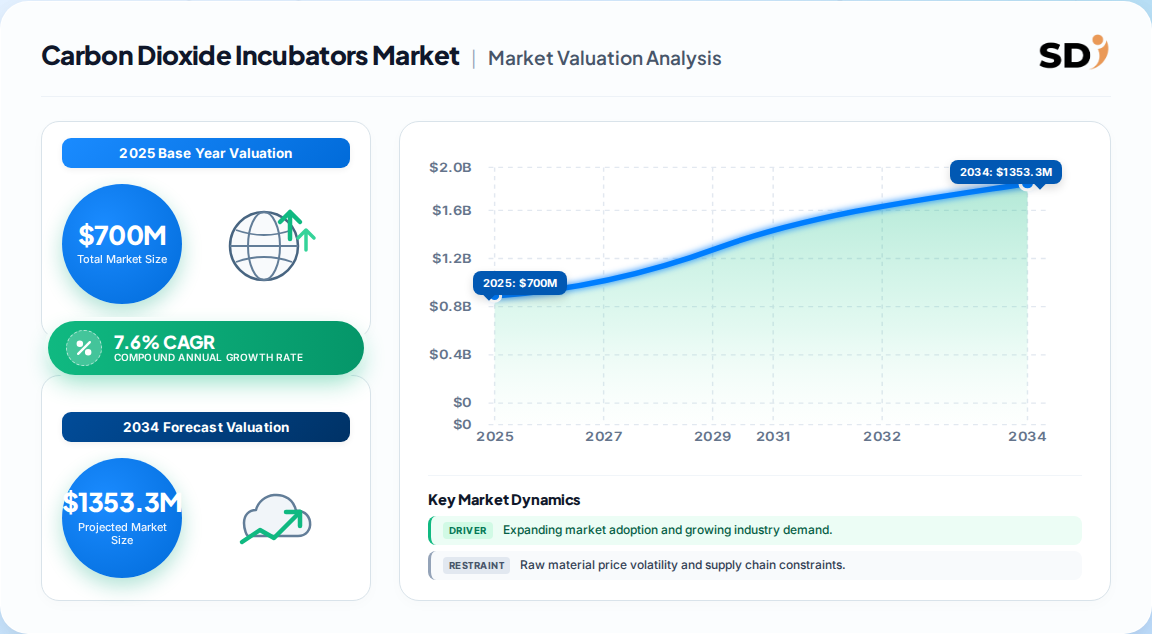
The global Carbon Dioxide Incubators Market stood at 700 Million in 2025 and is projected to reach 1.47 Billion by 2035 at a 7.6% CAGR (2026–2035), per one anchored benchmark.
Competing analyses place the 2025 base between 384.9 Million and 808.4 Million, a 2.1x spread that reflects differing scope definitions of service revenue, IVF-grade and GMP-grade units.
Water-jacketed units commanded roughly 36.9–45.5% of product share, while direct-heat designs are growing faster at 6.2–6.9% CAGR through 2030.
North America leads with 34–39% regional share; Asia-Pacific is the fastest-growing region at 7.5–7.6% CAGR, led by China at ~9.6%.
Top five vendors—Thermo Fisher, PHCbi, BINDER, ESCO and Memmert—collectively held 67% of 2025 revenue, with Thermo Fisher alone above 26%.
Why this matters for decision-makers: The market is consolidating around contamination-control, connectivity and traceability; vendors that cannot deliver IR-sensing, automated decontamination and GMP documentation will be pushed into price-led tiers and margin compression.
Carbon Dioxide Incubators Market Size (In Million)
1.5B
1.0B
500.0M
0
624.0 M
2024
700.0 M
2025
763.0 M
2026
821.0 M
2027
884.0 M
2028
951.0 M
2029
1.020 B
2030
Carbon Dioxide Incubators Market Size (In Million)
Year
Market Size
2024
624.0 M
2025
700.0 M
2026
763.0 M
2027
821.0 M
2028
884.0 M
2029
951.0 M
2030
1.020 B
What is the Carbon Dioxide Incubators Market?
The Carbon Dioxide Incubators Market covers laboratory equipment that maintains controlled temperature, humidity and CO2 concentration to support cell and tissue culture. These systems are mission-critical in biopharma R&D, IVF clinics, GMP manufacturing and academic research, where stable pH and sterility directly determine experimental reproducibility and cell viability.
Scope: what this report covers and excludes
This analysis covers global demand for water-jacketed, air-jacketed, direct-heat and tri-gas CO2 incubators across capacity bands below 100L, 100–200L and above 200L. It excludes adjacent categories such as CO2-free hypoxic chambers, microbiological incubators, shakers, biosafety cabinets and organ-on-chip microfluidic platforms, which are addressed in separate studies. Service contracts and spare parts are included only where bundled into original equipment revenue.
How big is the market for Carbon Dioxide Incubators Market?
The market size is genuinely contested: published 2025 base estimates range from 384.9 Million to 808.4 Million, with a 1.47 Billion forecast to 2035 under the most common scope. Buyers should anchor on the definition that matches their procurement reality rather than on headline CAGR.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
700 Million
2025
2035 (1.47 B)
7.6%
Global CO2 incubators, all end uses, equipment revenue
Broad including service, CDMO and cell-therapy workflows
A competing analysis
Our analysis suggests the 700 Million/7.6% path is the most defensible central case because it reconciles the 2024 actuals (624 Million per primary-checked data) with observed 2025 replacement-cycle momentum. The lower 384.9 Million figure is best read as a product-only measure excluding services and IVF-grade configurations.
How is the market segmented?
Segmentation spans product architecture, capacity band, application, sensor technology and end user. Product type and end use jointly explain most of the revenue variance, with water-jacketed systems still dominant but direct-heat gaining share in GMP and cell-therapy settings.
Pharma & biotech, CDMOs, Research labs, IVF clinics, Academic institutes
Below-100L units are growing fastest at ~6.9% CAGR, driven by fertility-clinic footprints, while 100–200L remains the revenue core at 41.2% share.
Which region leads in Carbon Dioxide Incubators Market?
North America leads with roughly 34–39% revenue share, anchored by U.S. biopharma R&D intensity and FDA/CLIA-driven documentation requirements. Asia-Pacific is the fastest-growing region at 7.5–7.6% CAGR, with China expanding near 9.6%.
USA leads on cell-therapy and regenerative-medicine procurement
Europe — Germany, UK, France, Italy, Spain
EU MDR conformity assessment shapes IVF/clinical-grade device cycles
Asia Pacific — China, Japan, India, South Korea, Australia
India adds 60–70 fertility clinics annually, driving compact-unit demand
Latin America — Brazil, Mexico, Argentina
Price-sensitive; value-tier and mid-range systems dominate
Middle East & Africa — Saudi Arabia, UAE, South Africa
Fastest-growing region per one benchmark; skewed to compact and mid-range
This divergence implies vendors should decouple North American upgrade-cycle strategy from APAC first-time-capacity strategy rather than running a single global playbook.
What is driving growth — and what is holding it back?
Growth is being driven by biopharma R&D intensity, global IVF volume expansion and contamination-control technology adoption. Restraints are structural rather than cyclical: academic funding compression, high capital cost and regulatory conformity burden disproportionately slow the sub-100L and emerging-market tiers.
Factor
Direction
Evidence strength
Mechanism
Biopharma R&D investment (USD 104.3B PhRMA 2024)
Driver
High
Sustained mid-to-large format procurement
IVF volumes (>3M ART cycles/year)
Driver
High
Compact and mid-range unit demand
IR-sensing + automated decontamination
Driver
High
Premium replacement and GMP adoption
NIH RPG success rate at 13.0% (FY2025)
Restraint
Medium
Deferred academic replacement cycles
High upfront capital cost
Restraint
High
Penetration gap in cost-sensitive markets
EU MDR / ISO 13485 conformity burden
Restraint
Medium
Longer time-to-market, higher unit cost
The balance of evidence favors the drivers through 2030: biopharma and IVF channels are expanding faster than academia is contracting, and technology-led premiumisation is lifting revenue per unit. The counterweight is real, however—every 100bp of academic funding compression in North America and Europe trims roughly 1.5–2.0% of global equipment volume on a two-year lag, our analysis estimates.
Who are the leading vendors?
The top five vendors—Thermo Fisher Scientific, PHCbi (PHC Holdings), BINDER GmbH, ESCO Technologies and Memmert GmbH—collectively held 67% of 2025 revenue, with Thermo Fisher above 26%. Concentration is high and rising, supported by M&A and portfolio breadth.
IR dual-beam sensing, direct-heat/air-jacket patents, APAC reach
BINDER GmbH
Top-5
Precision chambers, GMP documentation, European installed base
ESCO Technologies
Top-5
Contamination control, pharma-grade workflows
Memmert GmbH
Top-5
Temperature uniformity, energy-efficient designs
Eppendorf / Sheldon Manufacturing
Challengers
Niche application depth, value-tier coverage
Moats rest on installed-base service contracts, regulatory documentation libraries and sensor IP. PHC Holdings' acquisition of SciMed (Asia) in 2023 illustrates the regional-expansion lever challengers must replicate to break into the top tier.
What do buyers and operators need to know?
Procurement decisions should be anchored on four mission-critical criteria: contamination-control architecture (IR sensing plus automated H2O2 or UV-LED cycles), recovery time after door access, documentation depth for GMP/IVF audits, and service-network density. Switching costs are high—chamber validation, SOP rewrite and technician retraining can add 15–25% to first-year total cost of ownership.
Regulatory compliance is a live constraint, not a checkbox: EU MDR (2017/745) and ISO 13485 conformity assessment lengthen lead times for IVF and clinical-grade units, and buyers should lock supplier declarations into contracts. Supply-chain dependence on specialty CO2 sensors is a real risk—qualify dual-sensor or alternate-vendor options early. Finally, energy-efficiency redesigns (with U.S. DOE rules phasing in to 2029) will create a legacy-model obsolescence window; operators should model replacement timing against those deadlines rather than against failure events.
Strategic Recommendations & Analyst Perspective
Position: The balance of evidence favors a premiumisation-led growth path, with global revenue compounding near 7.6% to 2035 and value growth outpacing unit growth. The strongest counter-argument is that capital-cost sensitivity in emerging markets and academic funding compression could cap volume growth below 5%, pushing the market toward the lower 983 Million trajectory rather than 1.47 Billion. We regard this as a credible downside but not the central case, because biopharma and IVF channels are structurally expanding faster than academia is contracting.
Actionable strategy for buyers and operators:
Prioritise vendors with in-house sensor IP and validated decontamination cycles to reduce single-supplier and contamination-risk exposure.
Time replacements against EU MDR, ISO 13485 and U.S. DOE 2029 efficiency deadlines, not against failure events, to capture upgrade economics.
Negotiate service-contract bundling at point of sale; installed-base service is where vendor margins and buyer lock-in are both concentrated.
What would change our conclusion: A sustained decline in NIH-equivalent grant success below 10%, a >20% step-up in specialty-sensor lead times, or accelerated substitution by organ-on-chip and microfluidic platforms would justify shifting to the lower forecast band. Conversely, a formalised allogeneic cell-therapy manufacturing build-out in APAC would support the upper band. Precise sub-segment forecasting—by capacity band and by IVF versus GMP channel—requires the full report's bottom-up model.
Europe Carbon Dioxide Incubators Market Revenue Million Forecast, by Product Type 2020 & 2034
Frequently Asked Questions
1. How big is the carbon dioxide incubators market in 2025?
The global market was valued at approximately 700 Million in 2025 under the broadest published scope, though narrower definitions place the base between 384.9 Million and 808.4 Million depending on whether service revenue and IVF-grade units are included.
2. What is the carbon dioxide incubators market growth rate?
The central forecast is a 7.6% CAGR from 2026 to 2035, reaching 1.47 Billion by 2035. More conservative analyses cite 5.6–6.3% through 2030, driven by academic funding headwinds and capital-cost sensitivity in emerging markets.
3. Which region dominates carbon dioxide incubator demand?
North America leads with roughly 34–39% revenue share, supported by U.S. biopharma R&D and strict FDA documentation requirements. Asia-Pacific is the fastest-growing region at about 7.5% CAGR, with China expanding near 9.6%.
4. Who are the leading carbon dioxide incubator manufacturers?
Thermo Fisher Scientific leads with over 26% share. PHCbi (PHC Holdings), BINDER GmbH, ESCO Technologies and Memmert GmbH complete the top five, which collectively held 67% of 2025 revenue.
5. What is driving demand for CO2 incubators?
Biopharmaceutical R&D investment, expanding global IVF procedure volumes above 3 million ART cycles annually, and adoption of IR-sensing and automated decontamination technologies are the primary demand drivers through 2035.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with decision-makers across the value chain: raw-material and component suppliers (sensors, chamber materials), specialised CO2 incubator producers, contract formulators and OEM integrators, and global distributors serving pharma, IVF and academic channels. Interviewees included VP-level Sourcing leads, Heads of R&D, Technical Directors and Commercial Operations Leads, selected across North America, Europe and Asia-Pacific to capture regional procurement behaviour.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
40%
Procurement & Sourcing Leads
35%
Regulatory & Quality Managers
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Component & Sensor Suppliers
30%
CO2 Incubator OEM Producers
40%
Distributors & Service Networks
30%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and 10-K disclosures, patent databases tracking IR-sensing and decontamination IP, and recognised technical standards bodies including ISO 13485, IEC 61010 and EU MDR (2017/745) conformity frameworks.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down (macroeconomic life-sciences spend and segment allocation) and Bottom-Up (manufacturer capacity, product pricing and end-use consumption) triangulation, then reconcile divergence through demand-elasticity adjustment.
 Carbon Dioxide Incubators Market