 X Ray Vehicle Scanner Market
 Report 2026: Size, Share & Forecast
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 258

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 X Ray Vehicle Scanner Market
Sadashiv Parab
Research Analyst

| Year | Market Size |
|---|---|
| 2026 | 2.310 B |
| 2027 | 2.530 B |
| 2028 | 2.770 B |
| 2029 | 3.030 B |
| 2030 | 3.310 B |
| 2031 | 3.630 B |
| 2032 | 3.970 B |

The X Ray Vehicle Scanner Market covers high-energy transmission and backscatter X-ray systems that non-intrusively screen cars, trucks, and cargo for contraband, explosives, weapons, and smuggled goods at borders, ports, airports, and secure facilities. It includes fixed drive-through portals, portable/mobile units, imaging software, AI-enabled automated threat recognition, and associated services.
Scope: Global coverage of X-ray-based vehicle and cargo scanning hardware, AI/imaging software, and lifecycle services across government, critical infrastructure, and private-sector applications. Geographic coverage spans five major regions and key country markets. Excludes: millimeter-wave and terahertz imaging (analyzed separately), under-vehicle surveillance (UVSS) systems, medical X-ray equipment, and general cargo pallet scanners where the vehicle is not the inspection subject.
This analysis does not cover adjacent markets such as airport passenger baggage screening, handheld trace detectors, or non-X-ray cargo imaging modalities.
Estimates for X Ray Vehicle Scanner Market size diverge notably by definition — but a USD 2.3–2.5 billion base with a high-single-digit growth trajectory is the most defensible consensus view for 2026.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 2.31 Billion | 2026 | 2033 | 9.4% | X-ray vehicle scanning hardware + services only | One published X-ray-specific estimate |
| USD 2.19 Billion | 2025 | 2033 | 9.7% | X-ray-specific, component+type+application | Competing analysis (X-ray scope) |
| USD 2.80 Billion | 2025 | 2035 | 3.28% | Broad vehicle scanner market incl. non-ionizing modalities | Broader-scope analysis |
| USD 3.40 Billion | 2030 | 2030 | 5.4% | All vehicle scanner types (X-ray, radar, IR) | Broad-scope estimate |
| USD 8.30 Billion | 2030 | 2030 | 9.4% | Broad vehicle scanner incl. radar, thermal, AI systems | Broad-scope analysis |
Our analysis suggests the X-ray-specific estimates (USD 2.3–2.5 billion in 2026 at ~9.4–9.7% CAGR) are more defensible for this keyword because they exclude non-ionizing modalities now growing faster than X-ray. The wider 3.3% CAGR figure reflects a broader scanner market where legacy analog installations dilute the growth rate. Buyers should anchor forecasts to the X-ray-native 9%+ trajectory.
Segmentation splits X-ray vehicle scanner demand along hardware form factor, application vertical, and component/services mix — with the fixed, government, and product-led segments each holding majority share in 2026.
| Parent Segment | Children | Share / Growth Signal |
|---|---|---|
| By Type | Fixed (drive-through), Portable / Mobile | Fixed ~65%; portable growing ~10.1% CAGR |
| By Application | Government / Critical Infrastructure Protection, Private / Commercial | Government ~66.5%; private ~10.4% CAGR |
| By Component | Product (hardware), Services (installation, maintenance, AI subscriptions) | Product ~78%; services ~10.8% CAGR |
| By Structure Type | Drive-Through, Under-Vehicle Surveillance, Portal/Gantry, Others | Drive-through dominant |
| By Technology | X-Ray Backscatter, Dual-Energy Transmission, Gamma-Ray, Multi-Energy Imaging | Backscatter ~37% share; transmission strong in deep-inspection lanes |
This mix implies that vendors with a services-first business model can compound revenue materially faster than cabinet-only suppliers. Software and AI-attached services already account for 25–30% of total revenue across the broader scanner market, per one published estimate.
North America leads the X Ray Vehicle Scanner Market with roughly one-third of global revenue in 2026, driven by federal border budgets, a mature replacement cycle, and CBP's non-intrusive inspection modernization program.
| Region | Market Share (%) |
|---|---|
| North America | 0.33% |
| Europe | 0.27% |
| Asia Pacific | 0.24% |
| Latin America | 0.08% |
| Middle East & Africa | 0.08% |
Our analysis suggests Asia Pacific will narrow the gap with North America by 2031 as smart-gate rollouts in China, India, and ASEAN scale, though federal budget cycles in the US will preserve North American leadership through the mid-2020s.
Border-security mandates and AI-enabled detection software are the dominant growth engines; capital intensity and siting complexity are the principal brakes.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Border / port security mandates | Driver | High | US CBP NII + EU UCC create multi-year procurement calendars |
| Trade volume & container throughput | Driver | High | WTO merchandise trade +2.7% in 2025; intra-Asian corridors faster |
| AI-assisted anomaly detection | Driver | High | 90%+ reduction in false positives; supports 25–30% services revenue share |
| Non-ionizing shift | Mixed | Medium | Removes radiation-risk compliance; may cap X-ray growth in EU tenders |
| Smart-gate and automated clearance | Driver | Medium | Singapore ICA, ASEAN customs programs |
| High capex & siting complexity | Restraint | High | Multi-million USD per installation; shielding, power, lanes required |
| Budget volatility in emerging markets | Restraint | Medium | FX and fiscal pressure delay tenders in LatAm, Africa |
The balance of evidence favors sustained high-single-digit growth: mandates are legislated, not discretionary, and modernisation budgets are already appropriated. The principal risk is not demand destruction but margin compression as hardware becomes commoditised and value migrates to the inference/software layer. Our analysis suggests that by 2030, services and AI subscriptions could account for 35–40% of vendor revenue mix.
The competitive field is moderately consolidated, led by Nuctech, Leidos, Smiths Detection and LINEV Systems, with Rapiscan (OSI), Astrophysics and Gatekeeper competing on price, portability and regional strength.
| Vendor | HQ / Origin | Core Strength | Strategic Position |
|---|---|---|---|
| Nuctech | China | Broad installed base; cost-competitive X-ray and multi-energy systems | Global leader by share; strong in emerging markets |
| Leidos | USA | Homeland security, defense-grade screening, mobile units | Strong US federal footprint; AI integration |
| Smiths Detection | UK | High-resolution imaging, AI-enhanced threat detection | Premium vendor in EU / NA high-security sites |
| LINEV Systems | Luxembourg / USA | High-energy vehicle inspection, customs-focused screening | Niche leadership in drive-through cargo lanes |
| Rapiscan (OSI Systems) | USA | Modular VRT drive-through, cloud/AI monitoring | Scalable, flexible deployment |
| Astrophysics | USA | Cost-efficient X-ray, low-maintenance design | Strong Asia-Pacific and MEA traction |
| Gatekeeper Security | USA | Under-vehicle surveillance and integrated checkpoint | Niche UVSS+scanner bundle leader |
Differentiation is shifting from imaging resolution to software inference quality, service uptime, and interoperability with customs and border-management platforms. Vendors with strong government relationships and proven deployment histories retain pricing power; challengers compete on portability and total cost of ownership.
Procurement is now a multi-year, outcome-based decision, not a single capital purchase. Buyers should evaluate total cost of ownership across a 7–10-year lifecycle, including radiation shielding, siting, power, maintenance contracts, software subscriptions, operator training, and decommissioning. High-energy drive-through systems can exceed multi-million-dollar installation costs, making siting and infrastructure planning as important as the scanner specification itself.
Regulatory compliance is a material selection criterion. IAEA General Safety Requirements Part 3, EU labor directives on non-ionizing modalities, and national radiation-safety regimes are tightening. In European tenders, non-ionizing alternatives are increasingly preferred for passenger-vehicle screening, and X-ray vendors must demonstrate dose-management and occupational-safety controls. Buyers should also demand AI-enabled automated threat recognition with measurable false-positive rates, integration with customs management systems, and remote diagnostics for uptime guarantees.
Switching costs are high once a lane is commissioned — siting, shielding, and integration create lock-in. That argues for multi-vendor strategies and for negotiating data-portability and software-exit clauses up front. The biggest procurement risk is over-specifying hardware and under-specifying throughput and detection KPIs; contracts should tie payments to measured scan rates and threat-detection outcomes.
The balance of evidence favors a bullish but disciplined view of the X Ray Vehicle Scanner Market: 9%+ CAGR is structurally supported by legislated mandates and appropriated budgets through 2030, even as the technology mix shifts. The strongest counter-argument is that non-ionizing modalities (millimeter-wave, passive terahertz) could displace X-ray in passenger-vehicle lanes faster than expected, compressing the addressable X-ray market in Europe and eventually North America. We judge that risk real but slow-moving — X-ray remains the only modality with deep-penetration capability for cargo and container inspection, which is where most of the value sits.
Our analysis suggests the strategic battleground is the inference layer, not the cabinet. Vendors that pair hardened hardware with differentiated AI, remote monitoring, and inspection-as-a-service contracting will capture disproportionate margin as hardware commoditises. Operators that lock in legacy backscatter hardware without software refresh paths risk 20–30% lifecycle cost penalties by 2030.
Actionable strategy:
What would change our conclusion: evidence of accelerated EU regulatory bans on X-ray passenger-vehicle screening, or a step-change in millimeter-wave penetration depth that erodes X-ray's cargo-lane advantage. Absent those, the X-ray-specific 9%+ growth case is well supported.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.4% from 2020-2034 |
| Segmentation |
|
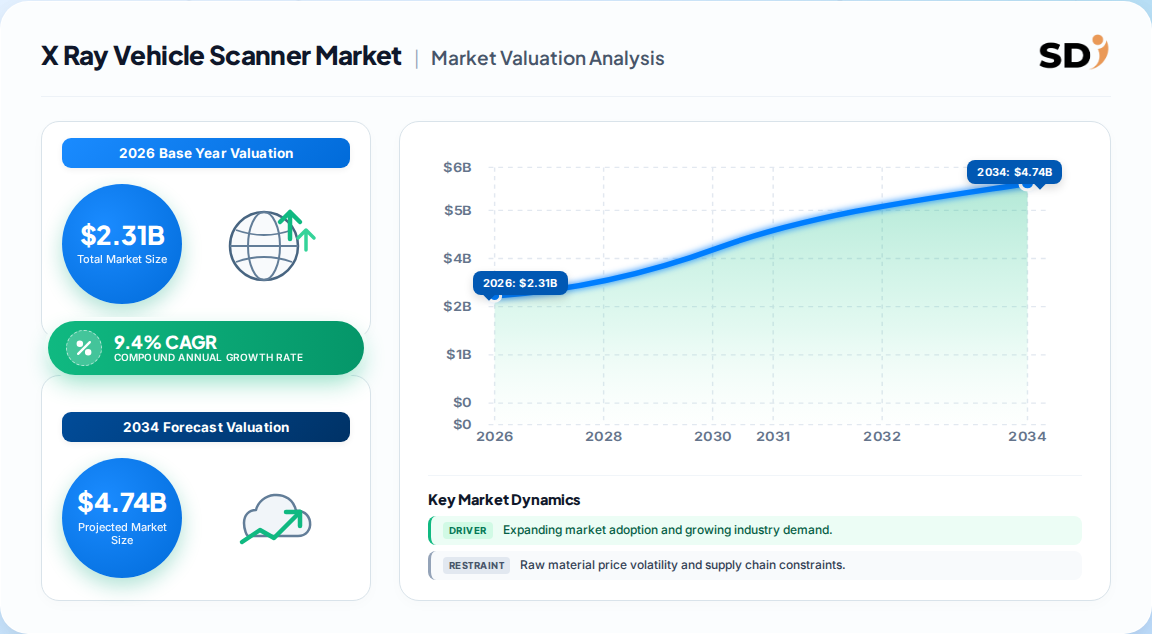
The global X Ray Vehicle Scanner Market is valued at approximately USD 2.31 Billion in 2026 and is projected to reach USD 4.34 Billion by 2033, expanding at a 9.4% CAGR over the forecast period.
North America leads with roughly one-third of global revenue, supported by US CBP non-intrusive inspection modernization and a mature replacement cycle. Asia Pacific is the fastest-growing region, driven by smart-gate rollouts.
Nuctech leads by installed base, followed by Leidos, Smiths Detection, LINEV Systems, Rapiscan Systems (OSI), Astrophysics and Gatekeeper Security. Competition is shifting from imaging hardware to AI-enabled detection software.
Government and critical infrastructure protection accounts for about 66.5% of demand, covering border crossings, ports and military sites. Private-sector logistics, ports and fleet operators are the fastest-growing segment at roughly 10.4% CAGR.
Legislated border and port security mandates, rising trade volumes, and AI-assisted anomaly detection that cuts false positives by over 90%. Modernisation budgets such as the US CBP NII program and EU Union Customs Code enforcement anchor multi-year procurement.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research operates on a 70/30 primary-to-secondary split. We conducted in-depth interviews across the X-ray vehicle scanner value chain: high-energy X-ray source and detector suppliers, scanner OEMs, systems integrators, customs and border agencies, and port/logistics operators. Decision-maker roles interviewed include Heads of Border Technology Procurement, Directors of Port Security Operations, Chief Radiation Safety Officers, and Commercial Directors at screening-equipment vendors.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Border Technology & Procurement Heads | 35% |
| Port & Facility Security Directors | 30% |
| Radiation Safety & Compliance Officers | 20% |
| Vendor Commercial & Product Directors | 15% |
| Company Type | Representation (%) |
|---|---|
| Scanner OEMs & Imaging Equipment Manufacturers | 40% |
| X-Ray Source, Detector & Component Suppliers | 25% |
| Systems Integrators & Software/AI Providers | 20% |
| Customs, Border & Port Operators (End Users) | 15% |
Secondary validation draws on UN Comtrade and WTO merchandise-trade data, US ITC and Eurostat customs statistics, customs-agency appropriations disclosures (e.g., CBP budget justifications), corporate 10-K/SEC filings, patent databases, and IAEA radiation-safety standards (GSR Part 3). We cross-reference vendor annual investor presentations with public tender records to validate installed-base and replacement-cycle assumptions.
We triangulate simultaneously top-down (macro security budgets, customs modernisation appropriations, regional capex allocation) and bottom-up (unit shipments at border crossings, seaports and private facilities × average selling price, plus attached software and services revenue). Forecasts layer installed-base replacement cycles onto new-lane commissioning schedules.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |