 Automotive Data Management Market
: 2026 Global Outlook
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 216

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Automotive Data Management Market
Sadashiv Parab
Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 5.840 B |
| 2025 | 7.120 B |
| 2026 | 8.680 B |
| 2027 | 10.58 B |
| 2028 | 12.89 B |
| 2029 | 15.71 B |
| 2030 | 19.14 B |

The automotive data management market covers platforms and services that collect, normalize, store, secure, govern, analyze, and share vehicle, fleet, production, and partner data. It spans in-vehicle edge processing, cloud and hybrid storage, compliance tooling, and analytics used for predictive maintenance, engineering feedback, and data monetization.
This report sizes software and services across connected vehicles, fleet telematics, production systems, and partner data networks, including edge runtimes, cloud ingestion, governance, analytics, and monetization platforms. This analysis does not cover vehicle hardware sales, standalone telematics device revenue, or the underlying semiconductor and sensor component markets.
The market is genuinely large and accelerating, but published estimates diverge sharply because base years, scope boundaries, and definitions of "data management" differ. The table below sets out the principal competing estimates and the definitional choices behind each.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 5.84 Billion | 2024 | 2030 | 21.88% | End-to-end software, edge runtimes, telematics ingestion, cloud storage, compliance | One published estimate (Marqstats) |
| USD 2.6 Billion | 2025 | 2035 | 17.8% | Platforms and services collect-to-share, excluding vehicle hardware | One competing analysis (GMI) |
| USD 2.69 Billion | 2025 | 2030 | 19.69% | Software/services by component, vehicle, deployment, data type | A separate published estimate (Mordor) |
| USD 1.58 Billion | 2021 | 2030 | 20.3% | Software and services, narrower legacy connected-car base | A historic-baseline estimate (GVR) |
Our analysis indicates the USD 5.84 Billion 2024 figure is the most defensible because it is built bottom-up from audited OEM software expenditure disclosures, enterprise cloud agreements, and statutory registration data, calibrated against a connected parc of 395.1 million units in 2024. The lower estimates likely exclude edge runtime licensing or broader telematics ingestion, which mechanically reduces stated value. The implication is that buyers evaluating vendors against "market size" should align scope definitions first, because headline numbers are not directly comparable.
Segmentation matters because growth is concentrated in specific pockets, notably autonomous validation, unstructured sensor data, and cloud and hybrid deployment. The table below summarizes the principal non-geography segments and their relative position.
| Parent Segment | Children | Leading Sub-Segment | Growth Signal |
|---|---|---|---|
| Component | Software, Services | Software (~64–76% share) | Services ~20–22% CAGR |
| Vehicle Type | Autonomous, Non-Autonomous | Non-autonomous (~55–69% share) | Autonomous ~21–28% CAGR |
| Deployment | Cloud, On-Premise, Hybrid | Cloud (~60–72% share) | Cloud ~26% CAGR to 2030 |
| Data Type | Structured, Unstructured | Structured (~55–57% share) | Unstructured ~19–30% CAGR |
| Application | ADAS/AD Validation, Predictive Maintenance, Fleet Intelligence, Monetization, Compliance | ADAS/AD validation (39.04%) | Rising to 43.99% by 2030 |
Three structural readings follow. First, software dominance reflects the fact that data management is fundamentally a platform business with recurring licensing economics, while services grow faster as OEMs outsource compliance and integration complexity. Second, autonomous-vehicle growth at up to 27.54% CAGR, despite a smaller base, signals where platform requirements will be redefined rather than merely extended. Third, unstructured data is the hardest engineering problem: LiDAR, radar, and imaging streams overwhelm classical relational storage, so vendors with proven lossless compression and tiered retention hold disproportionate advantage.
North America leads with 40.92% of global value in 2024, supported by hyperscaler concentration, mature connected-vehicle programs, and early monetization, though Asia-Pacific is the fastest-growing region at 25.24% CAGR through 2030.
| Region | Market Share (%) |
|---|---|
| North America | 0.39% |
| Europe | 0.25% |
| Asia-Pacific | 0.28% |
| South America | 0.04% |
| Middle East & Africa | 0.04% |
The regional story is paradoxical. North America's dominance rests less on vehicle volume than on infrastructure: hyperscalers, regulatory precedent, and OEM software revenue targets such as Stellantis's EUR 20 Billion ambition. Europe's position is shaped by regulation—UNECE R155 cybersecurity mandates and GDPR penalty exposure of up to 4% of global turnover—which converts governance from a cost center into a purchase criterion. Asia-Pacific's 25.24% CAGR reflects China's NEV parc exceeding 12.9 million units in 2024 and GB/T 32960 reporting obligations, plus India's AIS-140 requirements. Our analysis suggests APAC architectures will be designed around localized compliance as much as around vehicle volume, which favors regional cloud and hybrid deployments over global single-stack designs. That fragmentation has a commercial consequence: vendors seeking APAC share must offer sovereign data residency rather than treating compliance as a bolted-on module.
Growth is driven primarily by connected-vehicle data explosion and regulatory mandates, while cybersecurity compliance burden and sensor storage costs are the principal restraints; the net balance strongly favors expansion through 2030.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Connected vehicles and IoT sensor data | Driver (+1.6% CAGR) | High | 100+ sensors per vehicle; several GB to 4 TB per day needing normalization |
| Regulatory mandates (UNECE R155, GDPR, PIPL, GB/T 32960) | Driver (+0.4% CAGR) | High | Governance, consent, lineage, and audit become mandatory platform features |
| Predictive maintenance demand | Driver | High | 30–50% unplanned downtime reduction in commercial fleets |
| OEM data monetization | Driver (+0.7% CAGR) | Medium | Consent-managed exchanges with insurers, fleets, mapping providers |
| Cybersecurity compliance burden | Restraint (1.5% CAGR drag) | High | Certification, audit, and personnel costs stall smaller OEM programs |
| Sensor data storage cost | Restraint (1.3% CAGR drag) | Medium | Petabyte-scale retention economics remain difficult |
| Cloud latency and bandwidth gaps | Restraint (1.1% CAGR drag) | Medium | Rural and safety-critical real-time use cases |
The driver/restraint balance is asymmetric: data generation compounds faster than storage costs decline, while regulation raises the floor of mandatory spend. Edge processing is the critical relief valve—compressing 5–20 TB per vehicle per day to under 250 MB transmits 99.7% less data and makes fleet-wide cloud telemetry economically viable. The second-order effect is strategic: vendors that only sell cloud storage face margin compression, whereas vendors offering edge-agent integration capture value at the point of data creation. The counter-argument worth naming is that monetization revenue has underperformed badly—independent brokers Wejo and Otonomo combined for only USD 14.05 million peak annual revenue—implying that promises of data-marketplace upside should be discounted relative to compliance and engineering efficiency.
The market is fragmented, with hyperscalers leading, top five players holding 28.7% combined share in 2025, and AWS holding over 11.5% alone, ahead of Google Cloud, Microsoft Azure, SAP, and IBM.
| Vendor | Position | Differentiation | Moat Type |
|---|---|---|---|
| Amazon Web Services | Leader (~11.5%+ share) | FleetWise edge integration; broad OEM cloud migrations | Infrastructure scale and tooling ecosystem |
| Microsoft Azure | Strong | Mobilisights marketplace hosting; enterprise integration | Enterprise relationships and hybrid cloud |
| Google Cloud | Strong | Data analytics and AI toolchain depth | Analytics and model-training capability |
| SAP | Strong | Enterprise data governance and ERP linkage | Enterprise process embeddedness |
| IBM | Strong | Governance, security, and regulated-industry credentials | Compliance trust and services bench |
| Bosch Mobility / Continental | Specialist | Tier-1 vehicle integration and sensor-domain expertise | Automotive engineering proximity |
| Stellantis Mobilisights / BMW Cloud Data Hub | First-party OEM | Direct vehicle data access and consent control | Proprietary data position |
The competitive moat is migrating. Pure cloud infrastructure is commoditizing, so advantage now accrues to vendors that combine edge runtimes with policy enforcement and proven automotive certification. First-party OEM platforms such as Mobilisights and BMW's Cloud Data Hub represent a structural threat to independent brokers, which have largely failed commercially. Our analysis suggests the durable position sits with vendors that can demonstrate both regulatory auditability and edge-to-cloud economics, not with those selling storage capacity alone.
Procurement here is a decade-long architectural commitment, and selection criteria should be weighted accordingly. The dominant risk is regulatory: UNECE R155 certification, GDPR exposure up to 4% of global turnover, and jurisdiction-specific rules (PIPL, CCPA/CPRA, DPDP, LGPD) mean governance capability is a hard requirement, not a feature comparison line. A 2024 incident in which a misconfigured storage bucket exposed telemetry and centimeter-level geolocation for roughly 800,000 Volkswagen Group EVs demonstrates that security architecture failures carry reputational and legal consequences far exceeding licensing savings.
Switching costs are severe and asymmetric. Once telemetry pipelines, edge agents, and governance catalogs are embedded across fleets, migration involves re-certification, re-validation, and integration rework, so buyers should evaluate exit terms and data portability before signing. Realistic total cost of ownership must include edge compute lifecycle, egress, and retention tiering, because raw sensor volumes make naive cloud storage uneconomic. Finally, buyers should stress-test vendor claims against a pilot: verify actual compression ratios, latency under network slicing, and audit-report generation, rather than accepting benchmark slides.
The balance of evidence favors a 2030 market near USD 19 Billion at roughly 22% CAGR, with scope adjustments explaining the gap to lower estimates rather than any genuine disagreement about direction. Connected-vehicle data generation is compounding faster than storage costs fall, and regulation is raising the mandatory spend floor across every major jurisdiction. Growth is therefore structural, not cyclical, and the principal uncertainty is not whether demand exists but who captures it.
The strongest counter-argument is monetization. Independent vehicle-data brokers effectively failed—Wejo entered administration and Otonomo completed a distressed merger—and Stellantis's connected fleet of 13.80 million vehicles yields only 5.00 million paying software subscribers, a 36.23% conversion rate. If OEM software revenue targets prove unattainable, the market shrinks toward compliance and engineering spend. We judge this risk real but insufficient to reverse the forecast, because regulatory and engineering demand does not depend on monetization succeeding.
Actionable Strategy:
What would change our conclusion: sustained evidence that OEM software subscription conversion remains below 40% at scale, or a major jurisdiction delaying enforcement of UNECE R155 or GB/T 32960, would materially reduce the growth trajectory. Conversely, proof of profitable third-party data exchange economics would raise the upper bound.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 21.88% from 2020-2034 |
| Segmentation |
|
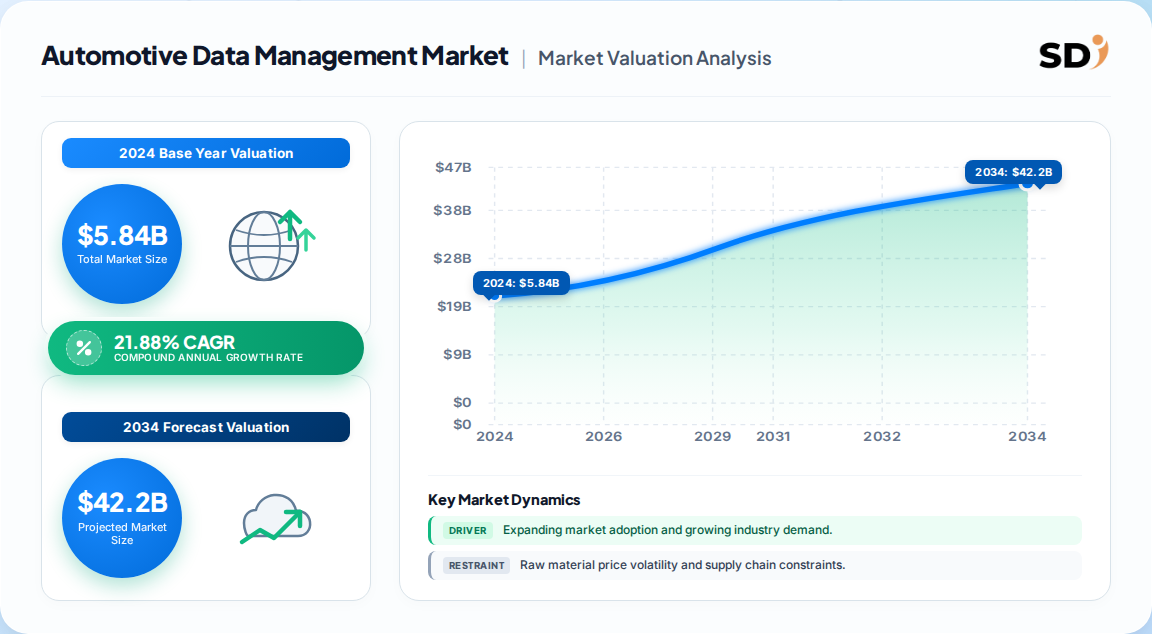
The market reached USD 5.84 Billion in 2024 and is projected to reach USD 19.14 Billion by 2030. Lower published estimates of USD 2.6–2.7 Billion reflect narrower scope definitions that exclude edge runtimes or telematics ingestion.
Growth compounds at 21.88% CAGR from 2024 to 2030, representing an absolute increase of USD 13.30 Billion. Alternative estimates range from 17.8% to 20.3%, reflecting differing base years and scope boundaries.
North America leads with 40.92% of global value in 2024, driven by hyperscaler concentration and mature connected-vehicle programs. Asia-Pacific is the fastest-growing region at 25.24% CAGR through 2030.
Amazon Web Services leads with over 11.5% share, followed by Google Cloud, Microsoft Azure, SAP, and IBM, which together held 28.7% in 2025. Tier-1 specialists and first-party OEM platforms compete on vehicle integration.
Cybersecurity compliance burden, sensor data storage costs, and cloud latency gaps in rural areas are the main restraints. Edge processing that compresses data transmission by up to 99.7% partially offsets these pressures.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research follows a 70/30 primary-to-secondary split, prioritizing direct verification over published inference. In-depth interviews were conducted with stakeholders across the automotive data value chain: connected-vehicle software platform providers, Tier-1 electronics suppliers, OEM data and digital officers, hyperscale cloud infrastructure vendors, and fleet telematics operators. Within these organizations we targeted decision-makers holding VP of Vehicle Data and Software roles, Heads of Connected Vehicle Engineering, Technical Directors of Data Governance, and Commercial Operations Leads responsible for data monetization programs. Interview guides probed deployment architecture, edge-versus-cloud trade-offs, regulatory certification pathways, and subscription conversion economics, producing qualitative evidence that was coded and cross-referenced against quantitative disclosures.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Vehicle Data & Software VPs | 35% |
| Connected Vehicle Engineering Heads | 30% |
| Data Governance Technical Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Cloud & Platform Providers | 40% |
| OEM Data & Software Entities | 30% |
| Tier-1 Electronics Suppliers | 20% |
| Fleet Telematics Operators | 10% |
All quantitative claims were triangulated against official multilateral and regulatory sources rather than competitor research. We drew on UNECE vehicle regulation texts, European Commission data-protection guidance, national statistical supply-and-use tables (including OECD Statistics and Data Directorate publications), connected-vehicle parc statistics from the International Energy Agency, and corporate annual filings including Form 10-K disclosures and investor presentations. Patent databases and recognized industry standards bodies supplemented technical validation of edge-processing and telematics architectures.
We ran simultaneous top-down and bottom-up models. The top-down path allocates macroeconomic automotive software expenditure across segments and regions using harmonized supply-and-use classifications. The bottom-up path aggregates audited OEM software spend disclosures, enterprise cloud agreements, and per-vehicle licensing fees, calibrated against connected-vehicle parc volumes. Divergence between the two paths was reconciled at segment level before finalization.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |