 Turkey Automotive Plastic Compounding Market
 2025
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 268

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Turkey Automotive Plastic Compounding Market
Sadashiv Parab
Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 336.0 M |
| 2025 | 357.0 M |
| 2026 | 380.0 M |
| 2027 | 403.0 M |
| 2028 | 429.0 M |
| 2029 | 456.0 M |
| 2030 | 486.0 M |

The Turkey automotive plastic compounding market covers the industrial blending of base polymers—PP, ABS, PU, PVC, PE, PC, PA and TPE—with additives, fillers and reinforcements to produce automotive-grade thermoplastic compounds sold to Turkish OEMs and tier suppliers for interior, exterior, powertrain and under-the-hood components.
This report covers Turkish-domiciled and Turkey-serving compounders producing automotive-grade thermoplastic compounds, segmented by product chemistry and application across instrument panels, powertrain, door systems, interior components, exterior fascia and under-the-hood parts. Volume and value are measured at compounder-gate. This analysis does not cover base polymer resin production, masterbatch and colorant-only suppliers, aftermarket replacement parts, or global compounding markets beyond their relevance to Turkish supply.
The Turkey automotive plastic compounding opportunity is best anchored near 357 Million in 2025, but published estimates diverge materially—driven by differing base years, currency handling and whether value is captured at compounder gate or OEM spend.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 337.9 Million | 2023 | 2030 | 6.3% | Compounder-gate value, product and application segmentation | One published estimate |
| 290.9 Million | 2020 | 2028 | 5.8% | Broader polymer set incl. PE, PC, PA, TPE | A competing analysis |
| 304.9 Million | 2021 | 2028 | 5.8% | Product-level, application-level forecasts | A competing analysis |
| 357 Million (2025) | 2025 | 2030 | 6.3% | Consensus mid-point, extended from 2023 base | Our synthesis |
The 2023-based 6.3% figure is the most defensible: it is the most recent, reflects post-2023 EV and export recovery, and its scope aligns with the product segmentation used in this report. The older 5.8% series is likely understated because it was anchored in pre-2021 lira volatility and pre-Togg production ramp. Our analysis suggests the true 2024–2030 trajectory sits at the upper end of the 5.8–6.3% band given Turkey's export orientation and EV localization incentives.
Segmentation runs on two axes—polymer chemistry and vehicle application zone—with product chemistry determining performance envelope and application determining qualification stringency.
| Parent segment | Children |
|---|---|
| By Product | ABS, PP, PU, PVC, PE, PC, PA, TPE, Others |
| By Application | Instrument Panels, Powertrain, Door Systems, Interior Components, Exterior Fascia, Under-the-hood Components, Others |
PP dominates because its specific gravity and cost-performance balance suits high-volume interior and under-hood parts. ABS holds premium interior trim and instrument-panel substrates. PA and PC/ABS blends are the growth chemistries for under-the-hood and EV structural parts, where thermal and dimensional stability matter more than unit cost. Our analysis suggests PA and PC will outgrow PP in percentage terms through 2030, but PP will retain absolute leadership.
Marmara leads Turkey's automotive plastic compounding landscape, concentrating OEM assembly, tier-one supplier parks and compounder capacity around Istanbul, Bursa and Kocaeli—the corridor that supplies Ford Otosan, Togg, Toyota and Hyundai plants.
| Region | Market Share (%) |
|---|---|
| Marmara | 0.42% |
| Central Anatolia | 0.24% |
| Aegean | 0.16% |
| Black Sea | 0.09% |
| Southeastern & Eastern | 0.09% |
| Parent | Children |
|---|---|
| Marmara | Istanbul, Bursa, Kocaeli, Sakarya |
| Central Anatolia | Ankara, Konya, Eskişehir |
| Aegean | Izmir, Manisa, Aydın |
| Black Sea | Samsun, Trabzon |
| Southeastern & Eastern | Gaziantep, Şanlıurfa |
Marmara's dominance is structural: proximity to assembly plants, port access for EU export, and the density of Petkim-linked polymer logistics. Central Anatolia is emerging as a secondary node via Togg's Gemlik-adjacent ecosystem and Ankara's defense-adjacent manufacturing. The Aegean benefits from Izmir's export terminals. Buyers should treat Marmara as the default procurement base but hedge with Aegean capacity to reduce single-corridor risk.
The primary growth engine is the convergence of EU emissions compliance and Turkey's position as a low-cost, EU-adjacent export platform—lightweighting is not optional for Turkish exporters selling into Euro 6 and Euro 7 markets.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| EU emissions regulation (Euro 6/7) | Driver | High | Mandates lightweighting for export-bound vehicles |
| EV localization (Togg, incentives) | Driver | High | New part designs demand PA, PC, and flame-retardant compounds |
| Per-capita plastics gap vs. Europe | Driver | Medium | Headroom for domestic compound consumption growth |
| Low-cost workforce and EU-Asia corridor | Driver | High | Sustains export competitiveness |
| Volatile crude oil and naphtha prices | Restraint | High | Compresses compounder margins and destabilizes pricing |
| Lira volatility and import dependency | Restraint | High | Raises working-capital and hedging costs |
| Fragmented domestic compounding capacity | Restraint | Medium | Limits scale economies vs. European majors |
The driver-restraint balance favors growth, but the margin story is more cautious. Volatile feedstock costs and lira depreciation mean revenue growth may not translate proportionally to compounder profitability. Our analysis suggests the strongest risk-adjusted opportunity sits with compounders that have locked-in export contracts and feedstock pass-through clauses.
The Turkey automotive plastic compounding landscape is moderately consolidated, with domestic polymer majors, specialized compounders and global distributors competing on formulation depth, OEM qualification and logistics.
| Company | Type | Primary strength | Differentiation |
|---|---|---|---|
| Petkim Petrokimya | Domestic polymer major | Integrated feedstock | Cost leadership, PP/PE base resin integration |
| Alfa Polimer İnovasyon | Domestic compounder | Custom formulation | Application engineering for OEMs |
| Tisan Mühendislik Plastikleri | Domestic compounder | Engineering plastics | PA, PC, specialty grades |
| EPSAN | Domestic compounder | Automotive-focused | Tier-supplier relationships |
| Elastron TPE | Domestic TPE specialist | Thermoplastic elastomers | Niche TPE leadership |
| PolyOne (Avient) | Global specialty | Colorant and compound | Global formulation IP |
| LyondellBasell | Global integrated | PP compounding | Scale and global OEM approvals |
| SABIC | Global integrated | Engineering plastics | PC, PA portfolio depth |
| Ravago | Global distributor | Distribution and recycling | Channel reach and circularity |
| LANXESS | Global specialty | High-performance compounds | Under-hood and structural grades |
Domestic players compete on cost, responsiveness and OEM proximity; global players compete on formulation IP, global OEM approvals and supply reliability. The moat for domestic compounders is OEM qualification cycles, which are sticky once passed. The moat for global players is cross-border platform approvals that domestic firms cannot easily replicate.
Buyers should prioritize OEM qualification status and formulation traceability over headline price—switching a qualified compound on a safety-critical part carries requalification costs and timeline risk that often exceed unit savings. Procurement risk concentrates in feedstock volatility: PP and PA prices track naphtha and benzene, so contracts without pass-through clauses transfer margin risk to the buyer during price spikes. Supply concentration in Marmara creates single-corridor exposure to seismic and logistics disruption; dual-sourcing across Marmara and Aegean is prudent.
Regulatory compliance is non-negotiable for export-bound programs: EU REACH, ELV directive recyclability targets and Euro 7 emissions indirectly mandate specific compound performance. Operators should verify that compounders maintain documented REACH registrations and recyclate-content capability. Our analysis suggests recyclate-content readiness will become a qualification gate for EU-bound programs by 2027–2028, and compounders without it will be excluded from new platform awards. Switching costs are highest for under-hood and structural parts, where thermal and fatigue validation cycles run 12–24 months.
The balance of evidence favors a constructive but selective view of the Turkey automotive plastic compounding market. The 6.3% CAGR is credible and above global benchmarks, but it is export- and EV-driven rather than broad-based domestic demand. The strongest counter-argument is feedstock and currency risk: a sustained lira depreciation episode or naphtha spike could compress compounder margins faster than volume growth can offset, and the 5.8% older estimates may prove closer to reality if EU automotive demand softens.
Our judgment is that the growth is real but unevenly captured. Compounders with export contracts and engineering-plastic portfolios (PA, PC, TPE) will outperform those concentrated in commodity PP for domestic OEMs. The Togg ecosystem and EV localization incentives create a genuine new demand pool, but qualification timelines mean revenue realization lags investment by 18–24 months.
Actionable strategy:
What would change our conclusion: a sharper-than-expected EU automotive demand contraction, removal of Turkish EV incentives, or a structural lira crisis that breaks feedstock import economics. Absent those, the 6.3% trajectory holds.
Note: Precise sub-segment forecasting—by chemistry, application and sub-region—requires the full report's granular model, which reconciles the divergent published estimates shown above.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.3% from 2020-2034 |
| Segmentation |
|
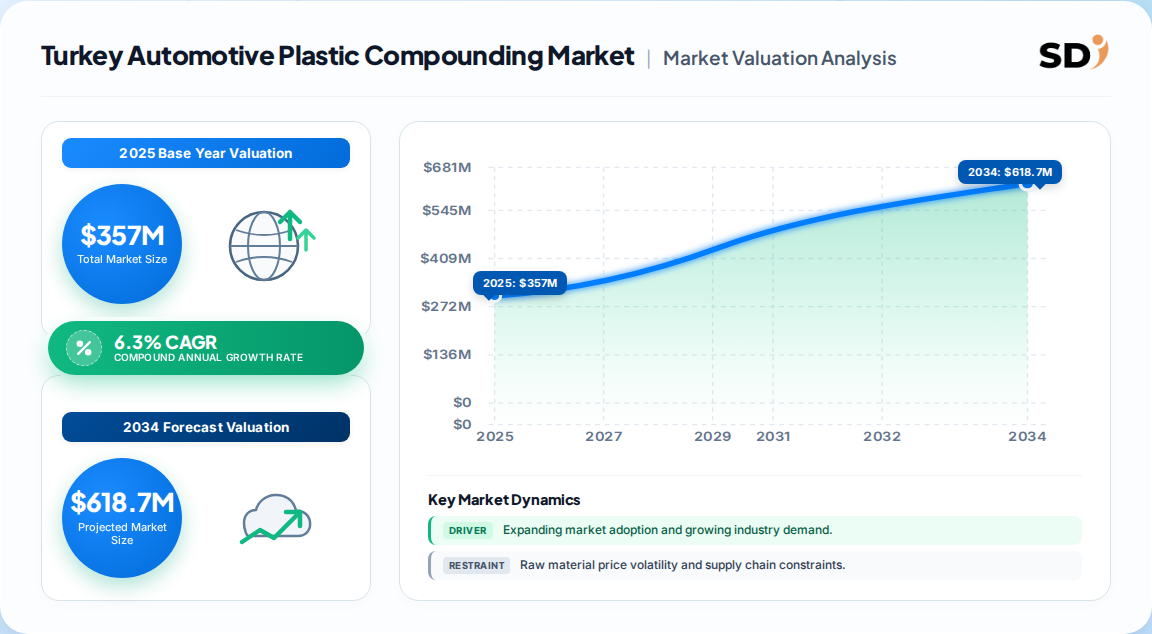
The market was valued at approximately 357 Million in 2025 and is forecast to reach roughly 486 Million by 2030, expanding at a 6.3% CAGR. Published estimates range from 290.9 Million (2020 base) to 337.9 Million (2023 base), reflecting differing scopes and base years.
Exterior fascia and under-the-hood components are the fastest-growing application segments, driven by lightweighting and energy-management requirements. Among chemistries, PA and PC are outpacing PP in percentage growth, though PP retains absolute leadership at roughly 32% share.
Leading players include Petkim Petrokimya, Alfa Polimer, Tisan Mühendislik Plastikleri, EPSAN, Elastron TPE, plus global participants such as LyondellBasell, SABIC, PolyOne (Avient), LANXESS, ALBIS and Ravago. The market is moderately consolidated with strong OEM qualification moats.
EU emissions regulations (Euro 6/7), EV localization incentives including the Togg program, Turkey's low-cost EU-adjacent export position and headroom in per-capita plastics consumption are the primary demand drivers. Feedstock volatility and lira depreciation are the main restraints.
Marmara leads, concentrating OEM assembly and compounder capacity around Istanbul, Bursa and Kocaeli. Central Anatolia is emerging as a secondary node via the Togg ecosystem, while the Aegean benefits from Izmir's export terminals.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with raw material and polymer producers, specialized compounders and formulators, contract blenders, and global and regional distributors serving Turkish OEMs. Interviewees were drawn from decision-maker roles including VP-level Sourcing Directors, Heads of R&D and Application Engineering, Technical Directors, and Commercial Operations Leads. Fieldwork was structured to capture qualification-cycle timing, feedstock pass-through practices and export-contract structure.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Application Engineering Heads | 35% |
| Procurement & Sourcing Directors | 35% |
| Technical & Quality Directors | 30% |
| Company Type | Representation (%) |
|---|---|
| Polymer & Raw Material Producers | 40% |
| Specialized Compounders & Formulators | 35% |
| Distributors & Traders | 25% |
Secondary validation draws on official multilateral trade and standards databases (UN Comtrade, WTO, Eurostat, US ITC), corporate annual filings and investor presentations (10-K, annual reports), patent databases for formulation IP tracking, and recognized technical standards and industry associations. No competitor market-research publications are cited in validation.
Market sizing triangulates simultaneously from the top down (macroeconomic output, automotive production and segment allocation) and bottom up (compounder capacity, product pricing and end-use consumption modeling). Divergent published estimates are reconciled against both approaches.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |