 Automotive Crankshaft Market
 Size, Share & Forecast 2026-2035
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 273

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Automotive Crankshaft Market
Sadashiv Parab
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 9.590 B |
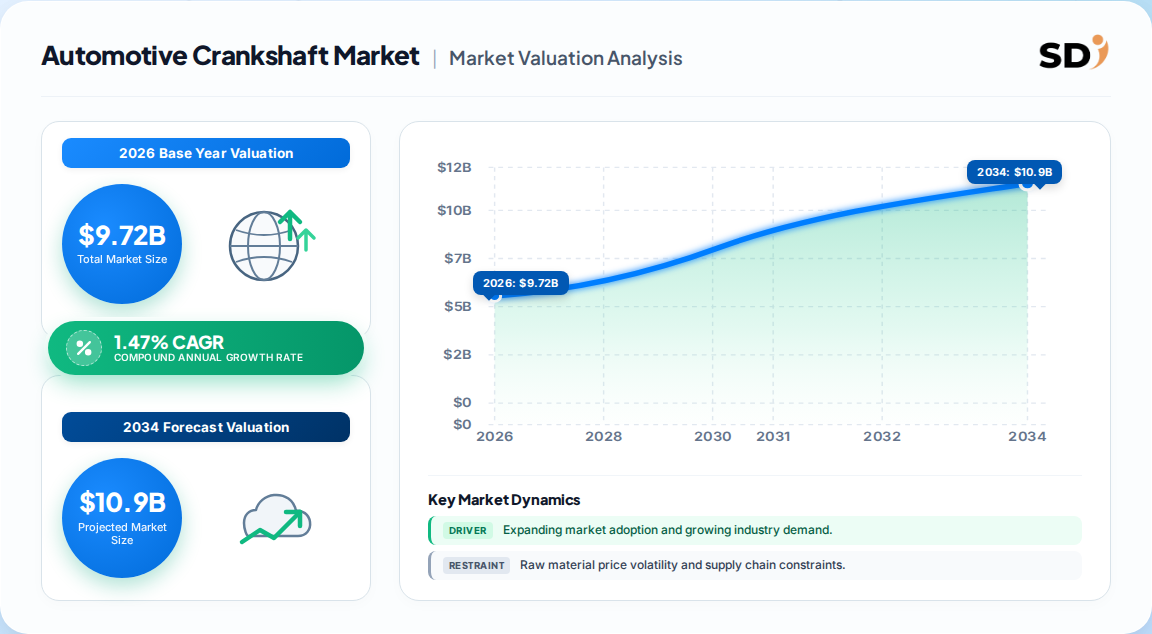
| 2026 | 9.720 B |
| 2027 | 9.870 B |
| 2028 | 10.01 B |
| 2029 | 10.16 B |
| 2030 | 10.31 B |
| 2031 | 10.46 B |

The automotive crankshaft market encompasses the manufacture, supply, and distribution of crankshafts—mechanical components that convert reciprocating piston motion into rotational motion in internal combustion engines—for passenger vehicles, commercial vehicles, two-wheelers, three-wheelers, and off-road applications. It serves OEM assembly lines and the aftermarket replacement channel.
This report covers crankshaft production for ICE and hybrid vehicles across all vehicle types, including forged and cast configurations in steel and iron materials, sold through OEM and aftermarket channels. It analyzes market sizing, segmentation, regional dynamics, and vendor strategy from 2025 to 2035. This analysis does not cover electric-vehicle powertrain components, transmission gears, camshafts, or other engine parts independent of the crankshaft assembly.
The global automotive crankshaft market size is estimated at USD 9.72 billion in 2026, with forecasts converging on moderate single-digit growth through 2035. However, published estimates vary widely depending on scope definitions and material coverage.
| Estimate Source | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| GMI (primary reference) | 2026 | 2035 | 1.47% | Full ICE + hybrid crankshafts, all vehicle types, OEM + aftermarket | One published estimate |
| Alternate analysis A | 2026 | 2034 | 2.25% | Narrower scope: excludes off-road and specialty; passenger/commercial focus | A competing analysis |
| Alternate analysis B | 2026 | 2033 | 4.5% | Includes billet and performance crankshafts; broader material definition | A competing analysis |
Our analysis suggests the 1.47% CAGR figure is the most defensible for strategic planning because it explicitly models the structural volume contraction in crankshaft-bearing vehicle production (from 140.4 million units in 2025 to 114.4 million in 2035). The higher-growth estimates likely reflect narrower scopes that exclude the BEV displacement effect in passenger vehicles. The divergence implies buyers should anchor procurement contracts to the conservative volume trajectory while negotiating value-based pricing on forged-steel and commercial-vehicle programs.
The automotive crankshaft market is segmented by configuration, construction, vehicle type, material, and sales channel, reflecting distinct demand drivers and pricing dynamics across each dimension.
| Parent Segment | Children |
|---|---|
| By Crankshaft Configuration | Flat Plane, Cross Plane |
| By Crankshaft Construction | Forged Crankshaft, Billet Crankshaft, Cast Crankshaft |
| By Vehicle Type | Passenger Vehicles, Light Commercial Vehicles, Heavy Commercial Vehicles, Two-Wheelers, Three-Wheelers, Off-Road & Specialty |
| By Material | Forged Steel/Alloy, Cast Iron/Steel, Billet Steel, Aluminum Alloys |
| By Sales Channel | OEM, Aftermarket |
Forged crankshafts dominate with 57.2% revenue share, favored for fatigue strength and cost-effectiveness in mass-market vehicles. Billet crankshafts are the fastest-growing configuration, driven by high-performance and motorsport applications. Cross-plane configurations are gaining traction at a 5% CAGR due to V8 engine demand.
Asia Pacific leads the global automotive crankshaft market with approximately 43% revenue share in 2025, underpinned by China, India, and Japan's massive ICE vehicle production bases. Latin America is the fastest-growing region, albeit from a smaller base.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.43% |
| Europe | 0.23% |
| North America | 0.19% |
| Latin America | 0.08% |
| Middle East & Africa | 0.07% |
| Region | Share (2025) | Growth Outlook |
|---|---|---|
| Asia Pacific | 43% | Stable; volume-led |
| Europe | 23% | Moderate; BEV pressure in passenger cars |
| North America | 19% | Steady; commercial vehicle strength |
| Latin America | 8% | Fastest-growing; two-wheeler demand |
| Middle East & Africa | 7% | Emerging; ICE two-wheeler volume |
Crankshaft demand is sustained by global ICE vehicle production recovery, persistent two-wheeler volume in emerging markets, and hybrid powertrain architecture continuity, while BEV penetration and structural volume contraction present the primary restraints.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Global ICE Vehicle Production Recovery | Driver | High (OICA 96.4M units, 2025) | Expands crankshaft procurement across OEM supply chains |
| Persistent ICE Two-Wheeler Volume | Driver | High (ICCT ~65M units, 2025) | Extends aftermarket and OEM demand in Asia and Africa |
| Hybrid Powertrain Architecture | Driver | Medium-High | Retains crankshaft-driven combustion cycles in P2/P4 and 48V hybrids |
| Accelerating BEV Penetration | Restraint | High (IEA >20M EV sales, 2025) | Reduces addressable ICE passenger-vehicle base |
| Structural Volume Contraction | Restraint | High (114.4M units forecast 2035) | Revenue growth must come from value appreciation, not volume |
| Capital Intensity & Process Complexity | Restraint | Medium | Fixed-cost structures constrain margin recovery when volumes decline |
The balance of evidence suggests demand resilience through 2030, supported by hybrid platform continuity and commercial-vehicle strength. However, the post-2030 outlook hinges on BEV adoption pace in China and Europe. Our analysis indicates that suppliers with exposure to small-displacement passenger engines face the greatest risk, while those serving heavy-duty and specialty applications retain pricing power.
The automotive crankshaft market is moderately concentrated, with the top five players holding 27.67% share in 2025. thyssenkrupp leads with 7.37% market share, followed by Kobelco, Nippon Steel, Aichi Steel, and Hyundai WIA.
| Company | Estimated Share (2025) | Strategic Focus | Differentiator |
|---|---|---|---|
| thyssenkrupp | 7.37% | Forged steel crankshafts, global OEM programs | Integrated forging and machining footprint |
| Kobelco | ~5.5% | Steel alloy crankshafts, Asia-Pacific OEMs | Material metallurgy expertise |
| Nippon Steel | ~5.2% | High-strength steel crankshafts | Vertical integration in steel supply |
| Aichi Steel | ~4.8% | Precision forged crankshafts, Japanese OEMs | Toyota group alignment |
| Hyundai WIA | ~4.8% | Crankshafts for Hyundai-Kia platforms | Captive OEM demand |
Differentiation hinges on material metallurgy, forging precision, and OEM qualification cycles, which span multiple production seasons. Competitive moats are built through program-specific tooling investments and localized assembly footprints near expanding OEM hubs. Smaller suppliers face consolidation pressure as OEMs rationalize platforms.
Buyers and operators must prioritize suppliers with multi-platform program awards and demonstrated capability in forged-steel and hybrid-compatible crankshafts, as these segments offer the strongest volume retention through 2030. Procurement risks include capacity underutilization at tier-2 suppliers, prolonged reprice cycles due to fixed-cost structures, and OEM-specific certification timelines that can exceed 12 months. Switching costs are high because crankshafts are engine-program-specific, requiring revalidation and tooling investment. Regulatory compliance with emissions standards (Euro 7, China 6) drives demand for tighter-tolerance, lightweight crankshafts that improve engine efficiency. Operators should also monitor steel price volatility—global steel prices rose from ~USD 500/ton in 2020 to USD 750-800/ton in 2024—which directly impacts crankshaft manufacturing costs and margin recovery.
The balance of evidence favors a value-over-volume strategy for stakeholders in the automotive crankshaft market. The 1.47% CAGR through 2035 masks a bifurcated reality: unit volumes are contracting as BEVs displace ICE passenger cars, but revenue resilience is achievable through forged-steel premiumization, commercial-vehicle mix shift, and hybrid platform continuity. The strongest counter-argument is that faster-than-expected BEV adoption in China and Europe could accelerate volume decline beyond the conservative forecast, particularly for suppliers with concentrated passenger-car exposure. However, hybrid architectures (P2/P4 and 48V) preserve crankshaft-driven combustion cycles and extend OEM tooling reuse, providing a buffer that pure-BEV forecasts often overlook.
Our analysis suggests the most defensible position is to anchor procurement and investment decisions to the conservative volume trajectory while negotiating value-based pricing on high-specification programs. Suppliers should prioritize capacity localization near expanding OEM hubs in Asia Pacific and commercial-vehicle corridors in North America, where forged crankshaft demand is most durable.
Actionable Strategy:
What evidence would change our conclusion: A sustained acceleration in BEV adoption beyond 25% of global light-vehicle sales before 2030, or a policy-driven collapse in ICE two-wheeler demand in Asia, would materially shift the forecast toward the severe decline scenario. Conversely, a slowdown in BEV adoption or a hybrid-led transition would support upside to the volume trajectory.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 1.47% from 2020-2034 |
| Segmentation |
|
The global automotive crankshaft market was valued at USD 9.72 billion in 2026. It is projected to reach USD 11.09 billion by 2035, growing at a 1.47% CAGR from 2026 to 2035, according to the primary reference estimate.
Asia Pacific dominates the automotive crankshaft market with approximately 43% revenue share in 2025. China, India, and Japan drive demand through high ICE vehicle production, while Latin America is the fastest-growing region.
Key drivers include global ICE vehicle production recovery (96.4 million units in 2025), persistent two-wheeler demand in emerging markets (65 million units), and hybrid powertrain architecture continuity that retains crankshaft-driven combustion cycles in P2/P4 and 48V systems.
The top five players are thyssenkrupp (7.37% share), Kobelco, Nippon Steel, Aichi Steel, and Hyundai WIA, collectively holding 27.67% market share in 2025. Differentiation hinges on material metallurgy and OEM program qualification.
The market is segmented by crankshaft configuration (flat plane, cross plane), construction (forged, billet, cast), vehicle type (passenger, commercial, two-wheeler, off-road), material (forged steel, cast iron, billet steel, aluminum), and sales channel (OEM, aftermarket).
Accelerating BEV penetration is the biggest challenge, with global electric car sales exceeding 20 million units in 2025. This reduces the addressable ICE passenger-vehicle base, compressing crankshaft volume from light vehicles, particularly in China and Europe.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is built on a 70/30 primary-to-secondary research split, prioritizing direct industry engagement to validate market sizing and forecast assumptions. We conducted in-depth interviews with stakeholders across the value chain, including raw material suppliers (steel and alloy producers), specialized crankshaft manufacturers (forging and casting specialists), contract machining and heat-treatment providers, and global distributors serving OEM and aftermarket channels. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of procurement, engineering, and commercial perspectives.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement Directors | 30% |
| Heads of R&D & Technical Directors | 35% |
| Commercial Operations Leads | 20% |
| Quality & Regulatory Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Steel Suppliers | 30% |
| Crankshaft Forging & Casting Specialists | 40% |
| Contract Machining & Heat Treatment Providers | 15% |
| Global Distributors & Aftermarket Channel | 15% |
We triangulated primary insights against official multilateral trade and standards databases, including UN Comtrade, WTO, US ITC, and Eurostat, to validate cross-border crankshaft trade flows and regional consumption patterns. Corporate annual filings (10-K, SEC filings, investor presentations) provided capacity and revenue benchmarks for leading manufacturers. Patent databases and technical standards from recognized industry associations informed process-technology assessments and material innovation trends.
Our demand model simultaneously applies Top-Down macro-economic and industry-segment allocation and Bottom-Up manufacturer capacity, product pricing, and end-use consumption modeling. This dual approach reconciles supply-side capacity data with demand-side vehicle production forecasts, producing a validated market size and compound growth projection.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |