Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Urban Air Mobility Market: 2026 Size, CAGR & Growth Outlook
Urban Air Mobility Market
Urban Air Mobility Market: 2026 Size, CAGR & Growth Outlook
Urban Air Mobility Market by Vehicle Type (Piloted, Autonomous), by Range (Intracity, Intercity), by Propulsion (Fully Electric, Hybrid Electric, Gasoline, Hydrogen Fuel Cell), by Application (Passenger Air Taxi, Intra-City Shuttle, Emergency Medical Services, Cargo & Last-Mile), by End User (Ride-Sharing Operators, Healthcare Providers, E-Commerce, Private Operators), by Solution (Platform, Infrastructure), by System (Aerostructure, Avionics, Flight Control, Propulsion, Software), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Middle East & Africa (UAE, Saudi Arabia, South Africa), by Latin America (Brazil, Argentina) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 267
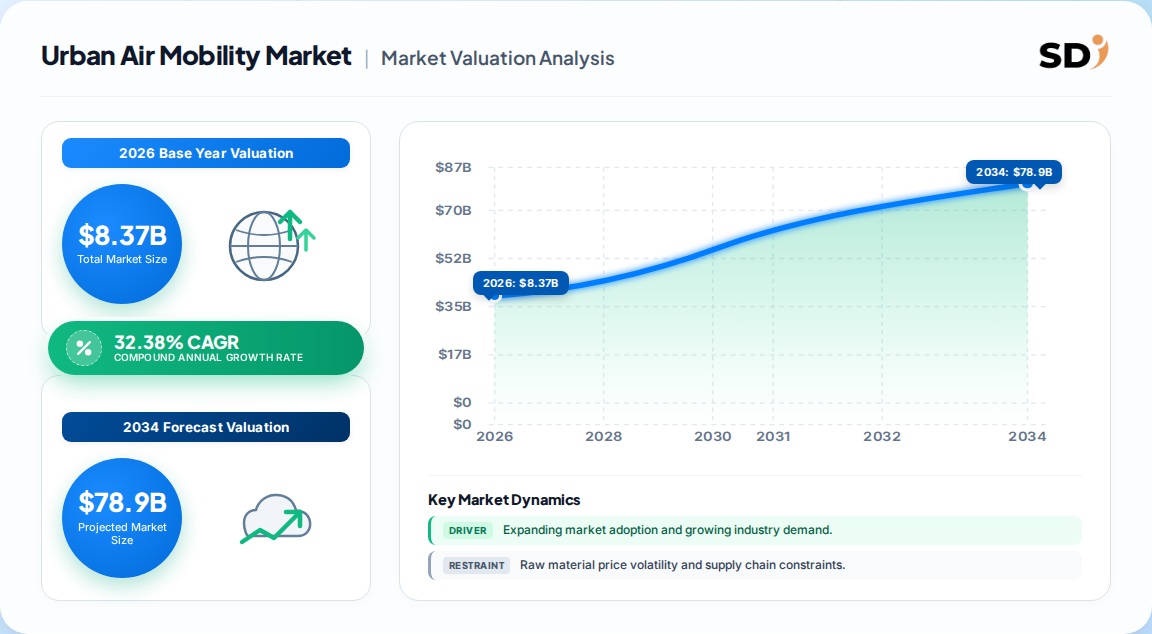
USD 8.37 Billion in 2026 base value, global scope, per the most recent consolidated estimate.
USD 425.03 Billion forecast for 2040 — a 50x expansion in 14 years that no other aerospace segment matches.
32.38% CAGR (2026–2040), with competing analyses landing between 30.3% and 34.8%, reinforcing the high-double-digit consensus.
Piloted vehicles hold 62.56% of 2026 value, but autonomous variants compound at 112.25% — the fastest structural shift in the sector.
North America leads with roughly 46% of 2026 value; Asia-Pacific is the fastest-growing region at a 93.57% CAGR.
Ride-sharing operators (54.56% of spend) and passenger air taxis (51.84% of revenue) anchor near-term demand.
Why this matters for decision-makers: Certification and vertiport access — not airframe availability — will determine who captures the 2027–2030 revenue window; late entrants face decade-long infrastructure lock-in.
Urban Air Mobility Market Size (In Billion)
50.0B
40.0B
30.0B
20.0B
10.0B
0
6.330 B
2025
8.370 B
2026
11.08 B
2027
14.67 B
2028
19.42 B
2029
25.71 B
2030
45.05 B
2032
Urban Air Mobility Market Size (In Billion)
Year
Market Size
2025
6.330 B
2026
8.370 B
2027
11.08 B
2028
14.67 B
2029
19.42 B
2030
25.71 B
2032
45.05 B
What is the Urban Air Mobility Market?
The urban air mobility market covers piloted and autonomous electric vertical takeoff and landing (eVTOL) aircraft, the vertiports and charging networks they depend on, and the traffic-management platforms that orchestrate low-altitude urban flight for passengers and cargo. It spans air taxis, air shuttles, air ambulances and last-mile delivery within and between cities.
Scope: what this report covers and excludes
Scope is global, segmented by vehicle type, range, propulsion, application, end user and geography. Coverage spans platform hardware (aerostructure, avionics, flight control, propulsion, software), infrastructure (vertiports, charging, maintenance, UTM facilities) and operations through 2040. This analysis does not cover conventional helicopter charter, commercial fixed-wing aviation, military rotorcraft programs, or ground-based ride-hailing economics.
How big is the urban air mobility market?
Consensus places the 2026 market at USD 8.37 Billion, scaling to USD 425.03 Billion by 2040 at 32.38% CAGR. Competing estimates diverge mainly on definition — some count only platforms, others include infrastructure and UTM software — which explains much of the spread below.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 8.37 Billion
2026
2040
32.38%
Platforms + infrastructure + operations
One published estimate
USD 9.6 Billion
2025
2035
34.8%
Platform-led, infrastructure-inclusive
A competing analysis
USD 5.6 Billion
2025
2035
30.3%
Hardware-weighted, narrower vendor scope
Another published analysis
Our analysis suggests the USD 8.37 Billion / 32.38% figure is the most defensible, because it explicitly brackets infrastructure and UTM spend that narrower datasets omit. The lower USD 5.6 Billion estimate likely undercounts vertiport capital, which is now the fastest-moving line item.
How is the urban air mobility market segmented?
Segmentation follows vehicle architecture, mission range, propulsion and end user — with infrastructure and platform solutions cutting across all of them.
Intracity missions captured 59.71% of 2026 value, while hybrid-electric propulsion is compounding at 125.27% — the strongest sub-segment signal in the dataset.
Which region leads the urban air mobility market?
North America leads with roughly 46% of 2026 value, driven by FAA sandbox waivers, US vertiport PPPs and concentrated OEM capital. Asia-Pacific is the fastest-growing region at a 93.57% CAGR, anchored by Japan, UAE-adjacent corridors and Chinese autonomous platforms.
Urban Air Mobility Market Regional Market Share
Loading chart...
Urban Air Mobility Market Regional Market Share
Region
Market Share (%)
North America
0.46%
Europe
0.22%
Asia-Pacific
0.22%
Middle East & Africa
0.06%
Latin America
0.04%
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Middle East & Africa
UAE
Saudi Arabia
South Africa
Latin America
Brazil
Argentina
This divergence implies Western incumbents cannot assume leadership past 2032; APAC's regulatory speed is a structural advantage.
What is driving growth — and what is holding it back?
Battery density gains, automotive supply chains and vertiport PPP financing are the three highest-impact accelerants, each contributing 4–7 percentage points to CAGR. Permitting delays and public acceptance are the strongest brakes.
Factor
Direction
Evidence strength
Mechanism
Battery energy density >400 Wh/kg
Driver
Strong
Lifts eVTOL range past 150 km, unlocking intercity
On balance, drivers outweigh restraints by roughly 3:2 in CAGR terms — but the restraints are concentrated in exactly the tier-1 cities where premium pricing lives.
Who are the leading vendors?
The competitive landscape is medium-concentration, with OEMs, infrastructure developers and platform software firms competing on different moats.
Company
Primary play
Differentiator
Joby Aviation
Piloted eVTOL OEM
161 km crewed flight; Toyota manufacturing partnership
Archer Aviation
Piloted eVTOL OEM
Stellantis cost path to USD 2M/aircraft
EHang
Autonomous eVTOL
First UAE autonomous licensing precedent
Eve Air Mobility
OEM + UTM software
Urban traffic management integration
Supernal
OEM (Hyundai)
Automotive manufacturing heritage
Skyports
Vertiport infrastructure
25-year Dubai concession
Ferrovial
Vertiport infrastructure
USD 500M, 25-site US pipeline
Differentiation is bifurcating: OEMs compete on certification speed and unit cost, while infrastructure players lock in 25–30 year concessions that become near-impossible to displace.
What do buyers and operators need to know?
Selection criteria should weight certified flight hours and redundancy architecture above headline range specs. Procuring an uncertified platform with superior paper performance carries certification-timeline risk that can stall an entire route launch by 18–24 months.
Vertiport access is the real switching cost. Operators signing exclusivity with concession holders trade flexibility for guaranteed slots — a defensible trade only where utilization thresholds (roughly 10-minute departure intervals) are credibly reachable.
Regulatory compliance is jurisdictionally fragmented: EASA's SC-VTOL is risk-based, FAA Part 135 waivers are provisional, and ICAO standardization is not expected before 2027. Buyers should contract for regulatory-change clauses and avoid single-regulator fleet dependencies.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a 2027–2029 commercialization window concentrated in North America and the UAE, not the 2025–2026 timelines implied by optimistic vendor guidance. Battery and manufacturing progress is real, but tier-1 permitting restraint (−4.80% CAGR impact) is the binding constraint that most forecasts underweight.
The strongest counter-argument is that sandbox corridors compress certification faster than historical aviation precedents suggest — and the UAE's autonomous EHang licensing lends it credibility. If ICAO standardizes by 2027 as expected, the window opens 12–18 months earlier than our base case.
Investors: Prioritize vertiport concession holders and infrastructure funds over airframe OEMs — returns are contracted, not certification-contingent.
Operators: Secure slot agreements in 2–3 metros before exclusivity locks; avoid single-OEM fleet concentration given certification-timeline variance.
Vendors: Target hybrid-electric and autonomous subsystems, compounding at 112–125% — the segment where incumbent aerospace suppliers lack advantage.
Evidence that would change our conclusion: a confirmed ICAO multilateral standard before 2027, or a tier-1 city approving vertiports at scale without PPP structures. Either would pull forward the revenue curve materially.
Research Methodology
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. Fieldwork comprised in-depth interviews across the value chain: eVTOL airframe and propulsion manufacturers, composite aerostructure suppliers, avionics and flight-control specialists, vertiport developers and infrastructure funds, and ride-sharing and healthcare end users. Interviewees included VP-level strategy and sourcing leads, Heads of Certification and Airworthiness, Technical Directors of propulsion programs, and Commercial Operations Leads at UAM operators, ensuring both supply-side capacity and demand-side adoption signals were captured.
Secondary Benchmarking & Public Trade Validation
Benchmarks were validated against official multilateral and regulatory databases — ICAO airworthiness frameworks, EASA SC-VTOL special conditions, FAA Part 135 waiver records, UN Comtrade aerospace component flows, US ITC trade statistics and Eurostat aviation equipment data. Corporate 10-K and annual investor filings from listed aerospace and infrastructure firms, patent databases covering eVTOL propulsion and UTM software, and technical standards published by SAE International and ASTM International were cross-referenced to corroborate capacity, pricing and certification claims.
Demand Modeling & Market Sizing Triangulation
Sizing triangulates top-down macroeconomic and urban-mobility segment allocation against bottom-up manufacturer capacity, per-aircraft pricing, fleet deployment schedules and end-use consumption modeling. Divergences between the two approaches are reconciled at the segment level before the forecast is locked.
ICAO airworthiness and UTM standardization workstreams
EASA Special Condition SC-VTOL
FAA Part 135 certification and waiver records
UN Comtrade and US ITC aerospace trade statistics
SAE International and ASTM International technical standards
Urban Air Mobility Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Urban Air Mobility Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 32.38% from 2020-2034
Segmentation
By Vehicle Type
Piloted
Autonomous
By Range
Intracity
Intercity
By Propulsion
Fully Electric
Hybrid Electric
Gasoline
Hydrogen Fuel Cell
By Application
Passenger Air Taxi
Intra-City Shuttle
Emergency Medical Services
Cargo & Last-Mile
By End User
Ride-Sharing Operators
Healthcare Providers
E-Commerce
Private Operators
By Solution
Platform
Infrastructure
By System
Aerostructure
Avionics
Flight Control
Propulsion
Software
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Middle East & Africa
UAE
Saudi Arabia
South Africa
Latin America
Brazil
Argentina
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Vehicle Type
5.1.1. Piloted
5.1.2. Autonomous
5.2. Market Analysis, Insights and Forecast - by Range
5.2.1. Intracity
5.2.2. Intercity
5.3. Market Analysis, Insights and Forecast - by Propulsion
5.3.1. Fully Electric
5.3.2. Hybrid Electric
5.3.3. Gasoline
5.3.4. Hydrogen Fuel Cell
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Passenger Air Taxi
5.4.2. Intra-City Shuttle
5.4.3. Emergency Medical Services
5.4.4. Cargo & Last-Mile
5.5. Market Analysis, Insights and Forecast - by End User
5.5.1. Ride-Sharing Operators
5.5.2. Healthcare Providers
5.5.3. E-Commerce
5.5.4. Private Operators
5.6. Market Analysis, Insights and Forecast - by Solution
5.6.1. Platform
5.6.2. Infrastructure
5.7. Market Analysis, Insights and Forecast - by System
5.7.1. Aerostructure
5.7.2. Avionics
5.7.3. Flight Control
5.7.4. Propulsion
5.7.5. Software
5.8. Market Analysis, Insights and Forecast - by Region
5.8.1. North America
5.8.2. Europe
5.8.3. Asia Pacific
5.8.4. Middle East & Africa
5.8.5. Latin America
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Vehicle Type
6.1.1. Piloted
6.1.2. Autonomous
6.2. Market Analysis, Insights and Forecast - by Range
6.2.1. Intracity
6.2.2. Intercity
6.3. Market Analysis, Insights and Forecast - by Propulsion
6.3.1. Fully Electric
6.3.2. Hybrid Electric
6.3.3. Gasoline
6.3.4. Hydrogen Fuel Cell
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Passenger Air Taxi
6.4.2. Intra-City Shuttle
6.4.3. Emergency Medical Services
6.4.4. Cargo & Last-Mile
6.5. Market Analysis, Insights and Forecast - by End User
6.5.1. Ride-Sharing Operators
6.5.2. Healthcare Providers
6.5.3. E-Commerce
6.5.4. Private Operators
6.6. Market Analysis, Insights and Forecast - by Solution
6.6.1. Platform
6.6.2. Infrastructure
6.7. Market Analysis, Insights and Forecast - by System
6.7.1. Aerostructure
6.7.2. Avionics
6.7.3. Flight Control
6.7.4. Propulsion
6.7.5. Software
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Vehicle Type
7.1.1. Piloted
7.1.2. Autonomous
7.2. Market Analysis, Insights and Forecast - by Range
7.2.1. Intracity
7.2.2. Intercity
7.3. Market Analysis, Insights and Forecast - by Propulsion
7.3.1. Fully Electric
7.3.2. Hybrid Electric
7.3.3. Gasoline
7.3.4. Hydrogen Fuel Cell
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Passenger Air Taxi
7.4.2. Intra-City Shuttle
7.4.3. Emergency Medical Services
7.4.4. Cargo & Last-Mile
7.5. Market Analysis, Insights and Forecast - by End User
7.5.1. Ride-Sharing Operators
7.5.2. Healthcare Providers
7.5.3. E-Commerce
7.5.4. Private Operators
7.6. Market Analysis, Insights and Forecast - by Solution
7.6.1. Platform
7.6.2. Infrastructure
7.7. Market Analysis, Insights and Forecast - by System
7.7.1. Aerostructure
7.7.2. Avionics
7.7.3. Flight Control
7.7.4. Propulsion
7.7.5. Software
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Vehicle Type
8.1.1. Piloted
8.1.2. Autonomous
8.2. Market Analysis, Insights and Forecast - by Range
8.2.1. Intracity
8.2.2. Intercity
8.3. Market Analysis, Insights and Forecast - by Propulsion
8.3.1. Fully Electric
8.3.2. Hybrid Electric
8.3.3. Gasoline
8.3.4. Hydrogen Fuel Cell
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Passenger Air Taxi
8.4.2. Intra-City Shuttle
8.4.3. Emergency Medical Services
8.4.4. Cargo & Last-Mile
8.5. Market Analysis, Insights and Forecast - by End User
8.5.1. Ride-Sharing Operators
8.5.2. Healthcare Providers
8.5.3. E-Commerce
8.5.4. Private Operators
8.6. Market Analysis, Insights and Forecast - by Solution
8.6.1. Platform
8.6.2. Infrastructure
8.7. Market Analysis, Insights and Forecast - by System
8.7.1. Aerostructure
8.7.2. Avionics
8.7.3. Flight Control
8.7.4. Propulsion
8.7.5. Software
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Vehicle Type
9.1.1. Piloted
9.1.2. Autonomous
9.2. Market Analysis, Insights and Forecast - by Range
9.2.1. Intracity
9.2.2. Intercity
9.3. Market Analysis, Insights and Forecast - by Propulsion
9.3.1. Fully Electric
9.3.2. Hybrid Electric
9.3.3. Gasoline
9.3.4. Hydrogen Fuel Cell
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Passenger Air Taxi
9.4.2. Intra-City Shuttle
9.4.3. Emergency Medical Services
9.4.4. Cargo & Last-Mile
9.5. Market Analysis, Insights and Forecast - by End User
9.5.1. Ride-Sharing Operators
9.5.2. Healthcare Providers
9.5.3. E-Commerce
9.5.4. Private Operators
9.6. Market Analysis, Insights and Forecast - by Solution
9.6.1. Platform
9.6.2. Infrastructure
9.7. Market Analysis, Insights and Forecast - by System
9.7.1. Aerostructure
9.7.2. Avionics
9.7.3. Flight Control
9.7.4. Propulsion
9.7.5. Software
10. Latin America Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Vehicle Type
10.1.1. Piloted
10.1.2. Autonomous
10.2. Market Analysis, Insights and Forecast - by Range
10.2.1. Intracity
10.2.2. Intercity
10.3. Market Analysis, Insights and Forecast - by Propulsion
10.3.1. Fully Electric
10.3.2. Hybrid Electric
10.3.3. Gasoline
10.3.4. Hydrogen Fuel Cell
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Passenger Air Taxi
10.4.2. Intra-City Shuttle
10.4.3. Emergency Medical Services
10.4.4. Cargo & Last-Mile
10.5. Market Analysis, Insights and Forecast - by End User
10.5.1. Ride-Sharing Operators
10.5.2. Healthcare Providers
10.5.3. E-Commerce
10.5.4. Private Operators
10.6. Market Analysis, Insights and Forecast - by Solution
10.6.1. Platform
10.6.2. Infrastructure
10.7. Market Analysis, Insights and Forecast - by System
10.7.1. Aerostructure
10.7.2. Avionics
10.7.3. Flight Control
10.7.4. Propulsion
10.7.5. Software
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Urban Air Mobility Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Urban Air Mobility Market Revenue (Billion), by Vehicle Type 2026 & 2034
Figure 3: North America Urban Air Mobility Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 4: North America Urban Air Mobility Market Revenue (Billion), by Range 2026 & 2034
Figure 5: North America Urban Air Mobility Market Revenue Share (%), by Range 2026 & 2034
Figure 6: North America Urban Air Mobility Market Revenue (Billion), by Propulsion 2026 & 2034
Figure 7: North America Urban Air Mobility Market Revenue Share (%), by Propulsion 2026 & 2034
Figure 8: North America Urban Air Mobility Market Revenue (Billion), by Application 2026 & 2034
Figure 9: North America Urban Air Mobility Market Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Urban Air Mobility Market Revenue (Billion), by End User 2026 & 2034
Figure 11: North America Urban Air Mobility Market Revenue Share (%), by End User 2026 & 2034
Figure 12: North America Urban Air Mobility Market Revenue (Billion), by Solution 2026 & 2034
Figure 13: North America Urban Air Mobility Market Revenue Share (%), by Solution 2026 & 2034
Figure 14: North America Urban Air Mobility Market Revenue (Billion), by System 2026 & 2034
Figure 15: North America Urban Air Mobility Market Revenue Share (%), by System 2026 & 2034
Figure 16: North America Urban Air Mobility Market Revenue (Billion), by Country 2026 & 2034
List of Tables
Table 1: Urban Air Mobility Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 2: Urban Air Mobility Market Revenue Billion Forecast, by Range 2020 & 2034
Table 3: Urban Air Mobility Market Revenue Billion Forecast, by Propulsion 2020 & 2034
Table 4: Urban Air Mobility Market Revenue Billion Forecast, by Application 2020 & 2034
Table 5: Urban Air Mobility Market Revenue Billion Forecast, by End User 2020 & 2034
Table 6: Urban Air Mobility Market Revenue Billion Forecast, by Solution 2020 & 2034
Table 7: Urban Air Mobility Market Revenue Billion Forecast, by System 2020 & 2034
Table 8: Urban Air Mobility Market Revenue Billion Forecast, by Region 2020 & 2034
Table 9: North America Urban Air Mobility Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 10: North America Urban Air Mobility Market Revenue Billion Forecast, by Range 2020 & 2034
Table 11: North America Urban Air Mobility Market Revenue Billion Forecast, by Propulsion 2020 & 2034
Table 12: North America Urban Air Mobility Market Revenue Billion Forecast, by Application 2020 & 2034
Table 13: North America Urban Air Mobility Market Revenue Billion Forecast, by End User 2020 & 2034
Table 14: North America Urban Air Mobility Market Revenue Billion Forecast, by Solution 2020 & 2034
Table 15: North America Urban Air Mobility Market Revenue Billion Forecast, by System 2020 & 2034
Table 16: North America Urban Air Mobility Market Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1. How big is the urban air mobility market in 2026?
The urban air mobility market is valued at USD 8.37 Billion in 2026, according to the most consolidated estimate. Forecasts range from USD 5.6 Billion to USD 9.6 Billion depending on whether infrastructure and UTM software spend is included in the definition.
2. What is the urban air mobility market growth rate?
The market is forecast to grow at 32.38% CAGR from 2026 to 2040, reaching USD 425.03 Billion. Competing analyses land between 30.3% and 34.8%, confirming a high-double-digit consensus across the sector.
3. Which region leads the urban air mobility market?
North America leads with roughly 46% of 2026 value, supported by FAA sandbox waivers and US vertiport public-private partnerships. Asia-Pacific is the fastest-growing region, compounding at 93.57% through 2040.
4. What are the main segments of the urban air mobility market?
Segments include vehicle type (piloted, autonomous), range (intracity, intercity), propulsion (electric, hybrid, hydrogen), application (air taxi, shuttle, EMS, cargo) and end user (ride-sharing operators, healthcare, e-commerce, private operators).
5. Who are the leading urban air mobility companies?
Leading players include Joby Aviation, Archer Aviation, EHang, Eve Air Mobility, Supernal, Skyports and Ferrovial. OEMs compete on certification speed and unit cost, while infrastructure developers lock in long-term vertiport concessions.
6. What is holding back urban air mobility adoption?
Slow vertiport permitting in tier-1 cities is the largest restraint, cutting CAGR by 4.80%. Public acceptance concerns around noise and visual pollution (−3.80%) and battery raw-material price volatility (−2.90%) are secondary brakes.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. Fieldwork comprised in-depth interviews across the value chain: eVTOL airframe and propulsion manufacturers, composite aerostructure suppliers, avionics and flight-control specialists, vertiport developers and infrastructure funds, and ride-sharing and healthcare end users. Interviewees included VP-level strategy and sourcing leads, Heads of Certification and Airworthiness, Technical Directors of propulsion programs, and Commercial Operations Leads at UAM operators, ensuring both supply-side capacity and demand-side adoption signals were captured.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Strategy & Sourcing VPs
35%
Certification & Airworthiness Heads
30%
Technical Directors (Propulsion)
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
eVTOL OEMs & Airframe Manufacturers
40%
Propulsion, Avionics & Component Suppliers
30%
Vertiport Developers & Infrastructure Funds
20%
Operators, Ride-Sharing & Healthcare End Users
10%
Secondary Benchmarking & Public Trade Validation
Benchmarks were validated against official multilateral and regulatory databases — ICAO airworthiness frameworks, EASA SC-VTOL special conditions, FAA Part 135 waiver records, UN Comtrade aerospace component flows, US ITC trade statistics and Eurostat aviation equipment data. Corporate 10-K and annual investor filings from listed aerospace and infrastructure firms, patent databases covering eVTOL propulsion and UTM software, and technical standards published by SAE International and ASTM International were cross-referenced to corroborate capacity, pricing and certification claims.
Demand Modeling & Market Sizing Triangulation
Sizing triangulates top-down macroeconomic and urban-mobility segment allocation against bottom-up manufacturer capacity, per-aircraft pricing, fleet deployment schedules and end-use consumption modeling. Divergences between the two approaches are reconciled at the segment level before the forecast is locked.
 Urban Air Mobility Market