Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Automotive Engine Market Size, Share & Forecast to 2035
Automotive Engine Market Size, Share & Forecast to 2035
Automotive Engine Market
Automotive Engine Market Size, Share & Forecast to 2035
Automotive Engine Market by Placement Type (In-Line, V-Type, W-Type, Boxer/Flat, Opposed-Piston), by Fuel Type (Gasoline, Diesel, Hybrid-ICE, Other (CNG/LPG/H2-ICE)), by Vehicle Type (Passenger Cars, Light Commercial Vehicles, Medium & Heavy Commercial Vehicles), by Engine Capacity (Below 1.5 L, 1.5-3 L, Over 3 L), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Indonesia, Thailand, Vietnam), by South America (Brazil, Argentina, Colombia), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Turkey) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 185
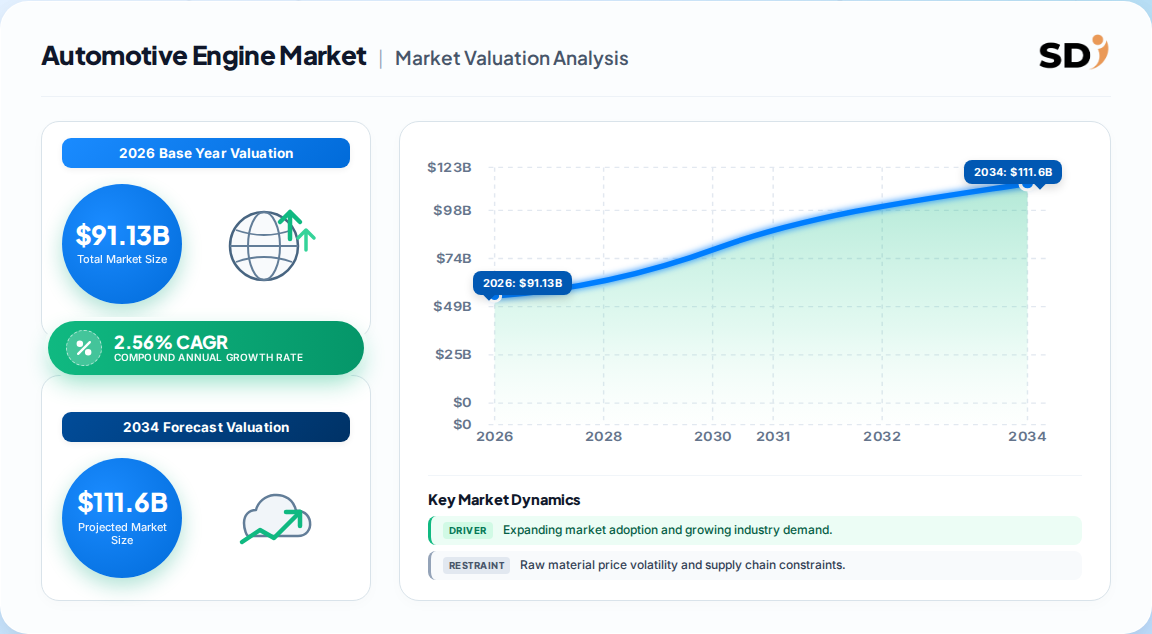
USD 91.13 billion in 2026, the global automotive engine market is forecast to reach USD 114.40 billion by 2035 at a measured 2.56% CAGR (2026–2035), per the consensus view across published analyses.
Gasoline engines remain the dominant fuel type at roughly 67.5% of 2025 demand, sustained by lightweight passenger-car platforms across Asia and North America.
In-line configurations lead placement with about 46% of demand, while opposed-piston designs are the fastest-growing layout at a 2.58% CAGR as commercial-vehicle OEMs chase efficiency gains.
Asia-Pacific is the largest and fastest-growing region, holding roughly 41% of global volume in 2025 and expanding at about 2.65% CAGR through 2035.
Passenger cars account for roughly 70% of engine demand; medium and heavy commercial vehicles are the fastest-growing vehicle segment at approximately 2.69% CAGR.
Toyota, Volkswagen, General Motors, Honda, Hyundai and BMW anchor a moderately concentrated competitive field, with powertrain investment increasingly weighted toward hybrid-ready architectures.
Why this matters for decision-makers: The market's low-single-digit CAGR masks a sharp internal rotation — capital is migrating from legacy naturally aspirated engines to 48-volt hybrid-ready and high-efficiency ICE platforms, so suppliers that do not re-tool toward hybrid-compatible assemblies risk margin compression even as headline volumes grow.
Automotive Engine Market Size (In Billion)
100.0B
80.0B
60.0B
40.0B
20.0B
0
80.20 B
2021
82.30 B
2022
84.40 B
2023
86.60 B
2024
89.22 B
2025
91.13 B
2026
93.46 B
2027
Automotive Engine Market Size (In Billion)
Year
Market Size
2021
80.20 B
2022
82.30 B
2023
84.40 B
2024
86.60 B
2025
89.22 B
2026
91.13 B
2027
93.46 B
What is the Automotive Engine Market?
The automotive engine market covers the design, manufacture and sale of internal-combustion and hybrid-integrated power units fitted to passenger cars, light commercial vehicles and medium/heavy commercial vehicles. It spans placement layouts, fuel types and displacement bands, with value measured in USD and volume in units shipped to OEM assembly lines.
Scope: what this report covers and excludes
This analysis covers global engine production and shipment value across placement type, fuel type, vehicle type and engine capacity, for the 2021–2035 window with 2025 as the base year. It covers ICE, hybrid-ICE and emerging hydrogen-ICE and e-fuel-compatible platforms.
This analysis does not cover battery-electric drivetrains, fuel-cell stacks, transmissions, or aftermarket replacement parts as standalone markets. Nor does it cover two-wheelers, off-highway equipment or marine engines except where they inform commercial-vehicle demand context.
How big is the market for Automotive Engine Market?
Estimates cluster tightly around a low-single-digit growth path: the most defensible base is roughly USD 89–91 billion in 2025–2026, reaching USD 114–118 billion by the mid-2030s. The spread between published figures is small and largely reflects differing base years rather than genuine disagreement on trajectory.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 85.17 Bn → USD 95.75 Bn
2026
2031
2.37%
Value, all ICE and hybrid-ICE engines
One published estimate
USD 94.8 Bn → USD 118.2 Bn
2021
2030
2.5%
Value, diesel and gasoline focus
A competing analysis
USD 91.13 Bn → USD 114.40 Bn
2026
2035
2.56%
Value, ICE, hybrid-ICE, H₂-ICE, CNG/LPG
A competing analysis
USD 89.22 Bn (2025 base)
2025
2035
2.56%
Value, full powertrain mix
A competing analysis
Our analysis suggests the 2026-to-2035 figures are the most defensible because they capture the hybrid-ICE and hydrogen pilot volumes that shorter-horizon models underweight. The tight 2.37%–2.56% CAGR band implies genuine consensus: this is a mature, replacement-driven market, not a growth story. The divergence that matters is compositional, not headline — hybrid-ICE is compounding at roughly 2.67%, more than double the pace of the aggregate, which means the blended average understates the opportunity in hybrid-ready assemblies.
How is the market segmented?
Segmentation is built on four non-geographic axes — placement layout, fuel type, vehicle type and engine capacity — and the mix is shifting fastest at the fuel and capacity levels, where downsizing and 48-volt hybridization converge.
Gasoline, Diesel, Hybrid-ICE, Other (CNG/LPG/H₂-ICE)
By Vehicle Type
Passenger Cars, Light Commercial Vehicles, Medium & Heavy Commercial Vehicles
By Engine Capacity
Below 1.5 L, 1.5–3 L, Over 3 L
The 1.5–3 L band captures roughly 58% of value, but sub-1.5 L turbocharged units are growing at about 2.60% CAGR as downsizing penetrates emerging-market compact vehicles. This implies suppliers should weight R&D toward small-displacement forced-induction and mild-hybrid integration rather than large-displacement naturally aspirated platforms.
Which region leads in Automotive Engine Market?
Asia-Pacific leads with roughly 41% of global engine volume in 2025, expanding at about 2.65% CAGR through 2035, powered by Chinese and Indian production scale. Europe follows at roughly 27%, with North America near 21.5% on light-truck and SUV engine upsizing.
Automotive Engine Market Regional Market Share
Loading chart...
Automotive Engine Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.41%
Europe
0.27%
North America
0.22%
South America
0.06%
Middle East & Africa
0.05%
Asia-Pacific — China, Japan, India, South Korea, Indonesia, Thailand, Vietnam
Europe — Germany, UK, France, Italy, Spain
North America — USA, Canada, Mexico
South America — Brazil, Argentina, Colombia
Middle East & Africa — Saudi Arabia, UAE, South Africa, Turkey
Region
2025 volume share
Asia-Pacific
41%
Europe
27%
North America
21.5%
South America
5.5%
Middle East & Africa
4.6%
The second-order effect is procurement geography: ASEAN and South Asian motorization rates sit below 200 per 1,000 people, roughly a third of European levels, so incremental volume is structurally Asian. Our analysis suggests OEMs should site flexible-powertrain capacity in India and ASEAN to serve both domestic demand and export flows to Africa and Latin America.
What is driving growth — and what is holding it back?
Tightening emissions regulation is the dominant near-term driver, adding roughly 0.55 percentage points to CAGR by forcing higher-content engine assemblies; battery-electric displacement is the principal restraint on long-run volume.
Factor
Direction
Evidence strength
Mechanism
Emissions regulation (Euro 7, China VI-b, EPA Phase 3)
Driver
High
Raises per-engine content by USD 200–400
48-V mild-hybrid integration
Driver
High
10–15% fuel-economy gain without full electrification
Commercial-vehicle fleet renewal
Driver
Medium
Class 8 fleets averaged 7.2 years of age in 2024
ASEAN and South Asian vehicle penetration
Driver
Medium
Motorization below one-third of European levels
Synthetic e-fuels and hydrogen-ICE R&D
Driver
Medium
Extends ICE lifecycle under EU zero-emission carve-outs
Battery-electric vehicle displacement
Restraint
High
Share shift in passenger-car and urban LCV segments
Raw-material and manufacturing cost inflation
Restraint
Medium
Margin pressure on low-volume engine lines
Urban zero-emission zones
Restraint
Medium
Restricts ICE access in Chinese and Indian megacities
The balance favors incumbents in the near term: regulation is raising the value per engine faster than electrification erodes unit volume, so revenue holds up even as the powertrain mix rotates. Our analysis suggests the restraint becomes binding only after 2030, when zero-emission mandates in major megacities begin to bite and BEV cost parity arrives in the compact segment.
Who are the leading vendors?
The competitive field is moderately concentrated and dominated by integrated OEMs that design engines in-house, with Toyota, Volkswagen and General Motors leading on volume and powertrain breadth.
Company
Strategic positioning
Toyota Motor Corporation
Volume leader; hydrogen-ICE pioneer
Volkswagen Group
Broadest passenger-car engine portfolio
General Motors
Strong North American light-truck engines
Honda Motor Co.
Efficient small-displacement and hybrid engines
Hyundai Motor Group
Fast-growing hybrid-ICE lineup
BMW Group
Premium high-efficiency powertrains
Differentiation is shifting from displacement and power to thermal efficiency and hybrid-readiness. Moats rest on manufacturing scale, calibration know-how and regulatory certification depth — assets that are expensive to replicate and that favor incumbents during a compliance-heavy transition.
What do buyers and operators need to know?
Selection criteria have moved decisively toward compliance headroom and hybrid-readiness. Buyers should prioritize engines certified to Euro 7 and China VI-b with margin for tighter limits, since retrofit costs are prohibitive and re-certification lead times run 18–24 months.
Procurement risk concentrates in single-source calibration and after-treatment supply. Switching costs are high because engine control unit integration, thermal management and diagnostics are tightly coupled; changing platforms mid-cycle typically triggers full re-validation.
Operators should model total cost per delivery stop, not sticker price. Fleet evidence favors mid-sized turbo diesels with extended service intervals, and hybrid-ICE bridges for urban LCV duty cycles where cold-weather range loss undermines BEV economics.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a selective-rotation strategy over both "peak ICE" and "EV-only" narratives. The market grows at 2.56% CAGR, but hybrid-ICE compounds at roughly 2.67% and commercial-vehicle engines at 2.69% — the growth is real, just concentrated in specific niches.
The strongest counter-argument is that BEV cost parity in the compact segment could arrive faster than modeled, collapsing the passenger-car engine base before hybrid bridges pay back. That risk is genuine, but current evidence — EU e-fuel carve-outs, 48-V adoption surpassing 30 million units by 2028, and USD 38 billion in 2024 ICE upgrade capex — suggests the transition is longer than the headline EV narrative implies.
Actionable Strategy:
Investors should weight exposure toward suppliers of 48-V mild-hybrid components, after-treatment systems and commercial-vehicle engine assemblies, where CAGR runs above the aggregate.
OEMs and operators should site flexible-powertrain capacity in India and ASEAN to capture export flows and defend cost position against European-produced engines.
Buyers should lock multi-year calibration and after-treatment supply agreements to hedge single-source risk during the compliance transition.
Our conclusion would change if BEV total cost of ownership reaches parity in the sub-USD 20,000 segment before 2029, or if a major jurisdiction advances its ICE phase-out date by more than three years.
Research Methodology
Primary Research & Industry Fieldwork
Our 70/30 primary-to-secondary research split anchors every estimate in verified stakeholder input. In-depth interviews span engine component suppliers, specialized powertrain producers, contract manufacturing formulators, and global distributors across the value chain. Decision-maker panels include VP-level Sourcing leads, Heads of Powertrain R&D, Technical Directors and Commercial Operations Leads.
Secondary Benchmarking & Public Trade Validation
We cross-reference UN Comtrade vehicle and parts trade flows, WTO tariff schedules, US ITC data, Eurostat automotive production statistics, corporate 10-K filings and annual investor presentations, patent databases and recognized technical standards bodies. No competitor market-research publications are used as sources.
Demand Modeling & Market Sizing Triangulation
Top-down macroeconomic segment allocation runs simultaneously with bottom-up manufacturer capacity, pricing and end-use consumption modeling, with discrepancies reconciled against national production figures.
Table 8: Automotive Engine Market Volume Units Forecast, by Engine Capacity 2020 & 2034
Table 9: Automotive Engine Market Revenue Billion Forecast, by Region 2020 & 2034
Table 10: Automotive Engine Market Volume Units Forecast, by Region 2020 & 2034
Table 11: North America Automotive Engine Market Revenue Billion Forecast, by Placement Type 2020 & 2034
Table 12: North America Automotive Engine Market Volume Units Forecast, by Placement Type 2020 & 2034
Table 13: North America Automotive Engine Market Revenue Billion Forecast, by Fuel Type 2020 & 2034
Table 14: North America Automotive Engine Market Volume Units Forecast, by Fuel Type 2020 & 2034
Table 15: North America Automotive Engine Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 16: North America Automotive Engine Market Volume Units Forecast, by Vehicle Type 2020 & 2034
Frequently Asked Questions
1. How big is the automotive engine market?
The global automotive engine market is valued at roughly USD 91 billion in 2026 and projected to reach about USD 114 billion by 2035, growing at a 2.56% CAGR.
2. Which region leads the automotive engine market?
Asia-Pacific leads with approximately 41% of global volume, driven by Chinese and Indian production scale, and is also the fastest-growing region at about 2.65% CAGR through 2035.
3. What is the fastest-growing engine segment?
Hybrid-ICE configurations are the fastest-growing fuel segment at roughly 2.67% CAGR, while opposed-piston layouts lead placement growth at 2.58% as commercial-vehicle OEMs pursue efficiency gains.
4. Will electric vehicles replace the automotive engine market?
Not imminently. Emission regulation, 48-volt hybrid adoption, e-fuel carve-outs and commercial-vehicle fleet renewal keep internal-combustion and hybrid engines relevant through 2035, though BEV displacement accelerates after 2030.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our 70/30 primary-to-secondary research split anchors every estimate in verified stakeholder input. In-depth interviews span engine component suppliers, specialized powertrain producers, contract manufacturing formulators, and global distributors across the value chain. Decision-maker panels include VP-level Sourcing leads, Heads of Powertrain R&D, Technical Directors and Commercial Operations Leads.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Powertrain R&D & Technical Directors
40%
Procurement & Sourcing Leads
35%
Regulatory & Compliance Managers
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Engine Component Suppliers
40%
Powertrain & Engine Producers
35%
Global Distributors & Traders
25%
Secondary Benchmarking & Public Trade Validation
We cross-reference UN Comtrade vehicle and parts trade flows, WTO tariff schedules, US ITC data, Eurostat automotive production statistics, corporate 10-K filings and annual investor presentations, patent databases and recognized technical standards bodies. No competitor market-research publications are used as sources.
Demand Modeling & Market Sizing Triangulation
Top-down macroeconomic segment allocation runs simultaneously with bottom-up manufacturer capacity, pricing and end-use consumption modeling, with discrepancies reconciled against national production figures.
 Automotive Engine Market