 Boom Truck Market
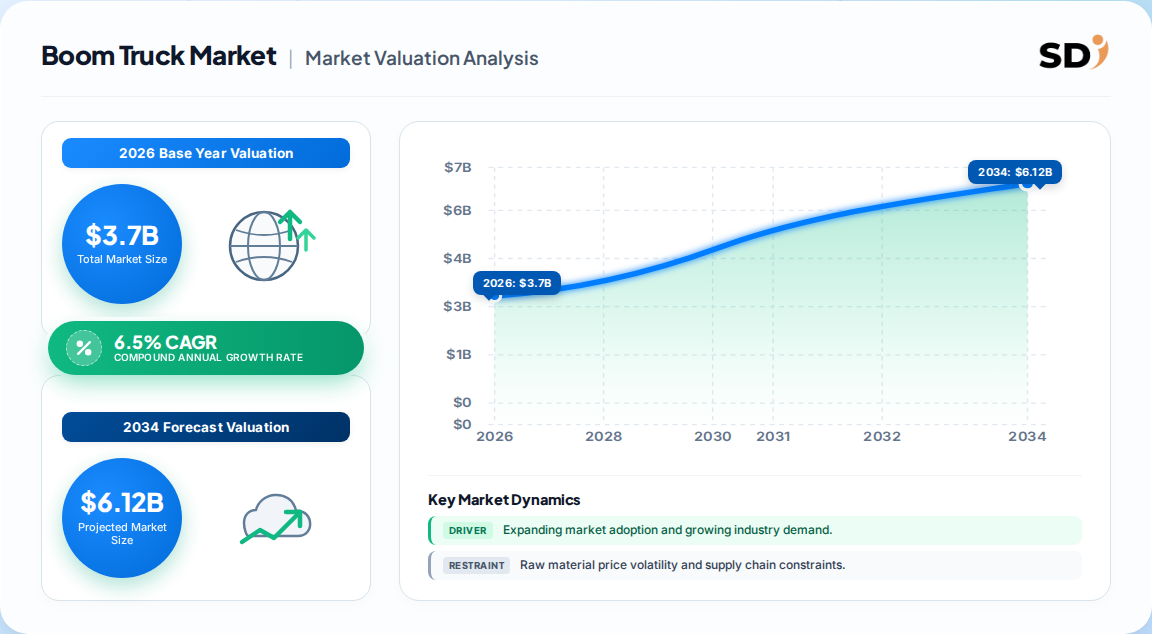
: $3.7B to $5.8B, 6.5% CAGR 2026
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 259

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Boom Truck Market
Sadashiv Parab
Research Analyst
| Year | Market Size |
|---|---|
| 2026 | 3.700 B |
| 2027 | 3.940 B |
| 2028 | 4.200 B |
| 2029 | 4.470 B |
| 2030 | 4.760 B |
| 2031 | 5.070 B |
| 2032 | 5.400 B |

A boom truck is a hydraulic or telescoping crane mounted on a commercial truck chassis, combining over-the-road mobility with lifting capability for mid-capacity tasks. It serves construction, utility, telecom, and infrastructure work where setup speed matters more than maximum reach.
This analysis covers the global boom truck market across mount configuration (behind-the-cab, rear, swing seat), lifting capacity (below 10 t through above 50 t), boom length bands, and end-use application. Regionally it spans North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. This analysis does not cover crawler cranes, tower cranes, aerial work platforms, knuckle-boom log loaders, or truck-mounted concrete pumps, which are separate lifting and material-handling categories with distinct chassis and certification regimes.
The most defensible global estimate places the boom truck market at 3.7 billion USD in 2026, growing to 5.8 billion USD by 2033 at 6.5% CAGR. Competing published figures diverge mainly on base year and capacity-scope definition rather than on underlying demand.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 3.6B → 5.8B USD | 2025 | 2033 | 6.5% | Global, all mount and capacity bands | One published estimate (GVR-style) |
| 3.4B → 6.0B USD | 2024 | 2034 | 5.8% | Global, truck-integrated cranes only | A competing analysis |
| 3.23B → 5.81B USD | 2024 | 2035 | 5.48% | Global, capacity-segmented only | A third published estimate |
| 218.1M → 358.8M USD | 2022 | 2032 | 5.1% | North America only, truck cranes | A regional published estimate |
Our analysis suggests the 6.5% figure is the most defensible global CAGR because it is the only estimate spanning the full 2026–2033 window while anchoring on a 2025 base year, which captures the post-2024 equipment-order backlog. The 5.48% and 5.8% figures are not contradictory; they reflect narrower capacity definitions and longer horizons that dilute the mid-decade replacement cycle. The North America-only estimate is consistent with a roughly 35–39% regional share of the global total, validating the geography split.
Segmentation follows four independent axes — mount, lifting capacity, boom length, and application — each with a clearly dominant band that shapes procurement and pricing.
| Parent segment | Leading child | Share (year) | Implication |
|---|---|---|---|
| Mount | Behind the cab | 58.4% (2025) | Best weight distribution; premium pricing |
| Lifting capacity | 10–20 metric tons | 26.3% (2025) | Sweet spot for utility and telecom fleets |
| Boom length | Less than 20 m | 37.7% (2025) | Urban maneuverability dominates volume |
| Application | Infrastructure | 38.2% (2025) | Road, bridge, and grid work anchors demand |
A second estimate places the 10–20 t band at 34.7% and the 20–30 m boom band at 48.9%, reflecting a wider definition that includes rear-mount utility bodies. The divergence is definitional, not directional: both confirm mid-capacity, mid-reach configurations as the volume core.
North America leads the global boom truck market with 35.9% revenue share in 2025, underpinned by utility fleet replacement, highway programs, and telecom densification. Asia Pacific is the fastest-growing region on 2026–2033 projections.
| Region | Market Share (%) |
|---|---|
| North America | 0.36% |
| Europe | 0.21% |
| Asia-Pacific | 0.28% |
| Latin America | 0.09% |
| Middle East & Africa | 0.06% |
| Region | Share (2025) | Growth posture |
|---|---|---|
| North America | 35.9% | Mature, replacement-driven |
| Europe | ~21% | Emissions-led modernization |
| Asia Pacific | ~28% | Fastest CAGR; grid and rail buildout |
| Latin America | ~9% | Inflection phase; rental-led |
| Middle East & Africa | ~6% | Project-tied, oil and utility |
Our analysis suggests North America's share will erode modestly toward 33–34% by 2033 as Asia Pacific compounds faster, but absolute North American revenue still grows because replacement demand is inelastic — utilities cannot defer bucket-truck replacement indefinitely without reliability penalties.
Infrastructure and utility capital spending is the primary growth engine, while high capital and maintenance costs remain the binding constraint on faster adoption.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Infrastructure and utility capex | Driver | High | Road, grid, and smart-city outlays require mobile lifting |
| Urban high-rise density | Driver | High | Confined sites favor truck-mounted over tower cranes |
| Telematics and load-moment systems | Driver | Medium-High | Cuts downtime; improves safety compliance |
| Electrification and hybrid drivetrains | Driver | Medium | Municipal and utility procurement preferences |
| High upfront capital cost | Restraint | High | 200k–600k USD per unit blocks small contractors |
| Maintenance and compliance burden | Restraint | Medium-High | Outrigger, load-chart, and emissions rules raise opex |
| Alternative lifting (AWPs, cranes) | Restraint | Medium | Substitution in low-capacity tasks |
The balance of evidence favors the drivers through 2028: public infrastructure pipelines are multi-year and largely contracted, so demand is less cyclical than general construction. The genuine restraint is not demand but financing — capital cost pushes buyers toward rental, which shifts margin from OEMs to fleet operators. Our analysis suggests this rental shift is the single most underappreciated structural force in the market through 2033.
Terex, Altec Industries, Manitex, Tadano, Link-Belt, Elliott Equipment, and XCMG form the competitive core, with North American specialty OEMs strongest in utility bodies and global crane majors strongest in high-capacity configurations.
| Vendor | HQ | Strength | Moat |
|---|---|---|---|
| Terex | USA | Broad crane and utility portfolio | Dealer network; brand |
| Altec Industries | USA | Utility and telecom bodies | Chassis integration depth |
| Manitex | USA | Boom trucks and knuckle booms | Product breadth |
| Tadano | Japan | High-capacity lift | Engineering and global service |
| Link-Belt | USA | Mid-to-high capacity cranes | Load-chart reputation |
| Elliott Equipment | USA | Custom and specialty units | Customization capability |
| XCMG | China | Volume and price | Cost leadership; APAC reach |
Differentiation rests on chassis integration and aftermarket service rather than raw lifting specs. Utility buyers weight uptime and parts availability above price, which protects incumbents in North America. Chinese OEMs compete on cost in Asia Pacific and Latin America but face certification and dealer-network friction in regulated markets.
Selection hinges on four mission-critical criteria: chassis-and-boom integration quality, load-chart accuracy under outrigger deployment, telematics compatibility with existing fleet management, and emissions compliance for the operating jurisdiction. Buyers should scrutinize outrigger deployment positions and sheave height rather than headline lifting capacity, since real job-site productivity depends on setup speed in constrained urban spaces.
Procurement risk concentrates in residual value and resale liquidity. Behind-the-cab mounts hold value better than rear mounts in North America but command higher acquisition cost, so total cost of ownership favors them only above high-utilization thresholds. Switching costs are moderate for fleet owners but high for utility contractors locked into OEM-specific body and parts ecosystems.
Regulatory compliance is non-negotiable: operator certification, load-moment indicators, and outrigger standards vary by jurisdiction, and emissions rules in Europe and parts of North America increasingly favor hybrid or electric-ready platforms. Buyers should contract for telematics data ownership up front — a gap that surfaces only at resale or fleet-audit stage.
The balance of evidence favors a constructive but bifurcated outlook: the global boom truck market compounds at a defensible mid-single-digit rate through 2033, but value migrates from unit sales toward rental fleets and service contracts. The strongest counter-argument is that electrification could compress replacement cycles faster than modeled, depressing near-term unit volumes as buyers wait for battery-electric platforms; we view this as a 2028+ risk rather than a 2026–2027 one.
Our analysis suggests three implications. First, OEMs should prioritize telematics-ready, hybrid-capable platforms for utility and municipal tenders, where procurement scoring increasingly rewards emissions and data integration. Second, rental fleet operators should lock multi-year chassis supply agreements now to hedge against chassis-cost inflation. Third, investors should weight aftermarket and service revenue over unit volume when assessing vendor quality, because service annuities are more resilient than cyclical equipment orders.
Evidence that would change this conclusion: sustained sub-4% infrastructure capex growth in North America and Europe, or accelerated battery-electric parity pricing before 2028, would push the market toward the lower 5.48% CAGR trajectory and favor rental consolidators over OEMs.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.5% from 2020-2034 |
| Segmentation |
|
The global boom truck market is estimated at 3.7 billion USD in 2026 and is projected to reach 5.8 billion USD by 2033. North America accounts for roughly 36% of global revenue, reflecting mature utility and infrastructure replacement demand.
A 6.5% CAGR is the most defensible figure for 2026–2033. Competing estimates of 5.48% and 5.8% use longer horizons and narrower capacity definitions, but all point to steady mid-single-digit expansion driven by infrastructure and utility capex.
North America leads with 35.9% revenue share in 2025, driven by U.S. utility fleet replacement and highway programs. Asia Pacific is the fastest-growing region, supported by grid, rail, and urban construction investment in China and India.
Terex, Altec Industries, Manitex, Tadano, Link-Belt, Elliott Equipment, and XCMG lead the market. North American OEMs dominate utility body integration, while global crane majors lead high-capacity configurations and Asia Pacific volume.
Behind-the-cab mounts dominate with 58.4% share, paired with 10–20 metric ton lifting capacity and sub-20-meter booms. This configuration balances weight distribution, urban maneuverability, and cost for utility and telecom fleets.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, prioritizing direct validation over desk aggregation. We conducted in-depth interviews across the boom truck value chain, including chassis and hydraulic component suppliers, specialized boom truck OEMs, body upfitters and custom fabricators, and global and regional equipment distributors. Decision-maker designations interviewed include VP-level Sourcing leads, Heads of Product Engineering, Technical Directors for safety and compliance, and Commercial Operations Leads responsible for fleet and rental channels. Interviews were structured to capture procurement thresholds, certification friction, and residual-value expectations that public filings do not disclose.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement Leads | 30% |
| Heads of Product Engineering | 30% |
| Technical & Safety Compliance Directors | 22% |
| Commercial Operations Leads | 18% |
| Company Type | Representation (%) |
|---|---|
| Chassis & Hydraulic Component Suppliers | 30% |
| Specialized Boom Truck OEMs | 35% |
| Body Upfitters & Custom Fabricators | 20% |
| Global & Regional Distributors | 15% |
We triangulate interview findings against official U.S. import and export statistics via USITC DataWeb, multilateral trade flows through ITC Trade Map and UN Comtrade, and tariff classifications under the Harmonized Tariff Schedule. Corporate 10-K and annual investor filings from listed OEMs inform revenue and capacity baselines, while patent databases and recognized industry safety standards — including load-moment indicator and outrigger deployment norms — validate technical segmentation. No competitor market-research publications are used as source inputs.
We run simultaneous Top-Down and Bottom-Up models. The Top-Down approach allocates macroeconomic construction and utility capex to lifting-equipment categories using historical substitution ratios. The Bottom-Up approach models manufacturer capacity, unit pricing, and end-use consumption by application. Divergence between the two is reconciled at the segment level before regional roll-up.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
