Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Automotive Over The Air Updates Market: 2026 Growth & Forecast
Automotive Over The Air Updates Market
Automotive Over The Air Updates Market: 2026 Growth & Forecast
Automotive Over The Air Updates Market by Technology (SOTA, FOTA), by Application (Telematics Gateway, ECU, Infotainment, Safety and Security, Remote Diagnostics), by Propulsion (ICE, Electric Vehicle), by Vehicle Type (Passenger Cars, Commercial Vehicles), by Communication Type (Cellular, Wi-Fi, Satellite), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, ASEAN), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 245
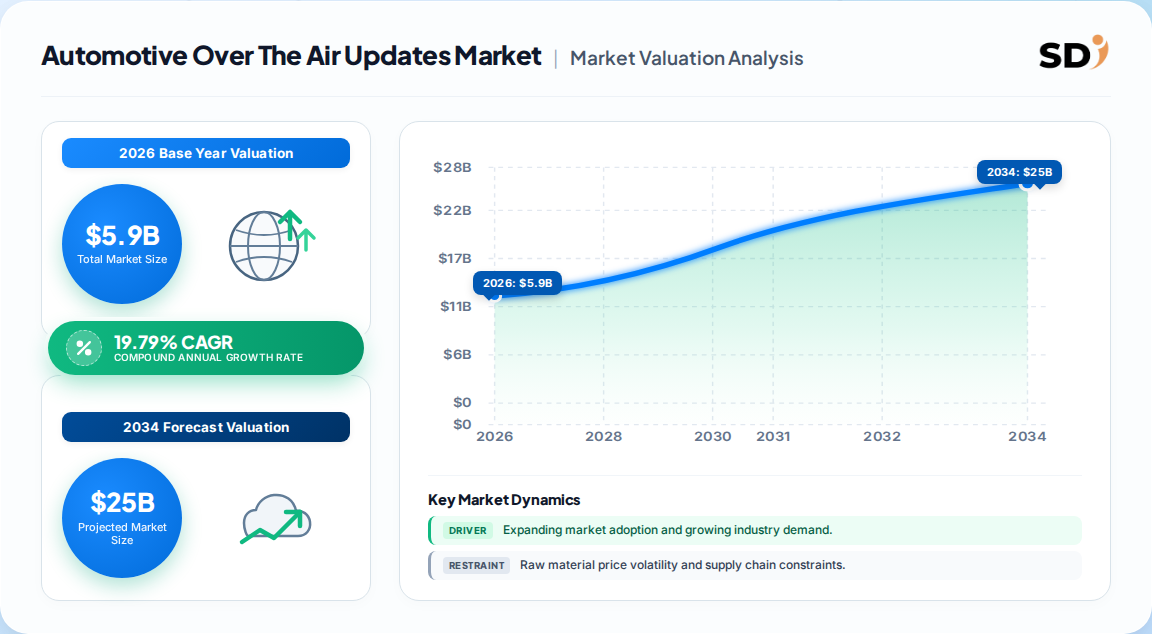
USD 5.90 billion in 2026, the global automotive over-the-air updates market expands to USD 14.55 billion by 2031, a 19.79% CAGR.
North America leads with roughly 44% revenue share in 2025; Asia-Pacific is the fastest-growing region at ~20–22% CAGR.
Software OTA (SOTA) held 68.14% of 2025 revenue; Firmware OTA (FOTA) is the faster path at 22.74% CAGR.
Telematics control units captured 36.25% application share, while safety and security updates grow fastest at 21.34% CAGR.
ICE vehicles still represent 75.03% of revenue; EVs will grow at 27.46% CAGR through 2031.
Leading players include Tesla, Volkswagen, General Motors, Hyundai, Toyota, Bosch, Continental, Harman and Qualcomm.
Why this matters for decision-makers: OTA shifts from differentiator to compliance floor; vendors that cannot deliver secure, auditable, high-frequency updates will be locked out of type approvals in 54 UNECE markets.
Automotive Over The Air Updates Market Size (In Billion)
15.0B
10.0B
5.0B
0
4.900 B
2025
5.900 B
2026
7.070 B
2027
8.460 B
2028
10.14 B
2029
12.14 B
2030
14.55 B
2031
Automotive Over The Air Updates Market Size (In Billion)
Year
Market Size
2025
4.900 B
2026
5.900 B
2027
7.070 B
2028
8.460 B
2029
10.14 B
2030
12.14 B
2031
14.55 B
What is the Automotive Over The Air Updates Market?
The automotive over-the-air updates market covers wireless delivery of software (SOTA) and firmware (FOTA) packages to vehicles, replacing dealer visits. It spans telematics gateways, ECUs, infotainment, safety patches and remote diagnostics, delivered via cellular, Wi-Fi or satellite links, and is the operational backbone of software-defined vehicles.
Scope: what this report covers and excludes
This analysis covers global revenue for OTA software and firmware delivery platforms, backend infrastructure, update-management systems and related services across passenger and commercial vehicles. This analysis does not cover in-vehicle infotainment content licensing, physical ECU hardware sales, or dealership diagnostic tools except where they directly enable remote update delivery.
How big is the market for Automotive Over The Air Updates Market?
Estimates cluster around USD 5.6–7.0 billion for 2026, but horizons and CAGRs diverge sharply; the spread reflects differing treatment of software margins, services and connectivity fees rather than genuine demand disagreement.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 5.90B
2026
2031
19.79%
OTA platforms, software and services, value terms
One published estimate
USD 5.58B
2026
2035
18.70%
OTA technology and application revenue
A competing analysis
USD 7.0B
2026
2033
24.6%
Software-led OTA incl. cloud-native platforms
Another published estimate
USD 4.90B
2025
2031
19.79%
Baseline OTA revenue, value terms
One published estimate
Our analysis suggests the ~19–20% CAGR cluster is most defensible because it aligns with connected-vehicle parc growth and regulatory deadlines. The 24.6% figure implies aggressive monetization of feature subscriptions, which remains unproven at scale outside Tesla and a handful of premium brands.
How is the market segmented?
Segmentation follows technology, application, propulsion, vehicle type and communication channel, each with distinct growth economics that shape vendor strategy and procurement priorities.
Which region leads in Automotive Over The Air Updates Market?
North America leads with about 44% revenue share in 2025, supported by Tesla, dense 4G/5G coverage and early SDV adoption. Europe follows at ~29%, and Asia-Pacific is the fastest-growing region at ~20–22% CAGR.
Automotive Over The Air Updates Market Regional Market Share
Loading chart...
Automotive Over The Air Updates Market Regional Market Share
Region
Market Share (%)
North America
0.35%
Europe
0.29%
Asia-Pacific
0.28%
South America
0.04%
Middle East & Africa
0.04%
North America — USA, Canada, Mexico
Europe — Germany, UK, France, Italy, Spain
Asia-Pacific — China, Japan, India, South Korea, ASEAN
Latin America — Brazil, Mexico, Argentina
Middle East & Africa — Saudi Arabia, UAE, South Africa
Our analysis suggests the North America–Asia-Pacific gap will narrow by 2031 as Chinese OEMs ship monthly feature releases and India's AIS 189/190 standards force update capability into the world's third-largest light-vehicle market.
What is driving growth — and what is holding it back?
Regulation and electrification are the dominant accelerants, while cybersecurity exposure and legacy ECU fragmentation cap how fast OTA can scale across the installed base.
Extends compliance obligations to largest producer
Expanding cyber-attack surface
Restraint
Medium
Security validation slows release cadence
Legacy ECU fragmentation
Restraint
High
70–100 discrete ECUs resist delta updates
Connectivity gaps
Restraint
Medium
Rural and emerging markets delay delivery
The balance favors growth: compliance deadlines are non-negotiable and create a captive upgrade cycle, while restraints are engineering problems with clear commercial solutions. The key implication is that OTA budgets are now defensive as much as offensive.
Who are the leading vendors?
Competition splits between vertically integrated OEMs, tier-1 suppliers and silicon/platform providers; no single player controls end-to-end delivery, and market concentration is medium.
Company
Category
Primary Strength
Tesla
OEM
Full-stack OTA and subscription monetization
Volkswagen AG
OEM
Zonal architecture and software JV scale
General Motors
OEM
Fleet-wide update deployment
Hyundai / Toyota
OEM
Mass-market connected-car parc
Robert Bosch
Tier-1
ECU and update-management systems
Continental AG
Tier-1
Telematics and backend integration
Harman International
Tier-1
Connected-car and OTA platforms
Qualcomm
Silicon / Platform
Snapdragon auto and V2X pipeline
Our analysis suggests the durable moat is not the update engine but the certified audit trail and rollback capability required by R156 — a switching cost that locks OEMs into platform providers for full vehicle life cycles.
What do buyers and operators need to know?
Buyers should prioritize certified update-management systems with documented RXSWIN traceability, rollback safety and multi-network delivery, because these are now type-approval conditions rather than optional features.
Procurement risk concentrates in vendor lock-in and cybersecurity liability: an OTA platform that cannot demonstrate penetration testing and signed-package integrity exposes the OEM to regulatory and reputational loss. Switching costs are high once backend integrations, eSIM agreements and fleet telemetry are embedded, so total cost of ownership should be modeled over at least seven years.
Fleet operators should negotiate update cadence SLAs tied to uptime, since predictive-maintenance OTA directly reduces unscheduled downtime. Finally, buyers must verify satellite or Wi-Fi fallback for regions with weak cellular coverage, where 70% cellular dependence remains a single point of failure.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a compliance-led growth thesis over a pure monetization thesis. Regulation creates a guaranteed baseline of OTA investment across 54 UNECE markets and now China, which is more reliable than consumer subscription uptake. The strongest counter-argument is that feature-as-a-service could accelerate revenue well beyond 20% CAGR; however, BMW's heated-seat retreat shows consumer resistance is real, and only Tesla has proven durable recurring software revenue at scale.
Second-order effects matter more than headline growth. As FOTA extends into powertrain and battery controllers, the liability profile shifts from infotainment glitches to safety-critical outcomes, raising validation costs and favoring suppliers with certified toolchains. This dynamic will consolidate share toward Bosch, Continental, Harman and Qualcomm at the expense of fragmented point solutions.
OEMs and tier-1s should invest in R156-certified update-management infrastructure now to protect type approvals through 2031.
Platform vendors should target commercial fleets, where uptime economics justify premium pricing and update cadence is contractually enforceable.
Investors should weight exposure toward FOTA and safety-update segments growing above 21% CAGR rather than mature SOTA infotainment.
Evidence that would change our conclusion: sustained subscription attach rates above 30% across mass-market brands, or regulatory relaxation of R156 audit requirements, would shift us toward a more aggressive monetization-led outlook.
Automotive Over The Air Updates Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Automotive Over The Air Updates Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 19.79% from 2020-2034
Segmentation
By Technology
SOTA
FOTA
By Application
Telematics Gateway
ECU
Infotainment
Safety and Security
Remote Diagnostics
By Propulsion
ICE
Electric Vehicle
By Vehicle Type
Passenger Cars
Commercial Vehicles
By Communication Type
Cellular
Wi-Fi
Satellite
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
ASEAN
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Technology
5.1.1. SOTA
5.1.2. FOTA
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Telematics Gateway
5.2.2. ECU
5.2.3. Infotainment
5.2.4. Safety and Security
5.2.5. Remote Diagnostics
5.3. Market Analysis, Insights and Forecast - by Propulsion
5.3.1. ICE
5.3.2. Electric Vehicle
5.4. Market Analysis, Insights and Forecast - by Vehicle Type
5.4.1. Passenger Cars
5.4.2. Commercial Vehicles
5.5. Market Analysis, Insights and Forecast - by Communication Type
5.5.1. Cellular
5.5.2. Wi-Fi
5.5.3. Satellite
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Technology
6.1.1. SOTA
6.1.2. FOTA
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Telematics Gateway
6.2.2. ECU
6.2.3. Infotainment
6.2.4. Safety and Security
6.2.5. Remote Diagnostics
6.3. Market Analysis, Insights and Forecast - by Propulsion
6.3.1. ICE
6.3.2. Electric Vehicle
6.4. Market Analysis, Insights and Forecast - by Vehicle Type
6.4.1. Passenger Cars
6.4.2. Commercial Vehicles
6.5. Market Analysis, Insights and Forecast - by Communication Type
6.5.1. Cellular
6.5.2. Wi-Fi
6.5.3. Satellite
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Technology
7.1.1. SOTA
7.1.2. FOTA
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Telematics Gateway
7.2.2. ECU
7.2.3. Infotainment
7.2.4. Safety and Security
7.2.5. Remote Diagnostics
7.3. Market Analysis, Insights and Forecast - by Propulsion
7.3.1. ICE
7.3.2. Electric Vehicle
7.4. Market Analysis, Insights and Forecast - by Vehicle Type
7.4.1. Passenger Cars
7.4.2. Commercial Vehicles
7.5. Market Analysis, Insights and Forecast - by Communication Type
7.5.1. Cellular
7.5.2. Wi-Fi
7.5.3. Satellite
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Technology
8.1.1. SOTA
8.1.2. FOTA
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Telematics Gateway
8.2.2. ECU
8.2.3. Infotainment
8.2.4. Safety and Security
8.2.5. Remote Diagnostics
8.3. Market Analysis, Insights and Forecast - by Propulsion
8.3.1. ICE
8.3.2. Electric Vehicle
8.4. Market Analysis, Insights and Forecast - by Vehicle Type
8.4.1. Passenger Cars
8.4.2. Commercial Vehicles
8.5. Market Analysis, Insights and Forecast - by Communication Type
8.5.1. Cellular
8.5.2. Wi-Fi
8.5.3. Satellite
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Technology
9.1.1. SOTA
9.1.2. FOTA
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Telematics Gateway
9.2.2. ECU
9.2.3. Infotainment
9.2.4. Safety and Security
9.2.5. Remote Diagnostics
9.3. Market Analysis, Insights and Forecast - by Propulsion
9.3.1. ICE
9.3.2. Electric Vehicle
9.4. Market Analysis, Insights and Forecast - by Vehicle Type
9.4.1. Passenger Cars
9.4.2. Commercial Vehicles
9.5. Market Analysis, Insights and Forecast - by Communication Type
9.5.1. Cellular
9.5.2. Wi-Fi
9.5.3. Satellite
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Technology
10.1.1. SOTA
10.1.2. FOTA
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Telematics Gateway
10.2.2. ECU
10.2.3. Infotainment
10.2.4. Safety and Security
10.2.5. Remote Diagnostics
10.3. Market Analysis, Insights and Forecast - by Propulsion
10.3.1. ICE
10.3.2. Electric Vehicle
10.4. Market Analysis, Insights and Forecast - by Vehicle Type
10.4.1. Passenger Cars
10.4.2. Commercial Vehicles
10.5. Market Analysis, Insights and Forecast - by Communication Type
10.5.1. Cellular
10.5.2. Wi-Fi
10.5.3. Satellite
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Automotive Over The Air Updates Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Automotive Over The Air Updates Market Revenue (Billion), by Technology 2026 & 2034
Figure 3: North America Automotive Over The Air Updates Market Revenue Share (%), by Technology 2026 & 2034
Figure 4: North America Automotive Over The Air Updates Market Revenue (Billion), by Application 2026 & 2034
Figure 5: North America Automotive Over The Air Updates Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Automotive Over The Air Updates Market Revenue (Billion), by Propulsion 2026 & 2034
Figure 7: North America Automotive Over The Air Updates Market Revenue Share (%), by Propulsion 2026 & 2034
Figure 8: North America Automotive Over The Air Updates Market Revenue (Billion), by Vehicle Type 2026 & 2034
Figure 9: North America Automotive Over The Air Updates Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 10: North America Automotive Over The Air Updates Market Revenue (Billion), by Communication Type 2026 & 2034
Figure 11: North America Automotive Over The Air Updates Market Revenue Share (%), by Communication Type 2026 & 2034
Figure 12: North America Automotive Over The Air Updates Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Automotive Over The Air Updates Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Automotive Over The Air Updates Market Revenue (Billion), by Technology 2026 & 2034
Figure 15: Europe Automotive Over The Air Updates Market Revenue Share (%), by Technology 2026 & 2034
List of Tables
Table 1: Automotive Over The Air Updates Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 2: Automotive Over The Air Updates Market Revenue Billion Forecast, by Application 2020 & 2034
Table 3: Automotive Over The Air Updates Market Revenue Billion Forecast, by Propulsion 2020 & 2034
Table 4: Automotive Over The Air Updates Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 5: Automotive Over The Air Updates Market Revenue Billion Forecast, by Communication Type 2020 & 2034
Table 6: Automotive Over The Air Updates Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Automotive Over The Air Updates Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 8: North America Automotive Over The Air Updates Market Revenue Billion Forecast, by Application 2020 & 2034
Table 9: North America Automotive Over The Air Updates Market Revenue Billion Forecast, by Propulsion 2020 & 2034
Table 10: North America Automotive Over The Air Updates Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 11: North America Automotive Over The Air Updates Market Revenue Billion Forecast, by Communication Type 2020 & 2034
Table 12: North America Automotive Over The Air Updates Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Automotive Over The Air Updates Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Automotive Over The Air Updates Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Automotive Over The Air Updates Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the automotive over-the-air updates market?
The market was valued at USD 5.90 billion in 2026 and is forecast to reach USD 14.55 billion by 2031, growing at a 19.79% CAGR. North America leads with roughly 44% revenue share, while Asia-Pacific is the fastest-growing region.
2. What is the difference between SOTA and FOTA?
SOTA updates software layers such as infotainment, navigation and apps, and held 68.14% of 2025 revenue. FOTA updates firmware on ECUs, powertrain and battery controllers and is growing faster at 22.74% CAGR through 2031.
3. Which region is the fastest-growing for OTA updates?
Asia-Pacific is the fastest-growing region at roughly 20–22% CAGR, driven by Chinese EV makers shipping monthly feature releases and new Indian standards AIS 189 and AIS 190 mandating update capability in the world's third-largest light-vehicle market.
4. What regulations require automotive OTA capability?
UNECE R155 and R156 require certified cybersecurity and software update management systems for type approval across 54 signatory countries, mandatory for new EU vehicle types since July 2024. China's GB 44496-2024 and India's AIS standards impose comparable obligations.
5. Who are the leading companies in the OTA updates market?
Leading players include Tesla, Volkswagen, General Motors, Hyundai and Toyota among OEMs, plus Robert Bosch, Continental, Harman International, Aptiv, NXP and Qualcomm among tier-1 suppliers and platform providers. Market concentration is medium.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the OTA value chain, spanning OEM software divisions, tier-1 ECU and telematics suppliers, semiconductor and connectivity platform providers, and fleet operators. Respondents were drawn from decision-maker designations including VP of Software Engineering, Heads of Connected Vehicle R&D, Chief Cybersecurity Officers and Commercial Fleet Operations Leads. Interview data were used to calibrate update-frequency assumptions, deployment cost curves and procurement cycles.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP Software Engineering & Connected Vehicle Heads
38%
Cybersecurity & Regulatory Compliance Leads
27%
Commercial Fleet Operations Leads
20%
Procurement & Sourcing Directors
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
OEM Software & Connected Vehicle Divisions
40%
Tier-1 ECU & Telematics Suppliers
30%
Semiconductor & Connectivity Platforms
18%
Commercial Fleet Operators
12%
Secondary Benchmarking & Public Trade Validation
Estimates were benchmarked against bilateral and multilateral trade databases (UN Comtrade, WTO, Eurostat, US ITC), corporate annual filings (10-K, 20-F, investor presentations), patent filings and recognized standards bodies including UNECE WP.29, ISO/SAE 21434 and national type-approval authorities. Supplier disclosures on connected-vehicle parc and update cadence were cross-checked against regulatory registration data.
Demand Modeling & Market Sizing Triangulation
Market sizing triangulates Top-Down allocation from global automotive software and connectivity spend against Bottom-Up modeling of connected-vehicle parc, update-capable ECU penetration and average annual update revenue per vehicle. Forecasts incorporate regulatory timelines, EV adoption scenarios and network rollout schedules, with sensitivity testing on subscription attach rates and FOTA penetration.
 Automotive Over The Air Updates Market