Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Automotive Metal Market: 2026 Size, Share & Forecast
Automotive Metal Market
Automotive Metal Market: 2026 Size, Share & Forecast
Automotive Metal Market by Metal Type (Steel, Aluminum, Magnesium, Copper, Titanium, Nickel, Zinc, Others), by Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, Electric Vehicles, Hybrid Vehicles), by Product Form (Flat Products, Long Products, Castings, Forgings, Extrusions, Tubes & Pipes), by Application (Body Structure, Chassis & Suspension, Powertrain, Wheels & Tires, Battery Components, Others), by End-user (OEMs, Aftermarket), by Manufacturing Process (Stamping, Casting, Forging, Rolling, Extrusion, Additive Manufacturing), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Russia), by Asia Pacific (China, Japan, India, South Korea, ASEAN), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Turkey) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 278
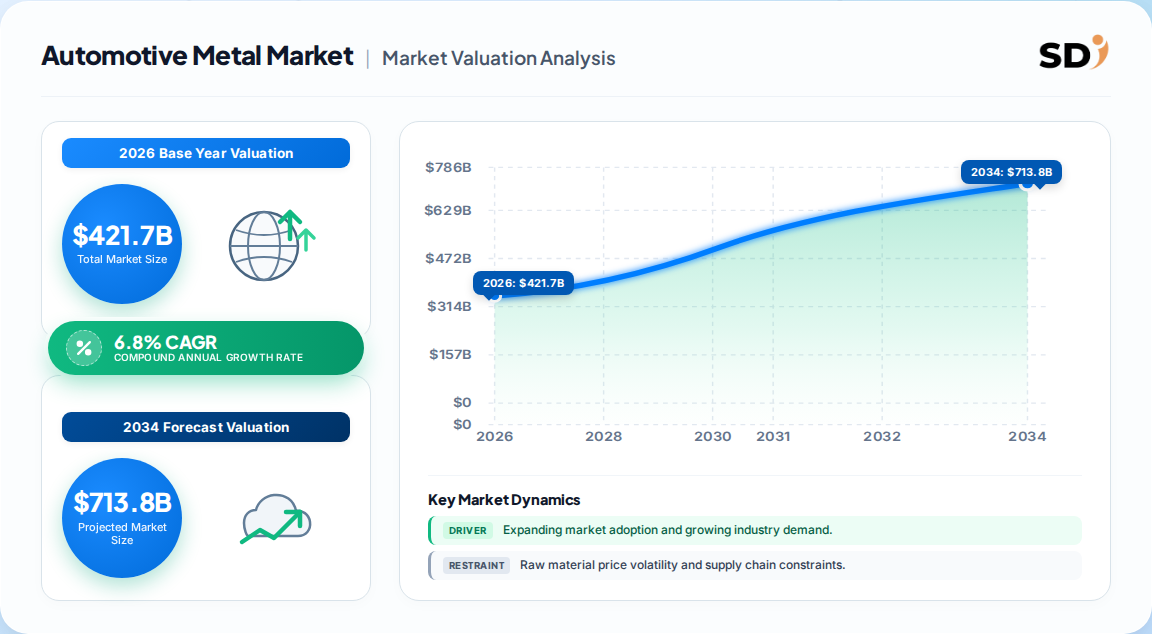
The global automotive metal market is valued at USD 421.7 billion in 2026 and forecast to reach USD 668.3 billion by 2033, a 6.8% CAGR.
Steel remains the anchor material, holding roughly 53–56% revenue share, sustained by advanced high-strength steel adoption in body structures and chassis.
Asia Pacific commands ~49% of global revenue, with China alone accounting for over 23% of consumption; the region also grows fastest at 6.1–8.1%.
Battery components are the fastest-growing application (~18% CAGR), driven by EV battery enclosures, e-drive housings, and thermal management hardware.
Leading vendors include ArcelorMittal, Nippon Steel, POSCO, China Baowu, Novelis, and thyssenkrupp, competing on advanced grades and low-carbon supply.
Why this matters for decision-makers: Suppliers must pivot to EV-specific aluminum and AHSS products while securing low-carbon production credentials — otherwise margin compression from commodity steel and CBAM cost penalties is unavoidable.
Automotive Metal Market Size (In Billion)
750.0B
600.0B
450.0B
300.0B
150.0B
0
421.7 B
2026
450.4 B
2027
481.0 B
2028
513.7 B
2029
548.6 B
2030
585.9 B
2031
625.8 B
2032
Automotive Metal Market Size (In Billion)
Year
Market Size
2026
421.7 B
2027
450.4 B
2028
481.0 B
2029
513.7 B
2030
548.6 B
2031
585.9 B
2032
625.8 B
What is the automotive metal market?
The automotive metal market encompasses the global supply of steel, aluminum, magnesium, copper, and other metals processed into vehicle body structures, powertrains, suspensions, battery enclosures, and chassis components. It serves OEM assembly lines and aftermarket replacement demand across passenger cars, commercial vehicles, and electric platforms.
Scope: what this report covers and excludes
This report covers automotive-grade metal products — flat products, long products, castings, forgings, and extrusions — sold to OEMs and aftermarket channels across all vehicle types. It excludes upstream mining and ore extraction, non-automotive metal demand (construction, packaging, aerospace), and battery cathode or anode active materials.
How big is the automotive metal market?
Estimates diverge materially because publishers define the addressable product set differently, ranging from USD 152 billion to USD 422 billion for the same 2025–2026 base year. The table below reconciles the major published benchmark ranges.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 421.7 billion
2026
2033
6.8%
Comprehensive: all metals, vehicle types, EV/hybrid, OEM + aftermarket
One published estimate
USD 668.3 billion
2033
2033
6.8%
Same comprehensive definition, forecast endpoint
One published estimate
USD 173.9–184.3 billion
2025
2030–2035
4.9–5.2%
Narrower product scope, fewer metal types
Competing analysis
USD 152.4 billion
2025
2033
3.4%
Body sheet metal-centric, limited EV segmentation
Competing analysis
Our analysis suggests the USD 421.7 billion 2026 figure is the most defensible comprehensive estimate because it aligns with global vehicle production of ~92 million units and average per-vehicle metal content of roughly USD 4,500–4,800. The lower USD 152–184 billion estimates likely exclude castings, forgings, and aftermarket volumes, understating true OEM procurement spend. The 6.8% CAGR sits between the aggressive 7.7% and conservative 3.4% projections and matches the mid-point of regulatory-driven lightweighting demand.
How is the automotive metal market segmented?
The market segments by metal type, vehicle type, product form, application, and end-user, with steel and body structure dominating revenue while battery components and aluminum grow fastest.
Which region leads in the automotive metal market?
Asia Pacific leads the global automotive metal market with approximately 49% revenue share in 2025, underpinned by China's position as the world's largest vehicle and EV producer, plus integrated steel and aluminum supply chains serving over 30 million vehicles annually.
Automotive Metal Market Regional Market Share
Loading chart...
Automotive Metal Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.49%
Europe
0.23%
North America
0.18%
South America
0.05%
Middle East & Africa
0.05%
Region
Share (2025)
CAGR (2026–2033)
Asia Pacific
~49%
6.1–8.1%
Europe
~23%
2.8–5.4%
North America
~18%
3.1%
Latin America
~5%
2.6–4.4%
Middle East & Africa
~5%
2.9%
Asia Pacific: China, Japan, India, South Korea, ASEAN
Europe: Germany, France, Italy, UK, Spain, Russia
North America: USA, Canada, Mexico
Latin America: Brazil, Mexico, Argentina
Middle East & Africa: Saudi Arabia, UAE, South Africa, Turkey
This divergence implies that suppliers without an Asia Pacific footprint will be structurally disadvantaged as EV platform localization accelerates; India's production-linked incentive scheme (~USD 3.1 billion) and China's 12.87 million NEV sales in 2024 are the strongest regional demand anchors.
What is driving growth — and what is holding it back?
Growth is driven by mandatory lightweighting regulation and EV production scale-up, while raw material volatility, energy costs, and supply chain concentration restrain margins and expansion velocity.
Factor
Direction
Evidence Strength
Mechanism
CO2 and fuel-economy regulation
Driver
High
Mandates mass reduction; EU 55% cut by 2030, US ~50 mpg by 2031
EV production surge
Driver
High
EVs use 25–30% more aluminum; 17M+ global EV sales in 2024
Defends steel share with >1,000 MPa grades on existing press lines
Low-carbon procurement
Driver
Medium
Scope 3 targets and CBAM create 15–25% import cost penalty
Raw material & energy volatility
Restraint
High
Energy is 20–35% of steel cost; aluminum smelting 14–15 MWh/tonne
Slower EV uptake / policy reversal
Restraint
Medium
US policy uncertainty may delay lightweighting investments
Critical metal import concentration
Restraint
Medium
Magnesium and rare-earth supply chain fragility
Our analysis suggests the drivers outweigh restraints through 2033, but the balance is uneven: regulatory-driven demand is structural, whereas cost volatility is cyclical and disproportionately harms mid-tier producers lacking captive energy or hedging infrastructure.
Who are the leading vendors?
ArcelorMittal, Nippon Steel, POSCO, China Baowu, and Novelis lead a moderately concentrated competitive landscape where differentiation rests on advanced product grades, low-carbon credentials, and proximity to OEM assembly hubs.
Company
Position
Key Strength
ArcelorMittal
Market Leader
Broad global steel portfolio, AHSS grades, deep OEM relationships
Nippon Steel
Major Supplier
Advanced steel grades, engineering support, Japanese OEM ties
POSCO Holdings
Major Supplier
High-quality automotive steel, strong Asian presence
This implies that competitive moats are shifting from sheer tonnage to qualification cycles for EV-specific alloys and verified low-carbon supply, where incumbents with closed-loop recycling and EAF capacity hold durable advantages. New entrants face 6-month lead times for automotive-grade 6000-series aluminum, a barrier that protects established processors.
What do buyers and operators need to know?
Procurement decisions now hinge on three mission-critical criteria: the supplier's ability to qualify EV-specific alloys (6000-series aluminum, high-ductility casting alloys), verified low-carbon production pathways aligned with CSRD and CBAM, and regional finishing assets that shorten delivery cycles. Switching costs are high because automotive-grade material qualification typically requires 12–18 months of crash and durability testing; buyers should therefore prioritize long-term supply agreements with producers investing in local stamping and distribution. Lead times for specialized aluminum alloys have stretched to six months versus a two-month historical norm, creating working-capital risk for OEMs that have not secured capacity. Regulatory compliance — EU CO2 rules, US EPA tailpipe standards, and CBAM — is no longer a downstream concern; it directly determines which metals qualify for platform sourcing.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors sustained growth in automotive metal demand, but the composition of that growth is shifting decisively toward aluminum and AHSS at the expense of commodity mild steel. The 6.8% CAGR consensus is credible because it sits at the intersection of regulatory mandates and EV platform localization, both of which lock in multi-year material volumes. The strongest counter-argument is that slower-than-expected EV adoption in North America and Europe could defer lightweighting investment; however, even in a delayed-EV scenario, CO2 compliance and fuel-economy rules keep mass-reduction spending intact.
Actionable Strategy:
Investors: Prioritize aluminum processors and AHSS-capable steelmakers with verified low-carbon capacity; avoid undifferentiated commodity steel exposure.
Operators: Secure 12–18 month supply agreements for automotive-grade aluminum now; the qualification bottleneck will intensify through 2028.
Vendors: Invest in regional finishing and stamping assets near EV assembly hubs to capture the 15–25% CBAM cost advantage over high-carbon imports.
What would change our conclusion: a sustained reversal of EU or US emissions rules, or a technological breakthrough in battery energy density that reduces the need for structural lightweighting, would materially lower the 6.8% CAGR trajectory. Absent those, the structural demand case remains intact.
Automotive Metal Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Automotive Metal Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.8% from 2020-2034
Segmentation
By Metal Type
Steel
Aluminum
Magnesium
Copper
Titanium
Nickel
Zinc
Others
By Vehicle Type
Passenger Cars
Light Commercial Vehicles
Heavy Commercial Vehicles
Electric Vehicles
Hybrid Vehicles
By Product Form
Flat Products
Long Products
Castings
Forgings
Extrusions
Tubes & Pipes
By Application
Body Structure
Chassis & Suspension
Powertrain
Wheels & Tires
Battery Components
Others
By End-user
OEMs
Aftermarket
By Manufacturing Process
Stamping
Casting
Forging
Rolling
Extrusion
Additive Manufacturing
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Russia
Asia Pacific
China
Japan
India
South Korea
ASEAN
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Turkey
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Metal Type
5.1.1. Steel
5.1.2. Aluminum
5.1.3. Magnesium
5.1.4. Copper
5.1.5. Titanium
5.1.6. Nickel
5.1.7. Zinc
5.1.8. Others
5.2. Market Analysis, Insights and Forecast - by Vehicle Type
5.2.1. Passenger Cars
5.2.2. Light Commercial Vehicles
5.2.3. Heavy Commercial Vehicles
5.2.4. Electric Vehicles
5.2.5. Hybrid Vehicles
5.3. Market Analysis, Insights and Forecast - by Product Form
5.3.1. Flat Products
5.3.2. Long Products
5.3.3. Castings
5.3.4. Forgings
5.3.5. Extrusions
5.3.6. Tubes & Pipes
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Body Structure
5.4.2. Chassis & Suspension
5.4.3. Powertrain
5.4.4. Wheels & Tires
5.4.5. Battery Components
5.4.6. Others
5.5. Market Analysis, Insights and Forecast - by End-user
5.5.1. OEMs
5.5.2. Aftermarket
5.6. Market Analysis, Insights and Forecast - by Manufacturing Process
5.6.1. Stamping
5.6.2. Casting
5.6.3. Forging
5.6.4. Rolling
5.6.5. Extrusion
5.6.6. Additive Manufacturing
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Latin America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Metal Type
6.1.1. Steel
6.1.2. Aluminum
6.1.3. Magnesium
6.1.4. Copper
6.1.5. Titanium
6.1.6. Nickel
6.1.7. Zinc
6.1.8. Others
6.2. Market Analysis, Insights and Forecast - by Vehicle Type
6.2.1. Passenger Cars
6.2.2. Light Commercial Vehicles
6.2.3. Heavy Commercial Vehicles
6.2.4. Electric Vehicles
6.2.5. Hybrid Vehicles
6.3. Market Analysis, Insights and Forecast - by Product Form
6.3.1. Flat Products
6.3.2. Long Products
6.3.3. Castings
6.3.4. Forgings
6.3.5. Extrusions
6.3.6. Tubes & Pipes
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Body Structure
6.4.2. Chassis & Suspension
6.4.3. Powertrain
6.4.4. Wheels & Tires
6.4.5. Battery Components
6.4.6. Others
6.5. Market Analysis, Insights and Forecast - by End-user
6.5.1. OEMs
6.5.2. Aftermarket
6.6. Market Analysis, Insights and Forecast - by Manufacturing Process
6.6.1. Stamping
6.6.2. Casting
6.6.3. Forging
6.6.4. Rolling
6.6.5. Extrusion
6.6.6. Additive Manufacturing
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Metal Type
7.1.1. Steel
7.1.2. Aluminum
7.1.3. Magnesium
7.1.4. Copper
7.1.5. Titanium
7.1.6. Nickel
7.1.7. Zinc
7.1.8. Others
7.2. Market Analysis, Insights and Forecast - by Vehicle Type
7.2.1. Passenger Cars
7.2.2. Light Commercial Vehicles
7.2.3. Heavy Commercial Vehicles
7.2.4. Electric Vehicles
7.2.5. Hybrid Vehicles
7.3. Market Analysis, Insights and Forecast - by Product Form
7.3.1. Flat Products
7.3.2. Long Products
7.3.3. Castings
7.3.4. Forgings
7.3.5. Extrusions
7.3.6. Tubes & Pipes
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Body Structure
7.4.2. Chassis & Suspension
7.4.3. Powertrain
7.4.4. Wheels & Tires
7.4.5. Battery Components
7.4.6. Others
7.5. Market Analysis, Insights and Forecast - by End-user
7.5.1. OEMs
7.5.2. Aftermarket
7.6. Market Analysis, Insights and Forecast - by Manufacturing Process
7.6.1. Stamping
7.6.2. Casting
7.6.3. Forging
7.6.4. Rolling
7.6.5. Extrusion
7.6.6. Additive Manufacturing
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Metal Type
8.1.1. Steel
8.1.2. Aluminum
8.1.3. Magnesium
8.1.4. Copper
8.1.5. Titanium
8.1.6. Nickel
8.1.7. Zinc
8.1.8. Others
8.2. Market Analysis, Insights and Forecast - by Vehicle Type
8.2.1. Passenger Cars
8.2.2. Light Commercial Vehicles
8.2.3. Heavy Commercial Vehicles
8.2.4. Electric Vehicles
8.2.5. Hybrid Vehicles
8.3. Market Analysis, Insights and Forecast - by Product Form
8.3.1. Flat Products
8.3.2. Long Products
8.3.3. Castings
8.3.4. Forgings
8.3.5. Extrusions
8.3.6. Tubes & Pipes
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Body Structure
8.4.2. Chassis & Suspension
8.4.3. Powertrain
8.4.4. Wheels & Tires
8.4.5. Battery Components
8.4.6. Others
8.5. Market Analysis, Insights and Forecast - by End-user
8.5.1. OEMs
8.5.2. Aftermarket
8.6. Market Analysis, Insights and Forecast - by Manufacturing Process
8.6.1. Stamping
8.6.2. Casting
8.6.3. Forging
8.6.4. Rolling
8.6.5. Extrusion
8.6.6. Additive Manufacturing
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Metal Type
9.1.1. Steel
9.1.2. Aluminum
9.1.3. Magnesium
9.1.4. Copper
9.1.5. Titanium
9.1.6. Nickel
9.1.7. Zinc
9.1.8. Others
9.2. Market Analysis, Insights and Forecast - by Vehicle Type
9.2.1. Passenger Cars
9.2.2. Light Commercial Vehicles
9.2.3. Heavy Commercial Vehicles
9.2.4. Electric Vehicles
9.2.5. Hybrid Vehicles
9.3. Market Analysis, Insights and Forecast - by Product Form
9.3.1. Flat Products
9.3.2. Long Products
9.3.3. Castings
9.3.4. Forgings
9.3.5. Extrusions
9.3.6. Tubes & Pipes
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Body Structure
9.4.2. Chassis & Suspension
9.4.3. Powertrain
9.4.4. Wheels & Tires
9.4.5. Battery Components
9.4.6. Others
9.5. Market Analysis, Insights and Forecast - by End-user
9.5.1. OEMs
9.5.2. Aftermarket
9.6. Market Analysis, Insights and Forecast - by Manufacturing Process
9.6.1. Stamping
9.6.2. Casting
9.6.3. Forging
9.6.4. Rolling
9.6.5. Extrusion
9.6.6. Additive Manufacturing
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Metal Type
10.1.1. Steel
10.1.2. Aluminum
10.1.3. Magnesium
10.1.4. Copper
10.1.5. Titanium
10.1.6. Nickel
10.1.7. Zinc
10.1.8. Others
10.2. Market Analysis, Insights and Forecast - by Vehicle Type
10.2.1. Passenger Cars
10.2.2. Light Commercial Vehicles
10.2.3. Heavy Commercial Vehicles
10.2.4. Electric Vehicles
10.2.5. Hybrid Vehicles
10.3. Market Analysis, Insights and Forecast - by Product Form
10.3.1. Flat Products
10.3.2. Long Products
10.3.3. Castings
10.3.4. Forgings
10.3.5. Extrusions
10.3.6. Tubes & Pipes
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Body Structure
10.4.2. Chassis & Suspension
10.4.3. Powertrain
10.4.4. Wheels & Tires
10.4.5. Battery Components
10.4.6. Others
10.5. Market Analysis, Insights and Forecast - by End-user
10.5.1. OEMs
10.5.2. Aftermarket
10.6. Market Analysis, Insights and Forecast - by Manufacturing Process
10.6.1. Stamping
10.6.2. Casting
10.6.3. Forging
10.6.4. Rolling
10.6.5. Extrusion
10.6.6. Additive Manufacturing
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Automotive Metal Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Automotive Metal Market Revenue (Billion), by Metal Type 2026 & 2034
Figure 3: North America Automotive Metal Market Revenue Share (%), by Metal Type 2026 & 2034
Figure 4: North America Automotive Metal Market Revenue (Billion), by Vehicle Type 2026 & 2034
Figure 5: North America Automotive Metal Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 6: North America Automotive Metal Market Revenue (Billion), by Product Form 2026 & 2034
Figure 7: North America Automotive Metal Market Revenue Share (%), by Product Form 2026 & 2034
Figure 8: North America Automotive Metal Market Revenue (Billion), by Application 2026 & 2034
Figure 9: North America Automotive Metal Market Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Automotive Metal Market Revenue (Billion), by End-user 2026 & 2034
Figure 11: North America Automotive Metal Market Revenue Share (%), by End-user 2026 & 2034
Figure 12: North America Automotive Metal Market Revenue (Billion), by Manufacturing Process 2026 & 2034
Figure 13: North America Automotive Metal Market Revenue Share (%), by Manufacturing Process 2026 & 2034
Figure 14: North America Automotive Metal Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Automotive Metal Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Automotive Metal Market Revenue (Billion), by Metal Type 2026 & 2034
List of Tables
Table 1: Automotive Metal Market Revenue Billion Forecast, by Metal Type 2020 & 2034
Table 2: Automotive Metal Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 3: Automotive Metal Market Revenue Billion Forecast, by Product Form 2020 & 2034
Table 4: Automotive Metal Market Revenue Billion Forecast, by Application 2020 & 2034
Table 5: Automotive Metal Market Revenue Billion Forecast, by End-user 2020 & 2034
Table 6: Automotive Metal Market Revenue Billion Forecast, by Manufacturing Process 2020 & 2034
Table 7: Automotive Metal Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Automotive Metal Market Revenue Billion Forecast, by Metal Type 2020 & 2034
Table 9: North America Automotive Metal Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 10: North America Automotive Metal Market Revenue Billion Forecast, by Product Form 2020 & 2034
Table 11: North America Automotive Metal Market Revenue Billion Forecast, by Application 2020 & 2034
Table 12: North America Automotive Metal Market Revenue Billion Forecast, by End-user 2020 & 2034
Table 13: North America Automotive Metal Market Revenue Billion Forecast, by Manufacturing Process 2020 & 2034
Table 14: North America Automotive Metal Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA Automotive Metal Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Canada Automotive Metal Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the automotive metal market?
The global automotive metal market is valued at approximately USD 421.7 billion in 2026 and is forecast to reach USD 668.3 billion by 2033, growing at a 6.8% CAGR. Estimates vary by scope, with narrower definitions placing the 2025 base closer to USD 152–184 billion.
2. Which metal type dominates the automotive metal market?
Steel dominates with roughly 53–56% revenue share, driven by advanced high-strength steel in body structures and chassis. Aluminum is the fastest-growing metal type at 8.7–9.2% CAGR, fueled by EV battery enclosures and lightweighting mandates.
3. Which region leads the automotive metal market?
Asia Pacific leads with approximately 49% of global revenue in 2025, driven by China's vehicle and EV production dominance. It is also the fastest-growing region at 6.1–8.1% CAGR, supported by India's production-linked incentives and South Korea's EV investments.
4. What are the key growth drivers in the automotive metal market?
Stricter CO2 and fuel-economy regulations, rapid EV production scaling, megacasting adoption, and low-carbon procurement mandates are the primary drivers. EVs require 25–30% more aluminum than combustion vehicles, structurally raising per-vehicle metal content and value.
5. Who are the leading companies in the automotive metal market?
Leading vendors include ArcelorMittal, Nippon Steel, POSCO Holdings, China Baowu, Novelis, thyssenkrupp, and Nucor. Competition centers on advanced high-strength steel grades, automotive-grade aluminum alloys, and verified low-carbon production capabilities.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research methodology applies a 70/30 primary-to-secondary research split, prioritizing direct industry engagement to validate market sizing and demand signals. We conducted in-depth interviews with stakeholders across the automotive metal value chain, including raw material suppliers, specialized steel and aluminum producers, contract casting and forging specialists, and global distributors. Interviewees included VP-level Sourcing executives at OEMs, Heads of Materials R&D, Technical Directors at Tier-1 suppliers, and Commercial Operations Leads at metal producers. This fieldwork captured procurement criteria, qualification timelines, and capacity constraints that shape real supply dynamics.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing VPs
40%
Materials R&D Directors
35%
Commercial Operations Leads
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Steel & Aluminum Producers
45%
Casting & Forging Specialists
30%
Global Distributors & Traders
25%
Secondary Benchmarking & Public Trade Validation
We validated primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC disclosures, investor presentations), patent databases, and recognized technical standards and industry associations. These sources provided independent verification of cross-border metal flows, per-vehicle content benchmarks, and regulatory compliance thresholds.
Demand Modeling & Market Sizing Triangulation
We deployed simultaneous top-down and bottom-up modeling. Top-down allocation used macroeconomic vehicle production forecasts and powertrain-mix scenarios to size total addressable metal demand. Bottom-up modeling used manufacturer capacity data, product pricing, and end-use consumption by application to reconcile segment-level revenues. The two approaches were iterated until convergence within a 3% tolerance band.


 Automotive Metal Market