 Apac Automotive Telematics Market
APAC Automotive Telematics Market Size & Forecast 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 232

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Apac Automotive Telematics Market
Sadashiv Parab
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 18.70 B |
| 2026 | 20.54 B |
| 2027 | 22.55 B |
| 2028 | 24.77 B |
| 2029 | 27.20 B |
| 2030 | 29.87 B |
| 2031 | 32.79 B |

The APAC automotive telematics market covers embedded, tethered, and aftermarket systems that combine GPS/GNSS positioning, cellular connectivity, and vehicle-bus data to deliver fleet tracking, navigation, safety, insurance, and predictive-maintenance services across passenger and commercial vehicles in Asia-Pacific. It spans hardware, connectivity, and software-service revenue.
This analysis covers OEM-embedded, aftermarket hard-wired, and OBD-II dongle telematics across light, medium, and heavy commercial vehicles plus passenger cars in Asia-Pacific. It includes fleet/asset tracking, navigation, insurance telematics, and safety services across GNSS, cellular, and DSRC/C-V2X technologies. This analysis does not cover standalone ADAS sensor markets, EV charging infrastructure, in-vehicle infotainment content licensing, or telematics hardware component-level supply chains.
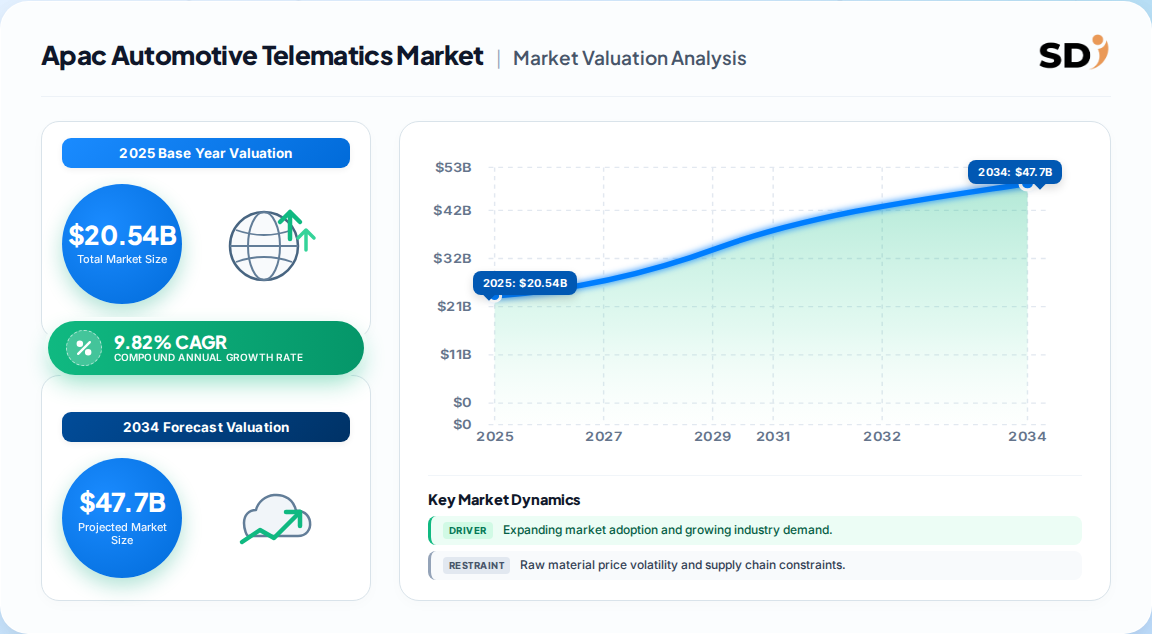
One published estimate puts the APAC automotive telematics market at USD 20.54 billion in 2026, reaching USD 32.79 billion by 2031 at a 9.82% CAGR — the most defensible figure because it isolates the APAC region and reconciles vehicle-type, channel, and service-type segment splits.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 18.70B → 32.79B | 2025 | 2031 | 9.82% | APAC-only, by vehicle type, channel, service, comms tech | One published estimate (regional) |
| USD 79.3B → 270.8B | 2025 | 2033 | 16.6% | Global automotive telematics, all solutions | A competing analysis (global) |
| USD 22.6B → 142.47B | 2024 | 2035 | 18.22% | Global automotive telematics, system-level | A competing analysis (global) |
The divergence is definitional, not contradictory. Global studies blend passenger-car connectivity, ADAS, and infotainment into a broader telematics envelope, inflating both base and CAGR. Our analysis suggests the APAC-only 9.82% figure is the credible planning anchor for commercial-fleet and compliance-driven buyers, while the 16.6–18.2% global CAGRs reflect passenger-vehicle embedded connectivity and emerging-market headroom. Buyers budgeting for APAC fleet deployments should anchor to the regional figure.
The market segments by vehicle type, channel, service type, and communication technology — with LCVs, OEM-embedded, fleet tracking, and GNSS each holding the largest current share but ceding relative ground to faster-growing niches.
| Parent Segment | Children | 2025 Share | Fastest Child (CAGR) |
|---|---|---|---|
| By Vehicle Type | Light CV, Medium & Heavy CV, Passenger | LCV 53.58% | MHCV 10.41% |
| By Channel | OEM-Embedded, Aftermarket Hard-Wired, OBD-II Dongle | OEM 41.89% | OBD-II 10.02% |
| By Service Type | Fleet/Asset Tracking, Navigation & Infotainment, Insurance Telematics, Safety | Fleet 36.12% | Insurance 11.02% |
| By Communication Tech | GNSS/GPS, Cellular, DSRC/C-V2X | GNSS 48.11% | DSRC/C-V2X 12.08% |
China leads with 37.62% of APAC telematics revenue in 2025, advancing at 9.96% CAGR through 2031, underpinned by factory-installed connectivity modules and state-backed smart-city pilots. India and ASEAN follow as regulation-driven fast-followers.
| Region | Market Share (%) |
|---|---|
| China | 0.38% |
| India | 0.16% |
| Japan | 0.12% |
| South Korea | 0.09% |
| Australia | 0.07% |
| Southeast Asia | 0.11% |
| Rest of APAC | 0.08% |
| Parent | Children |
|---|---|
| East Asia | China, Japan, South Korea |
| South Asia | India |
| Southeast Asia (ASEAN) | Indonesia, Thailand, Vietnam, Malaysia, Singapore |
| Oceania | Australia, New Zealand |
| Sub-Region | 2025 Share |
|---|---|
| China | 37.62% |
| India | 15.85% |
| Japan | 12.45% |
| Southeast Asia | 11.23% |
| South Korea | 8.62% |
| Australia | 6.55% |
| Rest of APAC | 7.68% |
Our analysis suggests China's share will ease slightly by 2031 as India and ASEAN compound faster off AIS-140 and eCall-style mandates, but China's module-integration depth keeps it the pricing reference for the region.
E-commerce last-mile fleet expansion (+2.3% CAGR impact) and OEM-installed connectivity proliferation (+2.1%) are the strongest growth drivers, while cybersecurity/data-privacy concerns (-1.6%) and semiconductor supply volatility (-1.4%) are the heaviest drags.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| E-commerce last-mile fleets | Driver +2.3% | High | Dynamic routing, battery tracking, geo-fencing |
| OEM connectivity modules | Driver +2.1% | High | Factory-fit eSIM, OTA, predictive maintenance |
| AIS-140 / eCall mandates | Driver +1.8% | High | Compliance-driven hardware attach |
| Usage-based insurance | Driver +1.4% | Medium | Data-driven premiums, loss-ratio gains |
| Cybersecurity & privacy | Restraint -1.6% | High | Compliance cost, data-localization rules |
| Semiconductor volatility | Restraint -1.4% | Medium | MCU/DRAM price spikes, dual-sourcing |
| Interoperability standards | Restraint -0.9% | Low | Cross-border fleet fragmentation |
The balance favors expansion: net driver impact exceeds restraints by roughly 4 percentage points, but the gap is narrowing as privacy regulation matures. Operators should treat cybersecurity spend as a growth enabler, not a tax — vendors that bundle managed-security services will capture premium pricing.
LG Electronics, MiX Telematics (Powerfleet), Tata Consultancy Services, Trimble, and Tech Mahindra anchor a medium-concentration competitive field, each differentiated by OEM relationships, software depth, or systems-integration reach.
| Vendor | Primary Strength | Moat Type |
|---|---|---|
| LG Electronics | OEM embedded modules | Hardware-scale & OEM ties |
| MiX Telematics (Powerfleet) | Fleet SaaS platform | Installed base & analytics |
| Tata Consultancy Services | Compliance & platform integration | Enterprise IT reach |
| Trimble | Fleet & asset tracking | Vertical software depth |
| Tech Mahindra | Connected-vehicle engineering | Systems-integration scale |
Differentiation is shifting from hardware to data platforms and compliance software. Our analysis suggests vendors with deep vehicle-bus integration and regional regulatory libraries will sustain pricing power, while generic aftermarket dongle makers face commoditization.
Selection should prioritize regulatory compliance coverage (AIS-140, eCall), data-localization capability, and API openness to avoid lock-in. Switching costs rise sharply once telematics is wired into vehicle buses and fleet workflows, so procurement should demand portable data schemas and exit clauses. Cybersecurity certifications and consent-management modules are now table stakes given diverging APAC privacy laws. Buyers should also stress-test vendor semiconductor dual-sourcing plans, as 2024–2025 supply shocks lifted unit costs and delayed deliveries. Total cost of ownership modeling must include connectivity subscriptions, OTA update cadence, and managed-security fees — not just hardware sticker price.
The balance of evidence favors a software-and-compliance-led growth thesis over hardware-volume plays. The APAC telematics market compounds near 10%, but the embedded channel's 94% attach trajectory by 2028 means aftermarket hardware margins compress structurally. Vendors and investors should position where recurring revenue and regulatory complexity intersect.
The strongest counter-argument is that price-sensitive Indian and Southeast Asian fleets will resist premium software bundles, sustaining a large low-cost dongle market. That is credible — OBD-II still grows at 10.02% — but it is a volume game with thin margins, not a value-creation story. The higher-return path is insurance telematics (11.02% CAGR), DSRC/C-V2X readiness (12.08% CAGR), and managed-security services.
Our conclusion would change if semiconductor costs normalize faster than expected and privacy regulation harmonizes across APAC — either would lift aftermarket hardware economics and narrow the software premium.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.82% from 2020-2034 |
| Segmentation |
|
The APAC automotive telematics market was valued at USD 20.54 billion in 2026 and is projected to reach USD 32.79 billion by 2031, growing at a 9.82% CAGR, driven by fleet digitization and regulatory mandates.
China leads with 37.62% of APAC telematics revenue in 2025, advancing at 9.96% CAGR through 2031, supported by factory-installed connectivity modules and smart-city pilots.
Insurance telematics is the fastest-growing service at 11.02% CAGR, while DSRC/C-V2X is the fastest-growing communication technology at 12.08% CAGR through 2031.
LG Electronics, MiX Telematics (Powerfleet), Tata Consultancy Services, Trimble, and Tech Mahindra are the major players in a medium-concentration competitive landscape.
E-commerce last-mile fleet expansion, OEM-installed connectivity proliferation, AIS-140 and eCall regulatory mandates, and rising usage-based insurance adoption are the primary growth drivers.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including telematics hardware manufacturers, OEM connectivity module suppliers, fleet-software platform providers, telecom connectivity partners, and regional fleet operators. Decision-maker designations interviewed included VP-level Fleet Operations, Heads of Connected-Vehicle Engineering, Procurement Directors for Commercial Fleets, and Regulatory Compliance Managers across China, India, Japan, and ASEAN markets.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Fleet Operations & Procurement Directors | 40% |
| Connected-Vehicle Engineering Heads | 30% |
| Regulatory & Compliance Managers | 30% |
| Company Type | Representation (%) |
|---|---|
| Telematics Hardware Manufacturers | 35% |
| Software & Platform Providers | 30% |
| Telecom & Connectivity Partners | 20% |
| Fleet Operators & Distributors | 15% |
Secondary validation drew on UN Comtrade and WTO trade databases, national automotive regulatory filings (including AIS-140 compliance records), corporate annual reports and 10-K filings, patent databases, and recognized technical standards bodies and industry associations. All benchmark figures were cross-checked against at least two independent public sources before inclusion.
Market sizing used simultaneous top-down allocation (macroeconomic fleet and GDP indicators by country) and bottom-up modeling (telematics unit shipments, attach rates, pricing, and service subscription revenue) to triangulate the base-year value and compound forecast to 2031.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |