 Automotive Steering Market
 Size, Share & Forecast to 2031
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 191

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Automotive Steering Market
Sadashiv Parab
Research Analyst

| Year | Market Size |
|---|---|
| 2026 | 36.85 B |
| 2027 | 38.81 B |
| 2028 | 40.88 B |
| 2029 | 43.06 B |
| 2030 | 45.35 B |
| 2031 | 47.77 B |

The automotive steering market encompasses the design, manufacture, and distribution of steering systems—including hydraulic power steering (HPS), electric power steering (EPS), and steer-by-wire—along with components such as steering columns, racks, sensors, and electric motors. It serves OEM and aftermarket channels across passenger and commercial vehicles, enabling vehicle control, safety, and ADAS integration.
This report covers the global automotive steering market with segmentation by component (hydraulic pump, electric motor, steering column/rack, sensors, other), mechanism (EPS, HPS, EHPS, steer-by-wire), vehicle type (passenger cars, commercial vehicles), and sales channel (OEM, aftermarket). It includes market sizing, forecasting, competitive analysis, and regional breakdowns across 2026–2031. This analysis does not cover adjacent markets such as braking systems, suspension systems, or autonomous driving software platforms.
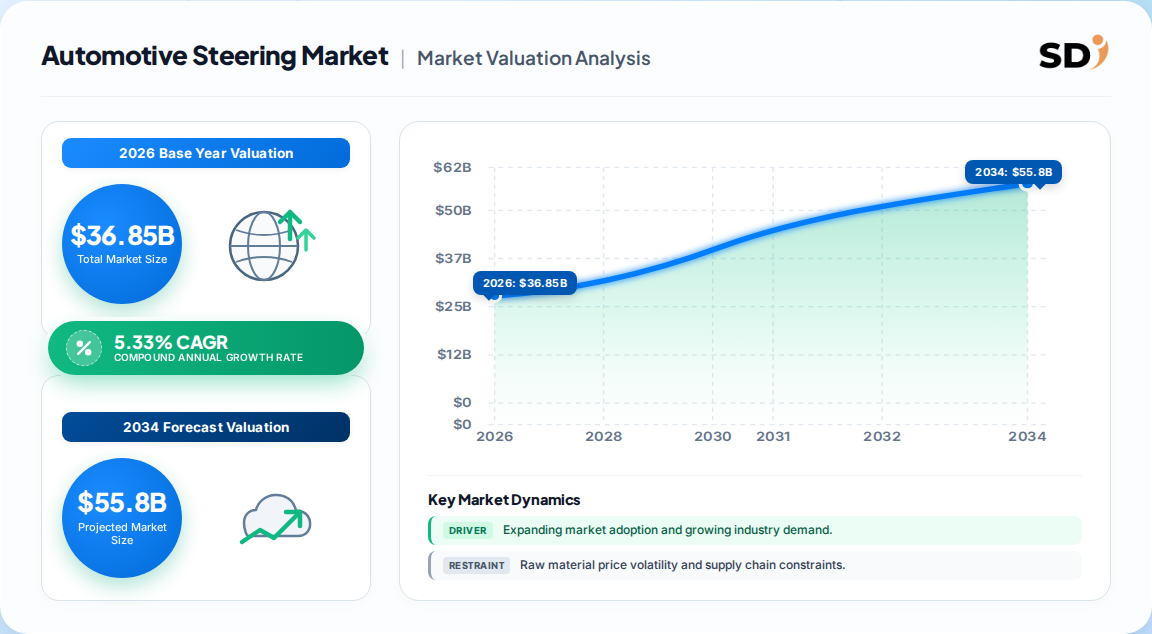
One published estimate values the global automotive steering market at USD 36.85 billion in 2026, rising to USD 47.77 billion by 2031 at a 5.33% CAGR. A competing analysis places the 2026 estimate at USD 29.8 billion, reaching USD 45.8 billion by 2033 at 5.9% CAGR. The divergence stems from differing scope definitions and base-year assumptions.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 36.85 Billion | 2026 | 2031 | 5.33% | Full steering systems incl. components, mechanisms, vehicle types, sales channels | One published estimate |
| USD 29.8 Billion | 2026 | 2033 | 5.9% | Steering systems incl. components, mechanisms, vehicle types; excludes some aftermarket | A competing analysis |
| USD 28.1 Billion | 2024 | 2033 | 5.9% | Broader automotive steering incl. hydraulic and electric systems | A competing analysis |
Our analysis suggests the 5.33% CAGR figure is more defensible for strategic planning because it aligns with observed EPS penetration rates, the GB17675-2025 regulatory timeline in China, and the measured pace of steer-by-wire serial production from ZF, Nexteer, and Mercedes-Benz. The lower base estimate likely excludes aftermarket revenue and some commercial vehicle segments.
The market is segmented by component, mechanism, vehicle type, and sales channel. EPS dominates mechanism share at 71.2%, while steering column/rack leads components at 38.74%. Passenger cars hold 62.65% of vehicle type share, and OEMs capture 86.7% of sales channel revenue.
| Parent Segment | Children | Leading Child (2025 Share) | Fastest-Growing Child (CAGR) |
|---|---|---|---|
| Component | Hydraulic Pump, Electric Motor, Steering Column/Rack, Sensors, Other | Steering Column/Rack (38.74%) | Electric Motor (8.53%) |
| Mechanism | EPS, HPS, EHPS, Steer-by-Wire | EPS (71.20%) | Steer-by-Wire (7.95%) |
| Vehicle Type | Passenger Cars, Commercial Vehicles | Passenger Cars (62.65%) | Commercial Vehicles (7.28%) |
| Sales Channel | OEM, Aftermarket | OEM (86.70%) | Aftermarket (7.02%) |
The segmentation reveals a market in transition: while EPS and passenger cars dominate current revenue, the fastest-growing segments—steer-by-wire, electric motors, and commercial vehicles—signal where capital and R&D are shifting. This implies suppliers must balance legacy EPS volume programs with investments in redundant, fail-operational architectures for premium EVs.
Asia Pacific leads the automotive steering market with 48.25% share in 2025, driven by China's NEV production and Japan's export-oriented OEM base. The region is also the fastest-growing at 6.52% CAGR through 2031. Europe follows with 22.1% share, and North America holds 18.3%.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.48% |
| Europe | 0.22% |
| North America | 0.18% |
| South America | 0.06% |
| Middle East & Africa | 0.06% |
| Region | 2025 Share | 2026–2031 CAGR | Key Drivers |
|---|---|---|---|
| Asia Pacific | 48.25% | 6.52% | China NEV production, GB17675-2025, Japan exports |
| Europe | 22.10% | 5.40% | Premium EV steer-by-wire adoption (Mercedes EQS), Euro NCAP |
| North America | 18.30% | 5.10% | ADAS mandates, commercial vehicle demand |
| South America | 5.60% | 4.80% | Lightweight column demand, cost sensitivity |
| Middle East & Africa | 5.75% | 4.50% | Aftermarket growth, import-dependent OEM supply |
Regional Market Share Tree:
The Asia Pacific dominance is structural, not cyclical. China's GB17675-2025 regulation, effective July 1, 2026, removes the mandatory mechanical steering connection—creating the world's first mass-market legal basis for steer-by-wire. This regulatory first-mover advantage positions Chinese OEMs and their Tier-1 partners to scale steer-by-wire production years ahead of Western competitors, compressing the premium tier into mainstream price bands faster than conventional forecasts assume.
Growth is primarily driven by EPS penetration in ICE and hybrid platforms (+1.8% CAGR impact), steer-by-wire deployment in premium EVs (+1.2%), and demand for ADAS-ready fail-operational architectures (+0.9%). Restraints include rare-earth magnet inflation and mature-node automotive MCU shortages, which squeeze margins and delay production schedules in mainstream EPS programs.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| EPS penetration in ICE/XEV | Driver (+1.8%) | High | Fuel economy gain 3–5%; enables ADAS actuators |
| Steer-by-wire in premium EVs | Driver (+1.2%) | High | Serial production from ZF/Nexteer; GB17675-2025 |
| ADAS-ready fail-operational architectures | Driver (+0.9%) | Medium-High | ASIL-D redundancy; dual-winding motors |
| Cyber-secure ECU mandates | Driver (+0.7%) | Medium | ISO 21434 compliance; Europe/Japan/South Korea |
| Lightweight steering columns | Driver (+0.6%) | Medium | Fuel efficiency and EV range extension |
| OTA-upgradable torque-overlay | Driver (+0.4%) | Low-Medium | Recurring revenue via software updates |
| Rare-earth magnet inflation | Restraint | High | Input cost volatility; supply concentration in China |
| Mature-node MCU tightness | Restraint | High | Extended lead times; production delays |
The balance of drivers outweighs restraints through 2031, but the supply-side constraints are not trivial. Rare-earth magnet inflation and mature-node MCU shortages are structural bottlenecks that disproportionately affect cost-sensitive EPS programs in India, Southeast Asia, and Latin America. Our analysis suggests suppliers with captive magnet sourcing or long-term MCU supply agreements will capture disproportionate margin advantages—a factor that should weigh heavily in vendor selection.
The automotive steering market is moderately concentrated around five Tier-1 suppliers: JTEKT, Robert Bosch, ZF Friedrichshafen, Nexteer Automotive, and NSK. These players control the majority of EPS and steer-by-wire platform awards, with differentiation increasingly driven by software integration and ASIL-D safety capability rather than hardware cost alone.
| Company | Headquarters | Core Strength | Notable 2025–2026 Development |
|---|---|---|---|
| JTEKT Corporation | Japan | EPS scale, Toyota ecosystem | Expanding steer-by-wire capacity in Japan |
| Robert Bosch GmbH | Germany | EPS, ADAS integration, software | Fail-operational EPS for L3 autonomy |
| ZF Friedrichshafen AG | Germany | Steer-by-wire, chassis systems | Series production for NIO ET9 (Feb 2025); Mercedes EQS (Apr 2026); 380k sets/year capacity in Zhangjiagang |
| Nexteer Automotive | USA | High-output C-EPS, steer-by-wire | ASIL-D steer-by-wire production for Chinese NEV OEM (Apr 2026); 110 Nm C-EPS (Apr 2025) |
| NSK Ltd. | Japan | Steering columns, EPS components | Expanding column-assist EPS for crossover EVs |
The competitive moat is shifting from manufacturing scale to software and safety certification. ZF's dual wins with NIO and Mercedes signal that ASIL-D steer-by-wire capability is now a platform-award prerequisite in premium segments. Nexteer's 110 Nm column-assist EPS addresses the torque gap for heavier EVs, but its strategic value lies in extending the C-EPS franchise into entry EV programs—a volume bridge to full steer-by-wire. Our analysis suggests vendors without in-house software or redundant ECU capability will be relegated to component supply, forfeiting system-level margins.
Buyers evaluating steering systems must prioritize fail-operational architecture readiness over upfront hardware cost. ASIL-D certification, dual-winding brushless DC motors, and lockstep processing are no longer premium-only features—they are baseline requirements for any platform targeting L2+ autonomy. Procurement teams should scrutinize supplier roadmaps for steer-by-wire scalability and software update capability, as torque-overlay OTA updates create a path to recurring revenue but require long-term supplier engagement. Regulatory compliance is non-negotiable: GB17675-2025 in China, ISO 21434 for cybersecurity, and Euro NCAP steering-related safety ratings will dictate market access. Switching costs are high—platform awards typically span 5–7 years—so vendor selection decisions made in 2026 will lock in cost structures and technology trajectories through 2032.
The balance of evidence favors a stepwise migration thesis: EPS remains the volume engine through 2030, but steer-by-wire is the value engine. The strongest counter-argument is that cost sensitivity in emerging markets could delay steer-by-wire adoption by 2–3 years, preserving HPS and EHPS demand longer than premium-focused forecasts assume. However, this does not undermine the strategic direction—it merely shifts the timeline for mass-market penetration while premium and Chinese NEV segments accelerate.
Our analysis suggests the most underappreciated risk is software integration capability. As steering systems become software-defined, Tier-1 suppliers without in-house ASIL-D software teams will face platform disqualification. The ZF-NIO-Mercedes wins and Nexteer's ASIL-D production milestone are not isolated events—they are early signals of a structural shift in competitive dynamics that will consolidate market share among software-capable suppliers by 2028.
Actionable Strategy:
What evidence would change our conclusion: A sustained decline in rare-earth magnet prices combined with rapid MCU supply normalization would lower entry barriers, allowing more suppliers to compete on cost and potentially delaying the software-driven consolidation we anticipate.
The balance of evidence favors a stepwise migration thesis: EPS remains the volume engine through 2030, but steer-by-wire is the value engine. The strongest counter-argument is that cost sensitivity in emerging markets could delay steer-by-wire adoption by 2–3 years, preserving HPS and EHPS demand longer than premium-focused forecasts assume. However, this does not undermine the strategic direction—it merely shifts the timeline for mass-market penetration while premium and Chinese NEV segments accelerate.
Our analysis suggests the most underappreciated risk is software integration capability. As steering systems become software-defined, Tier-1 suppliers without in-house ASIL-D software teams will face platform disqualification. The ZF-NIO-Mercedes wins and Nexteer's ASIL-D production milestone are not isolated events—they are early signals of a structural shift in competitive dynamics that will consolidate market share among software-capable suppliers by 2028.
Actionable Strategy:
What evidence would change our conclusion: A sustained decline in rare-earth magnet prices combined with rapid MCU supply normalization would lower entry barriers, allowing more suppliers to compete on cost and potentially delaying the software-driven consolidation we anticipate.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.33% from 2020-2034 |
| Segmentation |
|
The global automotive steering market is valued at USD 36.85 billion in 2026, based on one published estimate. It is projected to reach USD 47.77 billion by 2031, growing at a 5.33% CAGR over the forecast period.
Asia Pacific leads the automotive steering market with 48.25% share in 2025 and is the fastest-growing region at 6.52% CAGR through 2031. China's NEV production and the GB17675-2025 regulation are primary growth catalysts.
Steer-by-wire is the fastest-growing mechanism at 7.95% CAGR through 2031, followed by electric motors at 8.53% CAGR. Commercial vehicles are the fastest-growing vehicle type at 7.28% CAGR, driven by fleet electrification and ADAS adoption.
The major companies operating in this market are JTEKT Corporation, Robert Bosch GmbH, ZF Friedrichshafen AG, Nexteer Automotive Corporation, and NSK Ltd. These Tier-1 suppliers control the majority of EPS and steer-by-wire platform awards.
Key drivers include EPS penetration in ICE and hybrid platforms (+1.8% CAGR impact), steer-by-wire deployment in premium EVs (+1.2%), and demand for ADAS-ready fail-operational architectures (+0.9%). Rare-earth magnet inflation and MCU shortages are the primary restraints.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary research split, ensuring that market estimates are grounded in verified industry input rather than desk-based assumptions. We conducted in-depth interviews with stakeholders across the automotive steering value chain, including Tier-1 system suppliers, electric motor and sensor manufacturers, steering column/rack producers, and global aftermarket distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, providing granular insight into procurement cycles, technology roadmaps, and platform award dynamics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 35% |
| Procurement & Sourcing Leads | 30% |
| Commercial Operations Leads | 20% |
| Regulatory & Quality Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Tier-1 Steering System Suppliers | 40% |
| Component & Motor Manufacturers | 30% |
| OEM Procurement Teams | 20% |
| Aftermarket Distributors | 10% |
We benchmarked our primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards from ISO (including ISO 21434 for automotive cybersecurity) and SAE International. Regulatory frameworks such as UNECE vehicle regulations and NHTSA safety standards were cross-referenced to validate compliance-driven demand assumptions. No competitor market research firms were used in the validation process.
Our market sizing employs simultaneous Top-Down and Bottom-Up triangulation. The Top-Down approach allocates macroeconomic automotive production forecasts by segment, region, and steering mechanism. The Bottom-Up approach models manufacturer capacity, product pricing, and end-use consumption across OEM and aftermarket channels. These dual methodologies converge on a validated market size and forecast series, with discrepancies resolved through primary interview verification.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |