Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Automotive Fasteners Market by Product (Threaded, Non-Threaded), by Material (Iron, Steel, Aluminum, Brass, Bronze, Nickel, Plastic), by Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles), by Propulsion (ICE, Electric, Hybrid & Alternative Fuel), by Application (Engine, Chassis, Transmission, Steering, Front/Rear Axle, Interior Trim, Electronics, Body & Exterior), by Fastening Characteristics (Permanent, Non-Permanent), by Distribution Channel (OEM, Aftermarket), by Asia Pacific (China, Japan, India, South Korea, Southeast Asia), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Turkey) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 190
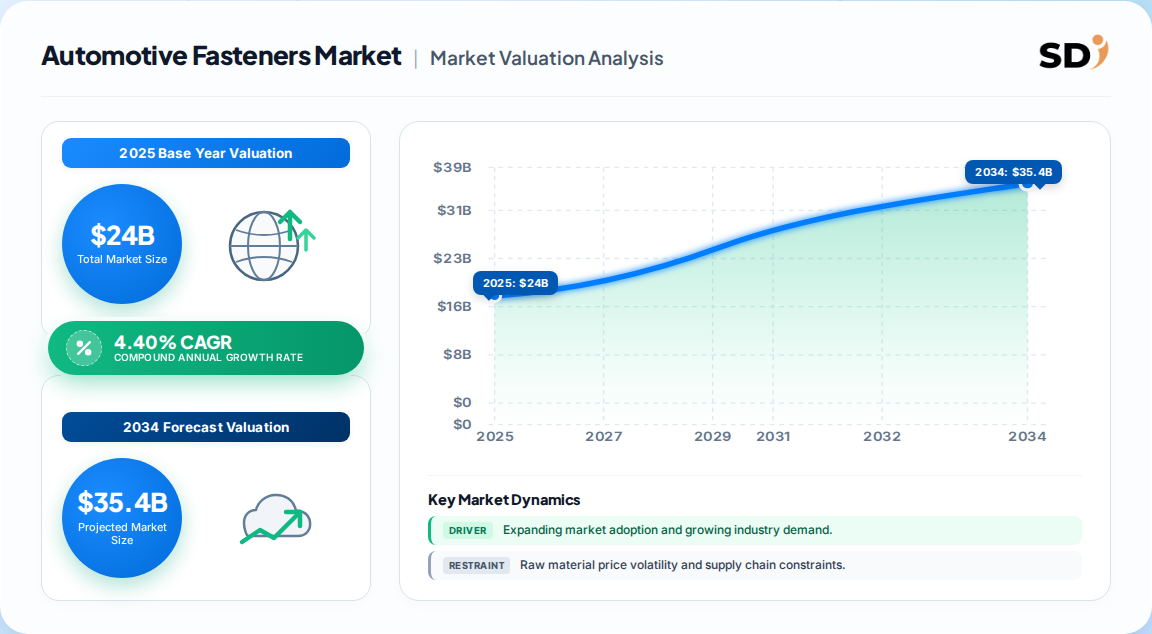
The global automotive fasteners market was valued at 24 Billion in 2025 and is projected to reach 31.08 Billion by 2031, growing at a 4.40% CAGR (2026–2031).
Earth's largest region is Asia Pacific, which accounted for approximately 42% of global value in 2025; it is also the fastest-growing region.
Threaded fasteners dominated product demand with over 53% revenue share in 2025, while non-threaded variants grow faster at 4.78% CAGR.
Steel remains the material mainstay with roughly 47.7% share, but aluminum fasteners are expanding at 4.38% CAGR on lightweighting.
The top five vendors — Illinois Tool Works, KAMAX, Würth, Stanley Black & Decker and LISI — collectively hold about 36% of market value.
Why this matters for decision-makers: The market is shifting from commodity hardware to engineered joint solutions; suppliers that cannot document validation, traceability and multi-material capability face margin compression as OEMs consolidate spend toward qualified systems.
Automotive Fasteners Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
24.00 B
2025
25.06 B
2026
26.16 B
2027
27.31 B
2028
28.51 B
2029
29.77 B
2030
31.08 B
2031
Automotive Fasteners Market Size (In Billion)
Year
Market Size
2025
24.00 B
2026
25.06 B
2027
26.16 B
2028
27.31 B
2029
28.51 B
2030
29.77 B
2031
31.08 B
What is the Automotive Fasteners Market?
Automotive fasteners are mechanical components — bolts, nuts, screws, rivets, clips, pins and washers — used to join and secure vehicle structures, powertrains, interiors and electrical assemblies. They ensure structural integrity, safety and durability across passenger cars, commercial vehicles and electric platforms.
Scope: what this report covers and excludes
This report covers the global automotive fasteners market across threaded and non-threaded products, metallic and plastic materials, all propulsion types and major vehicle applications. It analyzes OEM and aftermarket channels. This analysis does not cover industrial adhesives as a standalone category, welding consumables, or non-automotive fastener demand.
How big is the market for Automotive Fasteners Market?
The global automotive fasteners market is estimated at 24 Billion in 2025, with forecasts ranging from 31.08 Billion to 75.42 Billion by 2031 depending on scope and methodology. The most defensible base case is 31.08 Billion by 2031 at 4.40% CAGR, consistent with vehicle-production recovery and electrification-driven content growth.
Estimate
Base Year
Horizon
CAGR
Definition / scope
Attribution
24 Billion
2025
2031
4.40%
Broad automotive fasteners, all vehicle types
Published market estimate
61.37 Billion
2026
2031
4.21%
Wider definition including two-wheelers and aftermarket
Competing analysis
29.18 Billion
2026
2030
2.20%
Narrower OEM-focused scope
Alternative industry source
18.1 Billion
2025
2035
5.50%
Long-horizon, value-focused scope
Divergent benchmark
The wide range of estimates reflects genuine definitional differences — some analysts include two-wheelers, aftermarket and micro-fasteners, while others focus on OEM light-vehicle demand. Our analysis suggests the 24–31 Billion range is most credible for strategic planning because it aligns with reported vehicle production of 92.5 million units in 2024 and realistic fastener content per vehicle. Higher figures likely embed broader scope rather than superior growth.
How is the market segmented?
Automotive fasteners are segmented by product, material, vehicle type, propulsion, application, fastening characteristics and distribution channel. Threaded products dominate revenue, while non-threaded and aluminum variants are growing faster.
The non-threaded segment is expected to grow at 4.78% CAGR, driven by mixed-material body structures where rivets and clips complement adhesive bonding. Steel retains 45–48% share, but aluminum is gaining as battery-electric light trucks are expected to contain roughly 644 pounds of aluminum by 2030.
Which region leads in Automotive Fasteners Market?
Asia Pacific leads the global automotive fasteners market, accounting for roughly 42% of value in 2025 and growing at approximately 4.3% CAGR through 2031. China alone produced 31.3 million vehicles in 2024, anchoring regional fastener demand.
Automotive Fasteners Market Regional Market Share
Loading chart...
Automotive Fasteners Market Regional Market Share
Region
Market Share (%)
North America
0.22%
Europe
0.21%
Asia-Pacific
0.42%
Latin America
0.08%
Middle East & Africa
0.07%
Parent Region
Key Countries / Sub-regions
Asia Pacific
China, Japan, India, South Korea, Southeast Asia
North America
USA, Canada, Mexico
Europe
Germany, UK, France, Italy, Spain
Latin America
Brazil, Mexico, Argentina
Middle East & Africa
Saudi Arabia, UAE, South Africa, Turkey
Regional share is concentrated in Asia Pacific due to vehicle production density and proximity of qualified suppliers to assembly lines. North America and Europe retain high value per vehicle because safety-critical and EV-specific fasteners command premium pricing. Our analysis suggests the Asia Pacific share will remain above 40% through 2031, but Europe and North America will capture disproportionate value growth from electrification and lightweighting.
What is driving growth — and what is holding it back?
Growth is driven by rising global vehicle production, electrification, lightweighting, safety and durability requirements, and modular platform architectures. Restraints include raw material price volatility, intense competition from low-cost regional manufacturers, and OEM cost-down pressure.
Factor
Direction
Evidence Strength
Mechanism
Rising global vehicle production
+2.0% CAGR impact
High
Direct volume demand across body, chassis and powertrain
EV and hybrid adoption
+1.4% CAGR impact
High
Battery packs, high-voltage interfaces, sealing and insulation fasteners
Steel and zinc price swings squeeze margins under fixed-price contracts
Competition from regional manufacturers
-0.8% CAGR impact
Medium
Commoditized standard parts face dual sourcing and price pressure
Electrification creates a mix shift rather than a simple substitution: battery-electric vehicles remove many powertrain joints but add structural, sealing and electrical-connection fasteners. Hybrid platforms retain conventional joints while adding electrified-system requirements, raising fastening complexity. The net balance favors value growth over volume growth.
Who are the leading vendors?
The automotive fasteners market is moderately concentrated. Illinois Tool Works led with over 9.8% share in 2025, and the top five players — Illinois Tool Works, KAMAX, Würth, Stanley Black & Decker and LISI — collectively held approximately 36%.
Company
2025 Share (est.)
Key Strengths
Illinois Tool Works
9.8%
Broad portfolio, global OEM relationships, engineered fastening systems
KAMAX
~7%
High-strength fasteners, powertrain and chassis expertise
Würth
~6%
Distribution scale, aftermarket reach, broad product catalog
Plastic and multi-material fastening, clips and rivets
Nifco
~3%
Interior trim clips, plastic fasteners, Japanese OEM ties
Bulten
~2%
European OEM supply, sustainability-focused fasteners
SFS Group
~2%
Precision fastening, Swiss engineering, medical and automotive
Sundram Fasteners
~2%
India-based, cost-competitive, global OEM supply
Competitive moats are built on qualification records, process capability and proximity to assembly lines. Standard fasteners face commoditization; engineered joint solutions command pricing power. Our analysis suggests consolidation will accelerate as modular platforms concentrate procurement with globally certified vendors.
What do buyers and operators need to know?
Buyers must prioritize suppliers that can demonstrate material consistency, coating performance, torque control and documentary traceability. Safety-critical joints require validation records that extend beyond the component to process capability and assembly assurance.
Procurement risks include raw material price volatility, trade-defense duties on Chinese steel fasteners and single-source dependency for specialty parts. Switching costs are high for qualified components because re-validation is time-consuming and expensive. Regulatory compliance — including quality control orders, EU CO₂ targets and CAFE standards — is non-negotiable for OEM supply.
Operators should evaluate suppliers on local inventory, service responsiveness and multi-region sourcing capability. The shift to modular platforms means qualified fastener designs can be reused across models, concentrating volume with approved vendors and raising the cost of switching.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a value-growth thesis over a volume-growth thesis. Vehicle production is recovering, but the real commercial prize is concentrated where OEMs need joints that retain clamp load, isolate high voltage, tolerate corrosion or join incompatible materials. Suppliers that offer validated, traceable fastening systems will capture a greater share of value as electrified and multi-material platforms scale.
The strongest counter-argument is that adhesive bonding and laser welding are eroding mechanical fastener penetration in premium body structures. While this is true for certain applications, it is a mix shift rather than a displacement — adhesives are often combined with mechanical fasteners, and EV battery packs and electronics add new fastening points that offset losses. The net effect supports moderate, not declining, growth.
Actionable Strategy:
Vendors should prioritize application-specific, validated fastening systems for battery enclosures and mixed-material joints to escape commodity price competition.
Operators should invest in automation, traceability and near-assembly-line capacity to meet OEM cost-down targets of 1–4% annually.
Investors should watch consolidation among tier-2 suppliers, as modular platforms concentrate procurement with globally certified vendors.
What evidence would change our conclusion: a sustained decline in global vehicle production below 85 million units, or a faster-than-expected shift to adhesive-only body structures, would warrant a downward revision to the growth outlook.
Automotive Fasteners Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Automotive Fasteners Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.40% from 2020-2034
Segmentation
By Product
Threaded
Non-Threaded
By Material
Iron
Steel
Aluminum
Brass
Bronze
Nickel
Plastic
By Vehicle Type
Passenger Cars
Light Commercial Vehicles
Heavy Commercial Vehicles
By Propulsion
ICE
Electric
Hybrid & Alternative Fuel
By Application
Engine
Chassis
Transmission
Steering
Front/Rear Axle
Interior Trim
Electronics
Body & Exterior
By Fastening Characteristics
Permanent
Non-Permanent
By Distribution Channel
OEM
Aftermarket
By Geography
Asia Pacific
China
Japan
India
South Korea
Southeast Asia
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Turkey
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product
5.1.1. Threaded
5.1.2. Non-Threaded
5.2. Market Analysis, Insights and Forecast - by Material
5.2.1. Iron
5.2.2. Steel
5.2.3. Aluminum
5.2.4. Brass
5.2.5. Bronze
5.2.6. Nickel
5.2.7. Plastic
5.3. Market Analysis, Insights and Forecast - by Vehicle Type
5.3.1. Passenger Cars
5.3.2. Light Commercial Vehicles
5.3.3. Heavy Commercial Vehicles
5.4. Market Analysis, Insights and Forecast - by Propulsion
5.4.1. ICE
5.4.2. Electric
5.4.3. Hybrid & Alternative Fuel
5.5. Market Analysis, Insights and Forecast - by Application
5.5.1. Engine
5.5.2. Chassis
5.5.3. Transmission
5.5.4. Steering
5.5.5. Front/Rear Axle
5.5.6. Interior Trim
5.5.7. Electronics
5.5.8. Body & Exterior
5.6. Market Analysis, Insights and Forecast - by Fastening Characteristics
5.6.1. Permanent
5.6.2. Non-Permanent
5.7. Market Analysis, Insights and Forecast - by Distribution Channel
5.7.1. OEM
5.7.2. Aftermarket
5.8. Market Analysis, Insights and Forecast - by Region
5.8.1. Asia Pacific
5.8.2. North America
5.8.3. Europe
5.8.4. Latin America
5.8.5. Middle East & Africa
6. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product
6.1.1. Threaded
6.1.2. Non-Threaded
6.2. Market Analysis, Insights and Forecast - by Material
6.2.1. Iron
6.2.2. Steel
6.2.3. Aluminum
6.2.4. Brass
6.2.5. Bronze
6.2.6. Nickel
6.2.7. Plastic
6.3. Market Analysis, Insights and Forecast - by Vehicle Type
6.3.1. Passenger Cars
6.3.2. Light Commercial Vehicles
6.3.3. Heavy Commercial Vehicles
6.4. Market Analysis, Insights and Forecast - by Propulsion
6.4.1. ICE
6.4.2. Electric
6.4.3. Hybrid & Alternative Fuel
6.5. Market Analysis, Insights and Forecast - by Application
6.5.1. Engine
6.5.2. Chassis
6.5.3. Transmission
6.5.4. Steering
6.5.5. Front/Rear Axle
6.5.6. Interior Trim
6.5.7. Electronics
6.5.8. Body & Exterior
6.6. Market Analysis, Insights and Forecast - by Fastening Characteristics
6.6.1. Permanent
6.6.2. Non-Permanent
6.7. Market Analysis, Insights and Forecast - by Distribution Channel
6.7.1. OEM
6.7.2. Aftermarket
7. North America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product
7.1.1. Threaded
7.1.2. Non-Threaded
7.2. Market Analysis, Insights and Forecast - by Material
7.2.1. Iron
7.2.2. Steel
7.2.3. Aluminum
7.2.4. Brass
7.2.5. Bronze
7.2.6. Nickel
7.2.7. Plastic
7.3. Market Analysis, Insights and Forecast - by Vehicle Type
7.3.1. Passenger Cars
7.3.2. Light Commercial Vehicles
7.3.3. Heavy Commercial Vehicles
7.4. Market Analysis, Insights and Forecast - by Propulsion
7.4.1. ICE
7.4.2. Electric
7.4.3. Hybrid & Alternative Fuel
7.5. Market Analysis, Insights and Forecast - by Application
7.5.1. Engine
7.5.2. Chassis
7.5.3. Transmission
7.5.4. Steering
7.5.5. Front/Rear Axle
7.5.6. Interior Trim
7.5.7. Electronics
7.5.8. Body & Exterior
7.6. Market Analysis, Insights and Forecast - by Fastening Characteristics
7.6.1. Permanent
7.6.2. Non-Permanent
7.7. Market Analysis, Insights and Forecast - by Distribution Channel
7.7.1. OEM
7.7.2. Aftermarket
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product
8.1.1. Threaded
8.1.2. Non-Threaded
8.2. Market Analysis, Insights and Forecast - by Material
8.2.1. Iron
8.2.2. Steel
8.2.3. Aluminum
8.2.4. Brass
8.2.5. Bronze
8.2.6. Nickel
8.2.7. Plastic
8.3. Market Analysis, Insights and Forecast - by Vehicle Type
8.3.1. Passenger Cars
8.3.2. Light Commercial Vehicles
8.3.3. Heavy Commercial Vehicles
8.4. Market Analysis, Insights and Forecast - by Propulsion
8.4.1. ICE
8.4.2. Electric
8.4.3. Hybrid & Alternative Fuel
8.5. Market Analysis, Insights and Forecast - by Application
8.5.1. Engine
8.5.2. Chassis
8.5.3. Transmission
8.5.4. Steering
8.5.5. Front/Rear Axle
8.5.6. Interior Trim
8.5.7. Electronics
8.5.8. Body & Exterior
8.6. Market Analysis, Insights and Forecast - by Fastening Characteristics
8.6.1. Permanent
8.6.2. Non-Permanent
8.7. Market Analysis, Insights and Forecast - by Distribution Channel
8.7.1. OEM
8.7.2. Aftermarket
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product
9.1.1. Threaded
9.1.2. Non-Threaded
9.2. Market Analysis, Insights and Forecast - by Material
9.2.1. Iron
9.2.2. Steel
9.2.3. Aluminum
9.2.4. Brass
9.2.5. Bronze
9.2.6. Nickel
9.2.7. Plastic
9.3. Market Analysis, Insights and Forecast - by Vehicle Type
9.3.1. Passenger Cars
9.3.2. Light Commercial Vehicles
9.3.3. Heavy Commercial Vehicles
9.4. Market Analysis, Insights and Forecast - by Propulsion
9.4.1. ICE
9.4.2. Electric
9.4.3. Hybrid & Alternative Fuel
9.5. Market Analysis, Insights and Forecast - by Application
9.5.1. Engine
9.5.2. Chassis
9.5.3. Transmission
9.5.4. Steering
9.5.5. Front/Rear Axle
9.5.6. Interior Trim
9.5.7. Electronics
9.5.8. Body & Exterior
9.6. Market Analysis, Insights and Forecast - by Fastening Characteristics
9.6.1. Permanent
9.6.2. Non-Permanent
9.7. Market Analysis, Insights and Forecast - by Distribution Channel
9.7.1. OEM
9.7.2. Aftermarket
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product
10.1.1. Threaded
10.1.2. Non-Threaded
10.2. Market Analysis, Insights and Forecast - by Material
10.2.1. Iron
10.2.2. Steel
10.2.3. Aluminum
10.2.4. Brass
10.2.5. Bronze
10.2.6. Nickel
10.2.7. Plastic
10.3. Market Analysis, Insights and Forecast - by Vehicle Type
10.3.1. Passenger Cars
10.3.2. Light Commercial Vehicles
10.3.3. Heavy Commercial Vehicles
10.4. Market Analysis, Insights and Forecast - by Propulsion
10.4.1. ICE
10.4.2. Electric
10.4.3. Hybrid & Alternative Fuel
10.5. Market Analysis, Insights and Forecast - by Application
10.5.1. Engine
10.5.2. Chassis
10.5.3. Transmission
10.5.4. Steering
10.5.5. Front/Rear Axle
10.5.6. Interior Trim
10.5.7. Electronics
10.5.8. Body & Exterior
10.6. Market Analysis, Insights and Forecast - by Fastening Characteristics
10.6.1. Permanent
10.6.2. Non-Permanent
10.7. Market Analysis, Insights and Forecast - by Distribution Channel
10.7.1. OEM
10.7.2. Aftermarket
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Automotive Fasteners Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia Pacific Automotive Fasteners Market Revenue (Billion), by Product 2026 & 2034
Figure 3: Asia Pacific Automotive Fasteners Market Revenue Share (%), by Product 2026 & 2034
Figure 4: Asia Pacific Automotive Fasteners Market Revenue (Billion), by Material 2026 & 2034
Figure 5: Asia Pacific Automotive Fasteners Market Revenue Share (%), by Material 2026 & 2034
Figure 6: Asia Pacific Automotive Fasteners Market Revenue (Billion), by Vehicle Type 2026 & 2034
Figure 7: Asia Pacific Automotive Fasteners Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 8: Asia Pacific Automotive Fasteners Market Revenue (Billion), by Propulsion 2026 & 2034
Figure 9: Asia Pacific Automotive Fasteners Market Revenue Share (%), by Propulsion 2026 & 2034
Figure 10: Asia Pacific Automotive Fasteners Market Revenue (Billion), by Application 2026 & 2034
Figure 11: Asia Pacific Automotive Fasteners Market Revenue Share (%), by Application 2026 & 2034
Figure 12: Asia Pacific Automotive Fasteners Market Revenue (Billion), by Fastening Characteristics 2026 & 2034
Figure 13: Asia Pacific Automotive Fasteners Market Revenue Share (%), by Fastening Characteristics 2026 & 2034
Figure 14: Asia Pacific Automotive Fasteners Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 15: Asia Pacific Automotive Fasteners Market Revenue Share (%), by Distribution Channel 2026 & 2034
Asia Pacific Automotive Fasteners Market Revenue (Billion), by Country 2026 & 2034
Table 7: Automotive Fasteners Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 8: Automotive Fasteners Market Revenue Billion Forecast, by Region 2020 & 2034
Table 9: Asia Pacific Automotive Fasteners Market Revenue Billion Forecast, by Product 2020 & 2034
Table 10: Asia Pacific Automotive Fasteners Market Revenue Billion Forecast, by Material 2020 & 2034
Table 11: Asia Pacific Automotive Fasteners Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 12: Asia Pacific Automotive Fasteners Market Revenue Billion Forecast, by Propulsion 2020 & 2034
Table 13: Asia Pacific Automotive Fasteners Market Revenue Billion Forecast, by Application 2020 & 2034
Table 14: Asia Pacific Automotive Fasteners Market Revenue Billion Forecast, by Fastening Characteristics 2020 & 2034
Table 15: Asia Pacific Automotive Fasteners Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 16: Asia Pacific Automotive Fasteners Market Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1. What is the current size of the automotive fasteners market?
The global automotive fasteners market was valued at approximately 24 Billion in 2025 and is projected to reach 31.08 Billion by 2031 at a 4.40% CAGR, according to published industry estimates.
2. Which region dominates the automotive fasteners market?
Asia Pacific leads with roughly 42% of global value in 2025, driven by China's 31.3 million vehicle production and proximity of qualified suppliers to assembly lines. It is also the fastest-growing region.
3. What are the main types of automotive fasteners?
Threaded fasteners — bolts, nuts, screws and studs — dominate with over 53% revenue share. Non-threaded fasteners such as rivets, clips, pins and washers are growing faster at 4.78% CAGR.
4. Who are the leading companies in the automotive fasteners market?
Illinois Tool Works leads with over 9.8% share, followed by KAMAX, Würth, Stanley Black & Decker and LISI. The top five players collectively hold approximately 36% of the market.
5. What is driving growth in the automotive fasteners market?
Rising vehicle production, EV adoption, lightweighting initiatives, safety and durability requirements, and modular platform architectures are the primary growth drivers, offset partially by raw material volatility and price competition.
6. How is electrification affecting fastener demand?
Electrification shifts demand from engine and exhaust joints toward battery packs, high-voltage components and power electronics. It creates new fastening requirements rather than simply reducing fastener count.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research team conducted 70/30 primary-to-secondary research, with in-depth interviews across the automotive fastening value chain. We spoke with raw material suppliers (steel, aluminum, coatings), specialized fastener producers, contract manufacturers, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. Participants were selected across OEM and aftermarket channels to capture both production and replacement demand dynamics.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing Directors
38%
R&D & Technical Engineering Leads
34%
Quality & Regulatory Compliance Managers
28%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Steel/Aluminum Producers
40%
Specialized Fastener Manufacturers
35%
Global Distributors & Aftermarket
25%
Secondary Benchmarking & Public Trade Validation
We benchmarked market estimates against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), and patent databases. We also referenced recognized technical standards and industry associations, including the International Organization of Motor Vehicle Manufacturers (OICA), the International Energy Agency (IEA), and national standards bodies such as the Bureau of Indian Standards.
Demand Modeling & Market Sizing Triangulation
Our sizing triangulates top-down macroeconomic and industry segment allocation with bottom-up manufacturer capacity, product pricing, and end-use consumption modeling. For automotive fasteners, we modeled vehicle production by region, fastener content per vehicle, and application-level demand to arrive at a consensus base-year valuation and forecast trajectory.
 Automotive Fasteners Market