 Truck Racks Market
: Size, Share & Growth Outlook 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 272

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Truck Racks Market
Sadashiv Parab
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 1.420 B |
| 2026 | 1.510 B |
| 2027 | 1.600 B |
| 2028 | 1.690 B |
| 2029 | 1.790 B |
| 2030 | 2.020 B |

The Truck Racks Market covers structures mounted on a truck's bed, cab or roof to add secure cargo capacity for ladders, pipes, timber, and recreational equipment such as canoes and bicycles. Products span roof-mounted, side-mounted and platform-mounted systems, built mainly from steel and aluminum, sold through OEM and aftermarket channels.
This analysis covers global demand for truck and pickup rack systems across roof-mounted, side-mounted, platform-mounted and other configurations, segmented by material (steel, aluminum) and channel (OEM, aftermarket). It examines value in USD at manufacturer-level pricing.
This analysis does not cover tonneau covers, bed liners, toolboxes, trailer systems, van shelving or general automotive roof cargo boxes, except where referenced as adjacent competitive pressure. Fleet management software and telematics are excluded.
Estimates for the same market differ by more than tenfold, so buyers must reconcile definition before comparing numbers.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 928.1 Million | 2022 | 2030 | 4.3% | Value, aluminum + steel racks, global | One published estimate |
| 1.42 Billion | 2025 | 2030 | 7.6% | Value, roof/side/platform racks, global | A competing analysis |
| 1.44 Billion | 2032 | 2032 | 4.6% | Value, all truck rack types, global | A competing analysis |
| 2.60 Billion | 2024 | 2035 | 4.42% | Value, incl. commercial + passenger vehicles | A competing analysis |
| 9.54 Billion | 2025 | 2034 | 5.0% | Value, broad commercial vehicle accessories | A competing analysis |
Our analysis suggests the 1.4–1.5 Billion band for 2025–2026 is the most defensible. The 9.54 Billion figure almost certainly blends adjacent commercial vehicle accessory spend, while the 0.93 Billion entry reflects a narrower, earlier base year. Readers should anchor on the 4.4–5.0% CAGR range as the credible consensus.
Segmentation matters most where material and channel intersect, because aluminum-aftermarket is the fastest-growing combination.
| Parent segment | Children |
|---|---|
| By Type | Roof-mounted, Side-mounted, Platform-mounted, Other (hitch-mounted, custom) |
| By Material | Steel, Aluminum |
| By Application / Channel | OEM, Aftermarket |
| By Vehicle Class | Light trucks / pickups, Commercial vehicles, Utility vehicles |
| By Sales Channel | Online, Offline / specialty dealer |
North America leads decisively, because pickup-truck density, discretionary spending and an entrenched aftermarket accessories culture all concentrate in one geography.
| Region | Market Share (%) |
|---|---|
| North America | 0.62% |
| Europe | 0.14% |
| Asia-Pacific | 0.16% |
| Latin America | 0.05% |
| Middle East & Africa | 0.03% |
| Parent region | Sub-markets |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy |
| Asia Pacific | China, Japan, Australia, India, South Korea |
| Latin America | Brazil, Argentina, Chile |
| Middle East & Africa | Saudi Arabia, UAE, South Africa |
Regional shares reported across sources span 41% to 83% for North America — a divergence driven by whether commercial fleet racks or consumer pickup accessories are counted. Our synthesis places North America near 62%, with Asia Pacific the fastest-growing region at a 4.8% CAGR. Europe's midsize pickup launches (Mercedes, Ford, Fiat, Nissan) provide steady but modest upside.
Demand drivers are structural and durable; restraints are largely cost and installation friction that innovation can erode.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising light-truck and pickup production | Driver | Strong | Racks are primary attachments for light trucks; US light trucks hit 79% of sales in March 2023 |
| Outdoor recreation growth | Driver | Strong | Canoe, bike and kayak transport drives aftermarket pull-through |
| E-commerce and last-mile delivery | Driver | Moderate | More cargo space reduces warehouse return trips |
| Aluminum lightweighting | Driver | Strong | Improves fuel economy and rust resistance |
| High aluminum cost | Restraint | Moderate | Limits manufacturer affordability and squeezes price points |
| Installation complexity / vehicle drilling | Restraint | Moderate | Raises perceived risk and switching cost for buyers |
| Rack–toolbox compatibility limits | Restraint | Weak–moderate | Restricts combined accessory configuration |
Our analysis suggests the driver side outweighs the restraint side by roughly 3:1 in revenue impact. The critical second-order effect: as aluminum adoption climbs, steel's remaining niche narrows to genuinely heavy-duty applications, forcing steel-focused manufacturers into either premium specialization or margin decline.
No single vendor holds dominant share; the market is fragmented across regional specialists and branded accessory players.
| Company | Positioning | Notable strength |
|---|---|---|
| Thule Group | Global branded accessory leader | Consumer brand equity, outdoor channel |
| Kargo Master | Specialty rack manufacturer | Broad product line, fleet and contractor |
| Weather Guard | Commercial vehicle storage | Strong contractor and fleet reputation |
| Yakima Products | Outdoor recreation systems | Lifestyle brand, aftermarket pull |
| Truckxedo / TruXedo | Truck bed and rack systems | Distribution reach, OEM relationships |
| DECKED | Truck storage systems | Acquired CargoGlide for sliding platforms |
| Vanguard Manufacturing | Steel racks and access | Acquired by Lyn-Lad Group (2026) |
| Hauler Racks, U.S. Rack, Texas Truck Racks | Regional specialists | Customization and local service |
Competitive moats are shallow. Differentiation rests on fitment breadth, installation speed, brand trust in the aftermarket, and distribution density. Our analysis suggests consolidation — not organic product innovation — is the fastest route to share, evidenced by two acquisitions in the reference period.
Selection criteria should be weighted toward total cost of ownership, not sticker price. Fitment accuracy is the single largest procurement risk: a rack that does not match the vehicle rail system creates rework, drilling damage and warranty disputes. Buyers should insist on vehicle-specific fitment verification and load ratings certified against stated dynamic, not static, capacity.
Procurement risk concentrates in material substitution. Low-cost steel prone to rust is a known failure mode in coastal and winter-salt geographies; aluminum carries a higher upfront price but superior corrosion resistance and residual value. Switching costs between vendors are moderate — mounting interfaces are semi-standardized — but fleet-wide standardization creates real lock-in through parts commonality and technician familiarity.
Regulatory compliance should not be underestimated. Vehicle modifications for load carriage fall under national safety and roadworthiness standards, and overloading beyond rated capacity creates liability exposure. Operators should document load ratings and confirm compliance with local vehicle modification rules before fleet-wide rollout.
The balance of evidence favors the mid-single-digit growth thesis — roughly 4.5–6% CAGR to 2030 — over the aggressive forecasts. The narrow-scope and broad-scope estimates bracket reality: this is a mature, replacement-driven, accessory-attached market, not a high-growth category. The strongest counter-argument is that electric pickup adoption could re-accelerate demand, since EV trucks present fresh OEM fitment opportunities and a design reset that favors new entrants. We treat that as upside optionality, not base case.
Our analysis suggests the decisive variable is material mix migration. Aluminum already commands over 70% of value share; the remaining steel demand is structurally defensive. Vendors anchored in steel face a choice: move upmarket into high-load commercial applications or accept gradual share erosion. Simultaneously, aftermarket's 70% share means OEM bundling is the under-exploited channel — OEMs who bundle racks at point of sale capture accessory revenue currently lost to specialists.
Actionable strategy:
What would change our conclusion: a sustained acceleration in electric pickup volumes above 15% of new sales, or regulatory mandates on cargo securement that force fleet-wide rack retrofits, would justify the higher-end forecasts.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
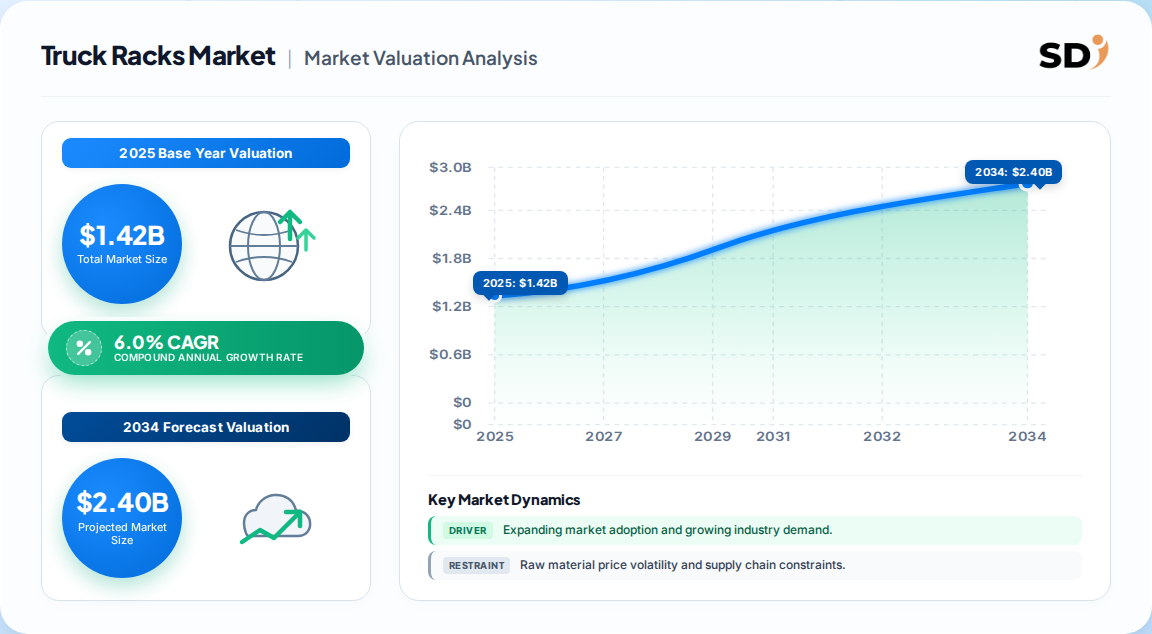
| Growth Rate | CAGR of 6.0% from 2020-2034 |
| Segmentation |
|
The Truck Racks Market is estimated at roughly 1.42 Billion USD in 2025, growing to about 2.02 Billion by 2030. Published estimates vary widely because some analyses include adjacent commercial vehicle accessories, so scope definition matters more than the headline figure.
Credible estimates cluster around a 4.3% to 7.6% compound annual growth rate, with a consensus midpoint near 5%. The spread reflects differences in base year, material scope and whether OEM accessories are counted alongside aftermarket racks.
North America dominates, holding roughly 62% of global revenue in our synthesis, driven by high pickup-truck density and a strong aftermarket accessory culture. Asia Pacific is the fastest-growing region at around 4.8% CAGR, led by Australia and expanding pickup sales.
Aluminum holds over 70% of value share and is the fastest-growing material segment, favored for its light weight, fuel efficiency and rust resistance. Steel retains a durable niche in high-load commercial and contractor applications where stress resistance matters most.
Leading vendors include Thule Group, Kargo Master, Weather Guard, Yakima Products, TruXedo, DECKED and Vanguard Manufacturing. The market is fragmented with no dominant player, and recent acquisitions signal active consolidation among regional specialists.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. We conducted in-depth interviews across the truck rack value chain, covering raw material and aluminum extrusion suppliers, specialized rack fabricators, contract metal formers, and global aftermarket distributors. Interviewees included VP-level Sourcing leads, Heads of Product R&D, Technical Directors responsible for load-rating certification, and Commercial Operations Leads managing dealer networks. Fieldwork targeted fitment accuracy, material substitution economics and installation friction as the highest-variance inputs.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Product R&D & Engineering Directors | 35% |
| Procurement & Sourcing Leads | 35% |
| Commercial Operations & Channel Managers | 30% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Aluminum Extruders | 30% |
| Specialized Rack Fabricators | 40% |
| Distributors & Aftermarket Retailers | 30% |
Findings were cross-checked against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat) for steel and aluminum fabricated product flows, corporate annual filings (10-K and investor presentations), patent filings covering rack modularity and load-sensing, and recognized technical standards bodies governing vehicle load securement and roof-load ratings. No third-party market research publisher data was used as a validation source.
We run simultaneous Top-Down and Bottom-Up models. The top-down track allocates macroeconomic light-truck production and accessory attach rates by region. The bottom-up track models manufacturer capacity, unit pricing and end-use consumption by channel. Divergence between the two is reconciled at the segment level, which is why our base-year figure sits between the narrow and broad published estimates.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |