 Us Automotive Collision Repair Market
US Automotive Collision Repair Market Outlook 2025
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 214

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Automotive Collision Repair Market
Sadashiv Parab
Research Analyst

| Year | Market Size |
|---|---|
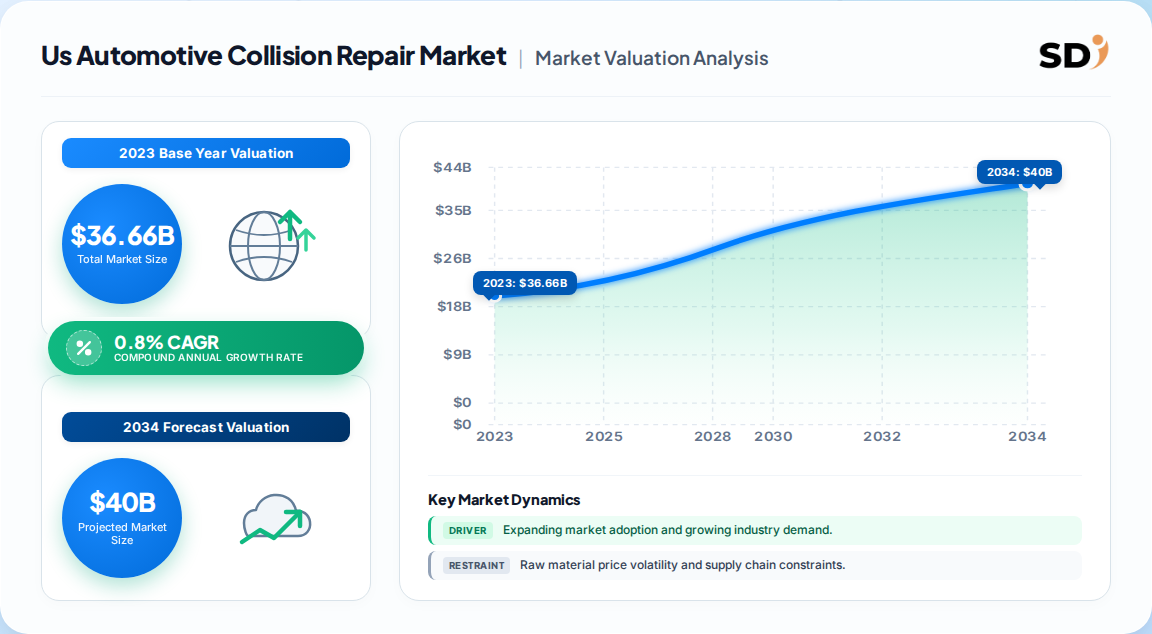
| 2023 | 36.66 B |
| 2024 | 36.95 B |
| 2025 | 37.25 B |
| 2026 | 37.55 B |
| 2027 | 37.85 B |
| 2028 | 38.15 B |
| 2029 | 38.46 B |

The U.S. automotive collision repair market covers revenue from restoring collision-damaged vehicles — structural and cosmetic bodywork, refinishing, glass, parts replacement and increasingly ADAS recalibration — delivered through OEM, MSO, independent and DIY/DIFM channels across light- and heavy-duty segments.
This analysis covers U.S. collision repair revenue across vehicle class (light-duty, heavy-duty), product (spare parts, paints and coatings, consumables) and service channel (DIY, DIFM, OE-handled). It spans structural repair, cosmetic and paint work, glass and ADAS calibration. This analysis does not cover routine mechanical maintenance, tire replacement, used-vehicle remarketing, or new-vehicle manufacturing and OEM parts production economics.
The U.S. market is most defensibly sized at 36.66 Billion (2023) with a low-single-digit CAGR to 2030; regional framings that imply a larger U.S. base typically fold in adjacent services or use later, inflation-adjusted base years.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 36.66 Billion | 2023 | 2030 | 0.8% | U.S. collision repair revenue, all channels | One published estimate |
| ~49.20 Billion (NA total) | 2025 | 2031 | 2.09% | North America, broader product set | A competing analysis |
| ~41.5 Billion (implied U.S.) | 2025 | 2031 | 2.09% | U.S. at ~84.55% of NA value | Derived from competing analysis |
Our analysis suggests the divergence is largely definitional: the higher-growth framing includes ADAS calibration, glass and expanded consumables, plus two additional forecast years of parts inflation. The defensible planning assumption is low-single-digit real growth with mid-single-digit nominal ticket growth — volume is flat-to-declining while average severity rises.
Segmentation follows three axes — vehicle class, product category and service channel — with damage type increasingly tracked as a fourth lens because calibration-heavy work carries premium labor rates.
| Parent | Children |
|---|---|
| By Vehicle | Light-duty vehicle, Heavy-duty vehicle |
| By Product | Spare parts, Paints and coatings, Consumables |
| By Service Channel | DIY, DIFM, OE-handled |
| By Damage Type | Structural repair, Cosmetic and paint, Glass and ADAS calibration |
Light-duty dominance reflects the passenger-car parc; the heavy-duty segment's faster CAGR reflects commercial fleet utilization and multi-axle repair complexity. On products, spare parts lead on volume while paints and coatings lead on value growth. On channels, OE-handled work retains quality-sensitive and warranty-linked customers, but DIFM is where structural growth sits.
No single U.S. region dominates outright: the South carries the largest share of repair revenue on population, vehicle parc and VMT density, while the West shows the strongest calibration-driven ticket growth.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.21% |
| South | 0.34% |
| Midwest | 0.22% |
| West | 0.23% |
| Parent | Children |
|---|---|
| Northeast | New York, Massachusetts, Pennsylvania, New Jersey |
| South | Texas, Florida, Georgia, North Carolina |
| Midwest | Illinois, Ohio, Michigan, Missouri |
| West | California, Arizona, Washington, Colorado |
| Region | Est. share |
|---|---|
| South | 34% |
| West | 23% |
| Midwest | 22% |
| Northeast | 21% |
Our analysis suggests regulation is the real regional differentiator, not raw volume. States mandating OEM-spec recalibration after windshield work — New York and Massachusetts being the clearest examples — effectively raise the technical bar for independent shops, concentrating DRP volume among certified operators in those states.
Growth is driven less by collision frequency — which is softening — than by repair severity, calibration scope and parts inflation, each of which raises revenue per claim even as claim counts moderate.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| ADAS calibration inclusion | Up | High | Adds diagnostic scans and recalibration to repair orders |
| Aging vehicle fleet | Up | High | 6–11 year cohort expands; extends economic repair life |
| PE-backed MSO consolidation | Up | High | Centralized purchasing and back-office scale |
| Mandatory insurance / safety rules | Up | Medium | Sustains insured repair demand and OEM-spec compliance |
| Declining repairable claim frequency | Down | High | Fewer collisions per vehicle mile |
| Technician shortage | Down | High | Constrains throughput and raises labor cost |
| Parts tariffs and inflation | Down | Medium | Compresses independent shop margins |
The balance favors incumbents with scale. Severity-led growth is real but unevenly distributed: certified MSOs capture premium labor rates and DRP volume, while independents face a capital wall for calibration bays and rising parts invoices. Our analysis suggests the single largest second-order effect is network exclusion — shops that defer calibration investment do not merely lose that work, they lose the entire DRP relationship.
The competitive field splits into three tiers: consolidated MSOs with national insurer relationships, OEM-certified networks, and parts-and-coatings suppliers whose economics are tied to repair volume rather than shop ownership.
| Player type | Examples | Moat |
|---|---|---|
| Multi-shop operators | Boyd Group, Crash Champions, Classic Collision, Caliber | Scale purchasing, DRP access, calibration capex |
| Parts and coatings suppliers | 3M, Axalta, PPG, AkzoNobel, BASF | Formulation IP, OEM approvals, distribution reach |
| Component and systems suppliers | ZF, Valeo, Continental, Forvia, Denso | OEM fitment, sensor and ADAS integration |
Differentiation increasingly rests on certification breadth rather than price. OEM-approved repair procedures and calibration tooling are the new switching cost — once a shop invests in licensed diagnostics and trained technicians, changing allegiance is expensive.
Selection criteria have shifted decisively toward verifiable technical capability. Buyers — insurers, fleets and OEM warranty programs — should prioritize documented ADAS calibration competence, OEM procedure compliance and cycle-time performance over headline labor rates, because a missed recalibration creates liability exposure far exceeding the repair invoice.
Procurement risk concentrates in parts. Tariff-driven invoice inflation and counterfeit or non-OEM parts create downstream warranty and safety exposure; contracts should specify OEM or verified equivalent parts, with audit rights. Switching costs are asymmetric: insurers can re-route DRP volume cheaply, but shops cannot cheaply exit a calibration investment, giving carriers negotiating leverage in the near term.
Regulatory compliance is a hard gate, not a differentiator. Low-VOC waterborne coatings under state clean-air rules, plus NHTSA's automatic emergency braking mandate on new light vehicles from September 2029, structurally raise the ADAS-equipped share of the future repairable fleet. Operators who treat compliance as a cost line rather than a capability will find themselves progressively locked out of the insured segment.
The balance of evidence favors severity-led growth over volume-led growth. Flat claim frequency and low-single-digit market CAGR mean revenue expansion comes from richer repair orders — calibration, premium refinish, advanced materials — not from more cars in bays. Anyone modeling this market on collision frequency is modeling the wrong variable.
The strongest counter-argument is that consolidation destroys independent margins fast enough to suppress total market value, as smaller shops exit and capacity tightens. That is plausible locally, but weaker nationally: MSOs backfill capacity and capture the work, so value migrates rather than disappears.
What would change our conclusion: a material rebound in repairable claim frequency, or regulatory reversal on recalibration mandates, would restore volume-led growth and reduce the premium on certification.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 0.8% from 2020-2034 |
| Segmentation |
|
The U.S. automotive collision repair market was valued at 36.66 Billion in 2023 under a widely cited published estimate, projected to grow at a 0.8% CAGR through 2030 as rising repair severity offsets softer claim frequency.
Repairable claim frequency is declining as vehicle safety systems prevent collisions, but average repair severity is rising sharply because ADAS calibration, premium coatings and advanced materials make each repair order more expensive.
The DIFM channel is growing fastest as vehicle complexity, leasing structures and busy consumer lifestyles push owners toward professional repair, while the OE-handled channel retains quality-sensitive and warranty-linked customers.
ADAS calibration adds diagnostic scans and recalibration to repair orders, raising ticket size. Shops without OEM-licensed equipment risk exclusion from insurer direct-repair programs, accelerating consolidation toward certified multi-shop operators.
The largest risk is network exclusion: failing to invest in calibration infrastructure can remove a shop from insurer DRP networks entirely, while parts inflation and tariff costs simultaneously compress margins on the work it retains.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, prioritizing direct industry engagement over published aggregation. We conducted in-depth interviews across the collision repair value chain, including parts and coatings manufacturers, OEM-certified component suppliers, multi-shop operator groups and independent body shop owners, alongside insurer claims and DRP network managers. Interviews targeted decision-makers holding VP of Claims and Network Strategy, Director of Collision Operations, OEM Parts and Procurement Leads, and Technical Compliance Managers. Structured questionnaires captured repair-order economics, calibration capex plans and procurement behavior.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Collision Operations Directors | 35% |
| Procurement & Sourcing Leads | 30% |
| Technical & Compliance Managers | 20% |
| Claims & Network Strategy VPs | 15% |
| Company Type | Representation (%) |
|---|---|
| Parts & Coatings Manufacturers | 40% |
| Multi-Shop Operators & Independents | 35% |
| Insurers & DRP Network Managers | 15% |
| Distributors & Tooling Suppliers | 10% |
Findings were cross-validated against official multilateral and national databases, including UN Comtrade and US ITC trade statistics for automotive parts, Eurostat for coatings and component flows, and NHTSA regulatory filings on safety mandates. Corporate 10-K filings and annual investor presentations from listed collision repair and coatings companies provided revenue and capacity benchmarks. Patent databases and recognized technical standards bodies informed our assessment of ADAS calibration and refinish technology trajectories.
We run simultaneous top-down and bottom-up models. The top-down path allocates macroeconomic vehicle parc, miles traveled and insurance claim data across segments; the bottom-up path models individual shop capacity, repair-order value, parts pricing and end-use consumption. Divergences between the two paths are reconciled through iterative weighting before final forecast publication.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |