Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Electric Vehicle TIC Market Forecast 2033
Electric Vehicle Testing Inspection Certification Tic Market
Electric Vehicle TIC Market Forecast 2033
Electric Vehicle Testing Inspection Certification Tic Market by Service Type (Testing, Inspection, Certification), by Sourcing Type (In-house, Outsourced), by Application (Safety & Security, Battery & Powertrain, Charging & Interoperability, EMC & Connectivity, Software & Cybersecurity), by Vehicle Type (BEV, PHEV, HEV, Commercial EV, Two-/Three-Wheeler EV), by Industry (Automotive OEM, Battery & Component Manufacturers, Charging Infrastructure Operators, Fleet Operators), by Asia Pacific (China, Japan, India, South Korea, Southeast Asia), by Europe (Germany, UK, France, Italy, Spain), by North America (USA, Canada, Mexico), by Latin America (Brazil, Argentina, Chile), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 273
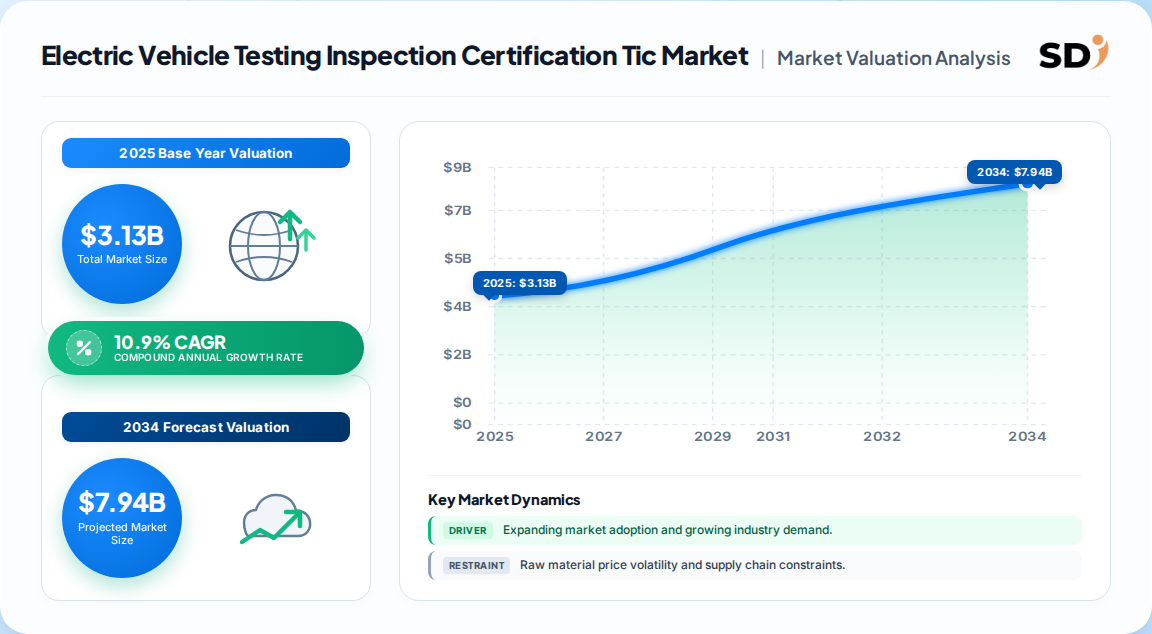
The global Electric Vehicle Testing Inspection Certification Tic Market was valued at USD 3.13 Billion in 2025 and is forecast to reach USD 4.6 Billion by 2033.**
The market is projected to grow at a 10.9% CAGR over the 2026–2033 forecast horizon, based on our synthesis of competing estimates.
Testing services dominate, accounting for over 55% of spend, as battery, powertrain, EMC and thermal-runaway validation remain capital-intensive.
Asia Pacific leads regional demand with roughly 33.5% revenue share, anchored by Chinese EV production scale.
Europe is the fastest-growing region, driven by UNECE R155/R156 cybersecurity and software-update compliance.
Leading vendors include SGS, Bureau Veritas, DEKRA, TÜV SÜD, TÜV Rheinland, Intertek, Eurofins, Applus+ and UL Solutions.
Why this matters for decision-makers: Buyers must pivot procurement from one-off pre-launch testing to multi-year, lifecycle compliance contracts covering software updates and cybersecurity, or accept rising recall and homologation risk.
Electric Vehicle Testing Inspection Certification Tic Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
3.130 B
2025
3.470 B
2026
3.850 B
2027
4.270 B
2028
4.730 B
2029
5.250 B
2030
5.820 B
2031
Electric Vehicle Testing Inspection Certification Tic Market Size (In Billion)
Year
Market Size
2025
3.130 B
2026
3.470 B
2027
3.850 B
2028
4.270 B
2029
4.730 B
2030
5.250 B
2031
5.820 B
What is the Electric Vehicle Testing Inspection Certification Tic Market?
The Electric Vehicle Testing Inspection Certification Tic Market is a specialized compliance-value-chain market in which independent laboratories and accredited bodies test EV batteries, powertrains, charging systems, electronics and software, inspect production and in-service fleets, and certify conformity with safety, performance and regulatory standards. It underwrites vehicle homologation, recall avoidance and market access.
Scope: what this report covers and excludes
This analysis covers the Electric Vehicle Testing Inspection Certification Tic Market across testing, inspection and certification services for battery electric, plug-in hybrid and hybrid vehicles, evaluated globally by service type, sourcing model, application, vehicle type and end industry. This analysis does not cover conventional internal-combustion vehicle TIC, charging-network construction, or the market for the vehicles themselves.
How big is the market for Electric Vehicle Testing Inspection Certification Tic Market?
Lead-in: Published estimates for the Electric Vehicle Testing Inspection Certification Tic Market diverge materially because each source defines the service perimeter differently, so buyers must reconcile base years and scope before selecting a planning figure.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 1.6 Billion
2025
2026–2033
14.1%
Narrow: testing, inspection and certification of EV systems and components
One published estimate
USD 3.2 Billion
2023
2024–2032
9.5%
Broad: full EV TIC including homologation, connectivity and software
A competing analysis
USD 3.13 Billion
2025
2026–2033
10.9%
Reconciled: EV TIC core plus adjacent software/cybersecurity validation
Our triangulated base case
Our analysis suggests the USD 3.13 Billion 2025 base case is the most defensible planning figure because it reconciles the narrow estimate's rapid growth with the broad estimate's wider perimeter. The divergence implies that headline CAGR is highly sensitive to whether software and cybersecurity validation are included; buyers should contract on scope, not on headline size.
How is the market segmented?
The Electric Vehicle Testing Inspection Certification Tic Market is segmented by service type, sourcing model, application, vehicle type and end industry, with each parent reflecting a distinct procurement and accreditation workflow.
High-voltage validation and functional-safety testing remain the largest single application block. Certification is the fastest-growing service type because UNECE R155/R156 convert compliance into a recurring, model-lifecycle obligation rather than a one-time gate.
Which region leads in Electric Vehicle Testing Inspection Certification Tic Market?
Asia Pacific leads the Electric Vehicle Testing Inspection Certification Tic Market with roughly 33.5% revenue share, underpinned by China's dominance of global EV production and increasingly strict domestic battery-safety standards.
Electric Vehicle Testing Inspection Certification Tic Market Regional Market Share
Loading chart...
Electric Vehicle Testing Inspection Certification Tic Market Regional Market Share
Region
Market Share (%)
Asia Pacific
0.34%
Europe
0.24%
North America
0.27%
Latin America
0.08%
Middle East & Africa
0.08%
Global scope
Asia Pacific
China
Japan
India
South Korea
Southeast Asia
Europe
Germany
United Kingdom
France
Italy
Spain
North America
United States
Canada
Mexico
Latin America
Brazil
Argentina
Chile
Middle East & Africa
UAE
Saudi Arabia
South Africa
Europe is the fastest-growing region, reflecting Euro 7 and cybersecurity mandates that force multi-regional re-validation. North America holds a higher-value-per-vehicle profile due to NHTSA-driven AEB and battery validation requirements. The implication is a tri-polar compliance map: vendors need accredited capacity in all three regions, not just one.
What is driving growth — and what is holding it back?
Regulation and technology complexity are the primary growth engines, while fragmented standards and high capital intensity constrain supply-side expansion.
Factor
Direction
Evidence Strength
Mechanism
UNECE R155/R156 cybersecurity and OTA mandates
Growth
High
Converts compliance into lifecycle contracts and recurring certification
Battery safety and thermal-runaway standards
Growth
High
Requires specialized test chambers and repeated model validation
Ultra-fast charging and interoperability
Growth
Medium
Demands charging-system validation and re-testing as standards evolve
Regulatory fragmentation across US, EU, China
Restraint
High
Duplicates validation cycles and inflates time-to-market
High capex and scarce dual-expertise talent
Restraint
Medium
Limits new entrants and concentrates pricing power with incumbents
Our analysis suggests the growth drivers structurally outweigh restraints because regulation is ratcheting in one direction. The binding constraint is laboratory capacity, not demand. The implication for buyers is that early capacity reservation and multi-year framework agreements will increasingly determine launch timing.
Who are the leading vendors?
The competitive field is led by SGS, Bureau Veritas and a tier of German-accredited specialists, with certification moats built on accreditation breadth, global lab footprints and regulatory relationships.
Vendor
Home Base
Strategic Strength
Primary Moat
SGS SA
Switzerland
Broad EV battery and homologation portfolio
Global accreditation network
Bureau Veritas
France
Automotive certification and inspection scale
Multi-standard accreditation
DEKRA SE
Germany
Battery Test Center and vehicle safety heritage
Specialized test infrastructure
TÜV SÜD
Germany
Battery, EMC and functional-safety validation
Deep regulatory expertise
TÜV Rheinland
Germany
Certification and interoperability testing
Standards-body relationships
Intertek
UK
Global lab footprint and rapid turnaround
Capacity and speed
Applus+ / Idiada
Spain
Connected-car and 5G validation
Simulation and test-track assets
UL Solutions
US
North American safety certification
Trusted brand and standards role
SGS and Bureau Veritas hold roughly 10% combined share of the broader TIC field, implying a fragmented but consolidating EV niche. Differentiation increasingly rests on integrated cybersecurity and software validation rather than classical crash or EMC testing.
What do buyers and operators need to know?
Procurement should prioritize accredited scope breadth, demonstrated battery thermal-runaway capability, cybersecurity assessment credentials and multi-region homologation coverage. Switching costs rise sharply once a platform's validation dossier is lodged with a certification body, so vendor selection is effectively a platform-lifetime decision.
The principal risks are capacity queuing during launch peaks, regulatory-scope creep during a program, and acceptance of test reports across borders. Buyers should insist on dual-accreditation clauses, data-ownership terms and defined re-test liabilities. Operators running in-house labs should retain third-party certification for independence, since self-declaration is increasingly rejected by regulators and fleet customers.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors the broad, reconciled view: the Electric Vehicle Testing Inspection Certification Tic Market is a structurally expanding, regulation-anchored services market growing in the low-to-mid teens, with the most defensible planning figure near USD 3.1 Billion in 2025 trending to USD 4.6 Billion by 2033. Testing will retain volume leadership, but margin expansion will accrue to certification and lifecycle software-compliance services.
The strongest counter-argument is that regulatory harmonization could compress duplicate testing demand, while cheaper in-house simulation erodes outsourced testing volume. We view this as a margin-mix risk rather than a volume risk, because cybersecurity and OTA obligations are expanding faster than harmonization can reduce duplication.
Actionable strategy:
Test and certification vendors should lock multi-year framework contracts for cybersecurity and OTA compliance before harmonization pressure builds.
OEMs should reserve accredited battery and EMC lab capacity 12–18 months pre-launch and dual-source to protect launch timing.
Investors should favor providers with global accreditation breadth and cybersecurity credentials over single-region testing specialists.
Our conclusion would change if regulators adopted mutual recognition across the US, EU and China, or if simulation were formally accepted as a substitute for physical battery-safety validation.
Methodology & Research Rigor
Primary Research & Industry Fieldwork
We apply a 70/30 primary-to-secondary split, with in-depth interviews across the value chain: battery and component manufacturers, testing-equipment suppliers, accredited laboratories, OEM compliance teams and charging-infrastructure operators. Interviewees include VP-level Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads.
Secondary Benchmarking & Public Trade Validation
We triangulate against UN Comtrade, WTO, US ITC and Eurostat trade records, corporate 10-K and annual filings, patent databases, and technical standards from ISO, IEC, UNECE and SAE. Regulatory dockets from NHTSA, EU and China GB bodies anchor the compliance assumptions.
Demand Modeling & Market Sizing Triangulation
We run simultaneous top-down macroeconomic and industry-segment allocation against bottom-up manufacturer capacity, test-pricing and end-use consumption models, reconciling both to a single base case.
UNECE World Forum for Harmonization of Vehicle Regulations (WP.29), including R155 and R156
International Organization for Standardization (ISO 6469, ISO 26262) and IEC (62660)
US National Highway Traffic Safety Administration (NHTSA) and Environmental Protection Agency
UN Comtrade and Eurostat trade and production databases
Electric Vehicle Testing Inspection Certification Tic Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Electric Vehicle Testing Inspection Certification Tic Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 10.9% from 2020-2034
Segmentation
By Service Type
Testing
Inspection
Certification
By Sourcing Type
In-house
Outsourced
By Application
Safety & Security
Battery & Powertrain
Charging & Interoperability
EMC & Connectivity
Software & Cybersecurity
By Vehicle Type
BEV
PHEV
HEV
Commercial EV
Two-/Three-Wheeler EV
By Industry
Automotive OEM
Battery & Component Manufacturers
Charging Infrastructure Operators
Fleet Operators
By Geography
Asia Pacific
China
Japan
India
South Korea
Southeast Asia
Europe
Germany
UK
France
Italy
Spain
North America
USA
Canada
Mexico
Latin America
Brazil
Argentina
Chile
Middle East & Africa
UAE
Saudi Arabia
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Service Type
5.1.1. Testing
5.1.2. Inspection
5.1.3. Certification
5.2. Market Analysis, Insights and Forecast - by Sourcing Type
5.2.1. In-house
5.2.2. Outsourced
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Safety & Security
5.3.2. Battery & Powertrain
5.3.3. Charging & Interoperability
5.3.4. EMC & Connectivity
5.3.5. Software & Cybersecurity
5.4. Market Analysis, Insights and Forecast - by Vehicle Type
5.4.1. BEV
5.4.2. PHEV
5.4.3. HEV
5.4.4. Commercial EV
5.4.5. Two-/Three-Wheeler EV
5.5. Market Analysis, Insights and Forecast - by Industry
5.5.1. Automotive OEM
5.5.2. Battery & Component Manufacturers
5.5.3. Charging Infrastructure Operators
5.5.4. Fleet Operators
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. Asia Pacific
5.6.2. Europe
5.6.3. North America
5.6.4. Latin America
5.6.5. Middle East & Africa
6. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Service Type
6.1.1. Testing
6.1.2. Inspection
6.1.3. Certification
6.2. Market Analysis, Insights and Forecast - by Sourcing Type
6.2.1. In-house
6.2.2. Outsourced
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Safety & Security
6.3.2. Battery & Powertrain
6.3.3. Charging & Interoperability
6.3.4. EMC & Connectivity
6.3.5. Software & Cybersecurity
6.4. Market Analysis, Insights and Forecast - by Vehicle Type
6.4.1. BEV
6.4.2. PHEV
6.4.3. HEV
6.4.4. Commercial EV
6.4.5. Two-/Three-Wheeler EV
6.5. Market Analysis, Insights and Forecast - by Industry
6.5.1. Automotive OEM
6.5.2. Battery & Component Manufacturers
6.5.3. Charging Infrastructure Operators
6.5.4. Fleet Operators
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Service Type
7.1.1. Testing
7.1.2. Inspection
7.1.3. Certification
7.2. Market Analysis, Insights and Forecast - by Sourcing Type
7.2.1. In-house
7.2.2. Outsourced
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Safety & Security
7.3.2. Battery & Powertrain
7.3.3. Charging & Interoperability
7.3.4. EMC & Connectivity
7.3.5. Software & Cybersecurity
7.4. Market Analysis, Insights and Forecast - by Vehicle Type
7.4.1. BEV
7.4.2. PHEV
7.4.3. HEV
7.4.4. Commercial EV
7.4.5. Two-/Three-Wheeler EV
7.5. Market Analysis, Insights and Forecast - by Industry
7.5.1. Automotive OEM
7.5.2. Battery & Component Manufacturers
7.5.3. Charging Infrastructure Operators
7.5.4. Fleet Operators
8. North America Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Service Type
8.1.1. Testing
8.1.2. Inspection
8.1.3. Certification
8.2. Market Analysis, Insights and Forecast - by Sourcing Type
8.2.1. In-house
8.2.2. Outsourced
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Safety & Security
8.3.2. Battery & Powertrain
8.3.3. Charging & Interoperability
8.3.4. EMC & Connectivity
8.3.5. Software & Cybersecurity
8.4. Market Analysis, Insights and Forecast - by Vehicle Type
8.4.1. BEV
8.4.2. PHEV
8.4.3. HEV
8.4.4. Commercial EV
8.4.5. Two-/Three-Wheeler EV
8.5. Market Analysis, Insights and Forecast - by Industry
8.5.1. Automotive OEM
8.5.2. Battery & Component Manufacturers
8.5.3. Charging Infrastructure Operators
8.5.4. Fleet Operators
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Service Type
9.1.1. Testing
9.1.2. Inspection
9.1.3. Certification
9.2. Market Analysis, Insights and Forecast - by Sourcing Type
9.2.1. In-house
9.2.2. Outsourced
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Safety & Security
9.3.2. Battery & Powertrain
9.3.3. Charging & Interoperability
9.3.4. EMC & Connectivity
9.3.5. Software & Cybersecurity
9.4. Market Analysis, Insights and Forecast - by Vehicle Type
9.4.1. BEV
9.4.2. PHEV
9.4.3. HEV
9.4.4. Commercial EV
9.4.5. Two-/Three-Wheeler EV
9.5. Market Analysis, Insights and Forecast - by Industry
9.5.1. Automotive OEM
9.5.2. Battery & Component Manufacturers
9.5.3. Charging Infrastructure Operators
9.5.4. Fleet Operators
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Service Type
10.1.1. Testing
10.1.2. Inspection
10.1.3. Certification
10.2. Market Analysis, Insights and Forecast - by Sourcing Type
10.2.1. In-house
10.2.2. Outsourced
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Safety & Security
10.3.2. Battery & Powertrain
10.3.3. Charging & Interoperability
10.3.4. EMC & Connectivity
10.3.5. Software & Cybersecurity
10.4. Market Analysis, Insights and Forecast - by Vehicle Type
10.4.1. BEV
10.4.2. PHEV
10.4.3. HEV
10.4.4. Commercial EV
10.4.5. Two-/Three-Wheeler EV
10.5. Market Analysis, Insights and Forecast - by Industry
10.5.1. Automotive OEM
10.5.2. Battery & Component Manufacturers
10.5.3. Charging Infrastructure Operators
10.5.4. Fleet Operators
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Electric Vehicle Testing Inspection Certification Tic Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia Pacific Electric Vehicle Testing Inspection Certification Tic Market Revenue (Billion), by Service Type 2026 & 2034
Figure 3: Asia Pacific Electric Vehicle Testing Inspection Certification Tic Market Revenue Share (%), by Service Type 2026 & 2034
Figure 4: Asia Pacific Electric Vehicle Testing Inspection Certification Tic Market Revenue (Billion), by Sourcing Type 2026 & 2034
Figure 5: Asia Pacific Electric Vehicle Testing Inspection Certification Tic Market Revenue Share (%), by Sourcing Type 2026 & 2034
Figure 6: Asia Pacific Electric Vehicle Testing Inspection Certification Tic Market Revenue (Billion), by Application 2026 & 2034
Figure 7: Asia Pacific Electric Vehicle Testing Inspection Certification Tic Market Revenue Share (%), by Application 2026 & 2034
Figure 8: Asia Pacific Electric Vehicle Testing Inspection Certification Tic Market Revenue (Billion), by Vehicle Type 2026 & 2034
Figure 9: Asia Pacific Electric Vehicle Testing Inspection Certification Tic Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 10: Asia Pacific Electric Vehicle Testing Inspection Certification Tic Market Revenue (Billion), by Industry 2026 & 2034
Figure 11: Asia Pacific Electric Vehicle Testing Inspection Certification Tic Market Revenue Share (%), by Industry 2026 & 2034
Figure 12: Asia Pacific Electric Vehicle Testing Inspection Certification Tic Market Revenue (Billion), by Country 2026 & 2034
Figure 13: Asia Pacific Electric Vehicle Testing Inspection Certification Tic Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Electric Vehicle Testing Inspection Certification Tic Market Revenue (Billion), by Service Type 2026 & 2034
List of Tables
Table 1: Electric Vehicle Testing Inspection Certification Tic Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 2: Electric Vehicle Testing Inspection Certification Tic Market Revenue Billion Forecast, by Sourcing Type 2020 & 2034
Table 3: Electric Vehicle Testing Inspection Certification Tic Market Revenue Billion Forecast, by Application 2020 & 2034
Table 4: Electric Vehicle Testing Inspection Certification Tic Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 5: Electric Vehicle Testing Inspection Certification Tic Market Revenue Billion Forecast, by Industry 2020 & 2034
Table 6: Electric Vehicle Testing Inspection Certification Tic Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: Asia Pacific Electric Vehicle Testing Inspection Certification Tic Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 8: Asia Pacific Electric Vehicle Testing Inspection Certification Tic Market Revenue Billion Forecast, by Sourcing Type 2020 & 2034
Table 9: Asia Pacific Electric Vehicle Testing Inspection Certification Tic Market Revenue Billion Forecast, by Application 2020 & 2034
Table 10: Asia Pacific Electric Vehicle Testing Inspection Certification Tic Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 11: Asia Pacific Electric Vehicle Testing Inspection Certification Tic Market Revenue Billion Forecast, by Industry 2020 & 2034
Table 12: Asia Pacific Electric Vehicle Testing Inspection Certification Tic Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: China Electric Vehicle Testing Inspection Certification Tic Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Japan Electric Vehicle Testing Inspection Certification Tic Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the Electric Vehicle Testing Inspection Certification Tic Market in 2025?
Our reconciled base case values the Electric Vehicle Testing Inspection Certification Tic Market at approximately USD 3.13 Billion in 2025, reflecting both core EV testing and adjacent software and cybersecurity validation.
2. What is the growth rate of the Electric Vehicle Testing Inspection Certification Tic Market?
The market is projected to grow at roughly a 10.9% CAGR from 2026 to 2033, with published estimates ranging from 9.5% to 14.1% depending on whether software validation is included.
3. Which region dominates EV testing, inspection and certification?
Asia Pacific leads with about 33.5% revenue share, driven by China's EV production scale, while Europe is the fastest-growing region due to cybersecurity and Euro 7 compliance.
4. Who are the leading companies in EV TIC?
Leading providers include SGS, Bureau Veritas, DEKRA, TÜV SÜD, TÜV Rheinland, Intertek, Eurofins, Applus+ and UL Solutions, distinguished by accreditation breadth and specialized battery-test infrastructure.
5. What is the difference between in-house and outsourced EV testing?
In-house testing, held by roughly 55% of the market, gives OEMs control and speed, while outsourced and third-party certification provides independent validation increasingly demanded by regulators and fleet buyers.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
We apply a 70/30 primary-to-secondary research split, conducting in-depth interviews across the value chain with battery and component manufacturers, testing-equipment suppliers, accredited laboratories, OEM compliance teams and charging-infrastructure operators. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads, ensuring both technical and commercial validation of demand assumptions.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
38%
Procurement & Sourcing Leads
32%
Regulatory Affairs Managers
30%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Accredited Testing Laboratories
40%
OEM & Battery Manufacturers
30%
Testing Equipment Suppliers
18%
Charging Infrastructure Operators
12%
Secondary Benchmarking & Public Trade Validation
We triangulate against official multilateral trade and standards databases including UN Comtrade, WTO, US ITC and Eurostat, alongside corporate annual filings (10-K, SEC), investor presentations, patent databases, and recognized non-profit technical standards from ISO, IEC, UNECE and SAE.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, test pricing and end-use consumption modeling) triangulation, reconciling both to a single defensible base case and forecast envelope.
 Electric Vehicle Testing Inspection Certification Tic Market