 China Electric Vehicle Testing Inspection Certification Tic Market
China EV Testing Inspection Certification TIC Market 2025
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 268

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 China Electric Vehicle Testing Inspection Certification Tic Market
Sadashiv Parab
Research Analyst
| Year | Market Size |
|---|---|
| 2023 | 136.0 M |
| 2024 | 155.0 M |
| 2025 | 177.0 M |
| 2026 | 203.0 M |
| 2027 | 232.0 M |
| 2028 | 265.0 M |
| 2029 | 303.0 M |

The China EV TIC market encompasses third-party and in-house testing, inspection, and certification services that validate electric vehicle safety, performance, and regulatory compliance. It covers battery abuse testing, EMC validation, charging interoperability, and type approval for domestic and export markets, serving OEMs, battery makers, and component suppliers across the EV value chain.
This analysis covers testing, inspection, and certification services for battery electric vehicles (BEVs), plug-in hybrids (PHEVs), and fuel-cell vehicles (FCEVs) across automotive, aerospace, and defense applications in China. It includes in-house and outsourced sourcing models. This analysis does not cover conventional internal combustion engine vehicle TIC services, charging-network construction, or non-automotive industrial testing.
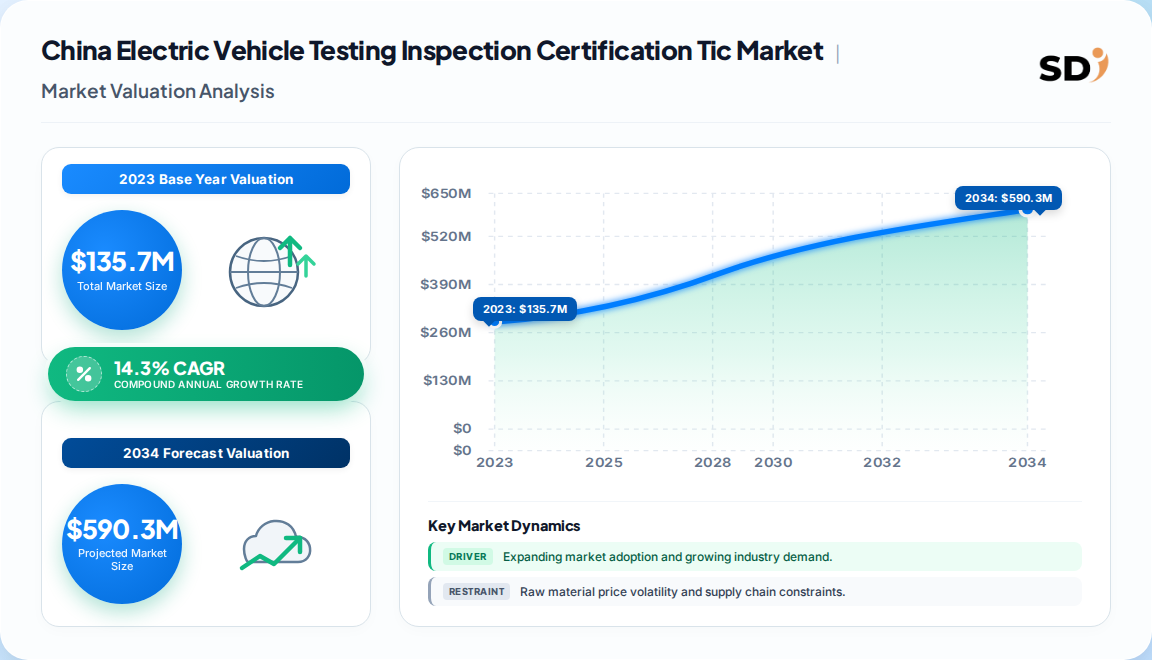
The most defensible estimate places China's EV TIC market at 135.7 Million in 2023, growing to 345.5 Million by 2030 at 14.3% CAGR. This aligns with China's 11.2% share of the global EV TIC market and reflects the country's dominance in global battery production and EV exports.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 135.7 Million | 2023 | 2030 | 14.3% | China EV TIC, service-type segmentation | One published estimate |
| 530 Million | 2025 | 2030 | 15.4% | China EV TIC, broader scope incl. adjacent services | A competing analysis |
| 1.56 Billion | 2025 | 2033 | 14.1% | China EV TIC, expanded definition incl. charging infrastructure | Alternative industry source |
The 135.7 Million figure is most defensible because it strictly scopes automotive EV TIC services and aligns with China's 11.2% share of the 1.2 Billion global market. The higher estimates likely bundle adjacent services such as charging infrastructure inspection and non-automotive testing, inflating the addressable market.
Service type is the primary segmentation, with testing commanding 72.8% of 2023 revenue. Certification is the fastest-growing segment, while inspection remains a smaller but recurrent revenue stream tied to charging infrastructure and component audits.
| Parent Segment | Children |
|---|---|
| Service Type | Testing, Inspection, Certification |
| Sourcing Type | In-House, Outsourced |
| Application | Safety & Security, Connectors, Communication, EV Charging |
| Vehicle Type | BEV, PHEV, FCEV, Others |
| Industry | Automotive, Aerospace, Defense, Others |
Battery testing alone represents roughly 40% of testing revenue, driven by GB 38031 thermal propagation requirements and UN R100 compliance. The China BEV Testing Market dominates vehicle-type demand, reflecting BEVs' 75%+ share of NEV sales.
Eastern China leads the China EV TIC market, accounting for approximately 34% of national revenue in 2023. The Yangtze River Delta cluster hosts major OEMs, battery manufacturers, and CNAS-accredited laboratories, creating concentrated demand for testing and certification services.
| Region | Market Share (%) |
|---|---|
| Northern China | 0.28% |
| Eastern China | 0.34% |
| Central China | 0.16% |
| Southern China | 0.14% |
| Western China | 0.08% |
| Parent Region | Sub-Regions | Est. Share |
|---|---|---|
| Eastern China | Shanghai, Jiangsu, Zhejiang, Anhui | 34% |
| Northern China | Beijing, Tianjin, Hebei | 28% |
| Central China | Hubei, Hunan, Henan | 16% |
| Southern China | Guangdong, Fujian | 14% |
| Western China | Sichuan, Chongqing, Shaanxi | 8% |
Eastern China's dominance is reinforced by the presence of SAIC, Tesla's Shanghai gigafactory, and CATL's battery facilities, which generate dense demand for battery abuse testing and EMC validation. Northern China follows closely, anchored by Beijing's regulatory bodies and BAIC's manufacturing base.
Battery safety mandates and export homologation are the strongest growth drivers, with high impact through 2027. Price-based procurement and domestic lab overcapacity are the primary restraints, concentrated in low-value testing segments.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| GB 38031 battery safety standard | Driver | High | Mandates thermal propagation and abuse testing for all EV batteries |
| EV export growth (EU type approval) | Driver | High | Requires certification to UN R100 and EU Battery Regulation |
| Charging infrastructure expansion (8M+ ports) | Driver | High | Creates recurring inspection and interoperability certification demand |
| 800V platforms and solid-state battery R&D | Driver | Medium | Drives new test protocols for high-voltage components |
| Price-based procurement and domestic lab overcapacity | Restraint | High | Domestic labs quote 20–30% below international TIC firms |
| Shortage of certified battery abuse-testing engineers | Restraint | Medium | Limits lab capacity expansion and extends turnaround times |
| Regulatory divergence (China, EU, U.S.) | Restraint | Medium | Forces duplicate testing, raising costs for OEMs |
Our analysis suggests the driver-restraint balance favors growth through 2027, with high-impact drivers outnumbering restraints. However, margin pressure in basic component testing is intensifying, and labs without EMC and abuse-testing capabilities will face consolidation pressure.
SGS, TÜV SÜD, and Bureau Veritas lead the China EV TIC market through global accreditation, battery testing expertise, and export homologation capabilities. Domestic labs compete on cost and turnaround but lack international recognition for export certification.
| Company | Core Strength | Target Audience | Market Position |
|---|---|---|---|
| SGS | Global accreditation, battery and EMC testing | OEMs, battery makers, exporters | Leader |
| TÜV SÜD | Homologation, battery abuse testing | OEMs, Tier 1 suppliers | Leader |
| Bureau Veritas | Certification, regulatory compliance | Exporters, multinational OEMs | Strong |
| Intertek | EMC testing, charging interoperability | Charging operators, component makers | Strong |
| TÜV Rheinland | Type approval, functional safety | Automotive OEMs | Strong |
| Domestic CNAS labs | Cost advantage, local turnaround | Domestic OEMs, Tier 2 suppliers | Emerging |
International TIC firms command premium pricing for export certification due to their recognition by EU and U.S. regulators. Domestic labs are gaining share in routine component testing but face accreditation bottlenecks, with CNAS and CMA approvals taking 18–24 months for new battery abuse labs.
Buyers must prioritize labs with CNAS accreditation and UN R100 recognition for export certification, as these credentials directly affect market access. Procurement risks include capacity constraints at accredited battery abuse labs, where turnaround times can extend by 30–40% during peak demand periods.
Switching costs are high for OEMs that have integrated TIC providers into their product development cycles, particularly for battery testing where test data continuity matters. Regulatory compliance is non-negotiable: GB 38031 thermal propagation tests and EU Battery Regulation carbon-footprint declarations require specialized lab capabilities that only a handful of providers offer.
Operators should evaluate TIC partners on three dimensions: accreditation scope (CNAS, CMA, UN R100), battery abuse-testing capacity, and digital test data platforms that enable continuous compliance monitoring. The shift from one-time homologation to lifecycle compliance testing means buyers should prioritize providers offering recurring revenue models.
The balance of evidence favors certification and battery abuse testing as the highest-value growth corridors in China's EV TIC market. Testing dominates revenue today, but certification carries higher margins due to liability and regulatory sign-off, and export homologation demand is accelerating as Chinese OEMs target European markets. Our analysis suggests certification will outpace vehicle-level inspection through 2030.
The strongest counter-argument is that domestic lab overcapacity could compress certification margins as well, particularly for routine EU type approval where Chinese labs are building capability. However, the accreditation bottleneck (18–24 months for battery abuse labs) and the complexity of EU Battery Regulation compliance create durable barriers that favor incumbents with established recognition.
Actionable Strategy:
The evidence that would change our conclusion: a rapid expansion of CNAS-accredited battery abuse labs (reducing the accreditation bottleneck) combined with EU regulatory harmonization with Chinese standards would erode the premium currently commanded by international TIC firms.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 14.3% from 2020-2034 |
| Segmentation |
|
The China EV TIC market was valued at 135.7 Million in 2023 and is projected to reach 345.5 Million by 2030, growing at a 14.3% CAGR. Testing accounted for 72.8% of revenue, with certification the fastest-growing segment.
GB 38031 battery safety standards, EV export growth requiring EU type approval and FMVSS compliance, and charging infrastructure expansion beyond 8 million ports are the primary drivers. Each new EV platform requires battery, EMC, e-motor, and charging validation.
SGS, TÜV SÜD, Bureau Veritas, Intertek, and TÜV Rheinland lead through global accreditation and export homologation capabilities. Domestic CNAS-accredited labs compete on cost and turnaround but lack international recognition for export certification.
Eastern China leads with approximately 34% of national revenue, anchored by the Yangtze River Delta cluster of OEMs, battery manufacturers, and CNAS-accredited laboratories. Shanghai, Jiangsu, and Zhejiang host the densest concentration of testing demand.
Price-based procurement and domestic lab overcapacity compress margins, with domestic labs quoting 20–30% below international firms. A shortage of certified battery abuse-testing engineers and regulatory divergence between China, EU, and U.S. standards add cost and complexity.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology triangulates primary industry fieldwork with secondary trade and standards validation to produce decision-ready market intelligence for the China EV TIC sector.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Quality & Homologation Heads | 35% |
| Technical Directors & Lab Managers | 30% |
| Procurement & Sourcing Leads | 22% |
| Regulatory Affairs Managers | 13% |
| Company Type | Representation (%) |
|---|---|
| Battery Manufacturers & Suppliers | 30% |
| Automotive OEMs & Tier 1 Suppliers | 28% |
| Accredited Testing Laboratories | 24% |
| Certification Bodies & Regulators | 18% |
We maintain a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the EV TIC value chain, including battery manufacturers, automotive OEMs, Tier 1 component suppliers, accredited testing laboratories, and certification bodies. Decision-maker designations interviewed include VP of Quality, Head of Homologation, Technical Directors, and Commercial Operations Leads. Structured questionnaires captured capacity, pricing, accreditation status, and service-level expectations.
We validate primary findings against official multilateral trade databases (UN Comtrade, WTO), corporate filings (10-K, annual investor presentations), patent databases, and recognized technical standards bodies including ISO, UNECE (UN R100), and SAE International. Chinese regulatory sources including MIIT, SAMR, and CNAS accreditation records are incorporated where publicly available.
Simultaneous top-down and bottom-up triangulation is applied. The top-down model allocates macroeconomic and industry segment data to EV TIC service categories. The bottom-up model builds from manufacturer capacity, test-line utilization, pricing schedules, and end-use consumption patterns across OEMs and battery makers.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
