Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Automotive Differential System Market Outlook 2026
Automotive Differential System Market Outlook 2026
Automotive Differential System Market
Automotive Differential System Market Outlook 2026
Automotive Differential System Market by Type (Open Differential, Limited Slip Differential, Locking Differential, Electronic Limited Slip Differential, Torque Vectoring Differential), by Drive Type (FWD, RWD, AWD/4WD, 2WD), by Component (Differential Gear, Differential Case, Differential Bearing, Seals & Gaskets, Control Modules), by Vehicle Type (Passenger Car, SUV/Crossover, Light Commercial Vehicle, Heavy Truck, Bus, Off-Highway Vehicle), by Propulsion (ICE, Hybrid, Battery Electric), by Sales Channel (OEM, Aftermarket), by Asia Pacific (China, India, Japan, South Korea, ASEAN), by Europe (Germany, UK, France, Italy, Spain, Nordics), by North America (USA, Canada, Mexico), by Latin America (Brazil, Mexico, Argentina, Colombia), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 224
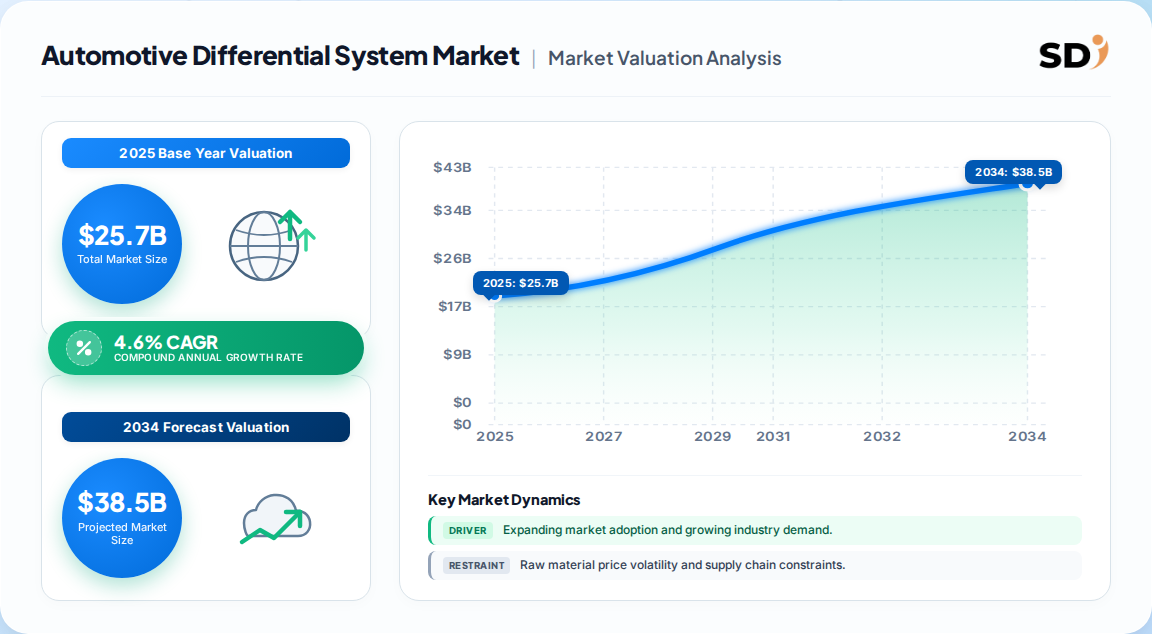
USD 25.7 Billion in 2025 revenue, global scope, across OEM and replacement channels for mechanical and electronic differential systems.
Forecast expansion to USD 40.2 Billion by 2035, a 4.6% CAGR (2026–2035), driven by AWD content-per-vehicle and e-Axle architecture.
Open differential remains the largest type at ~34.5% share; torque vectoring is the fastest-growing sub-type at ~8.2% CAGR.
Asia-Pacific leads with roughly 43% of global revenue, followed by Europe (~24%) and North America (~20%).
FWD is the largest drive configuration (~42.5%), but AWD/4WD is the fastest-growing as SUVs exceed 47% of global sales.
Top five suppliers — ZF, American Axle, Dana, BorgWarner, GKN — held a combined 20.3% share in 2025, confirming a fragmented, qualification-gated market.
Why this matters for decision-makers: Differential value is migrating from machined hardware to controls-integrated torque management, so suppliers without software and functional-safety capability face structural margin compression by 2030.
Automotive Differential System Market Size (In Billion)
30.0B
20.0B
10.0B
0
22.79 B
2022
23.66 B
2023
24.62 B
2024
25.70 B
2025
26.80 B
2026
28.00 B
2027
29.30 B
2028
Automotive Differential System Market Size (In Billion)
Year
Market Size
2022
22.79 B
2023
23.66 B
2024
24.62 B
2025
25.70 B
2026
26.80 B
2027
28.00 B
2028
29.30 B
What is the Automotive Differential System Market?
The automotive differential system market covers the design, manufacture and sale of gear assemblies, housings, bearings, seals and electronic control modules that let driven wheels rotate at different speeds while transmitting torque. It spans open, limited-slip, locking, electronic limited-slip and torque-vectoring units for ICE, hybrid and battery-electric vehicles.
Scope: what this report covers and excludes
This analysis covers OEM and aftermarket differential systems across passenger cars, light and heavy commercial vehicles, buses and off-highway equipment, segmented by type, drive configuration, component, propulsion and region, from 2022 through 2035 with 2025 as the base year. This analysis does not cover transfer cases as standalone products, complete e-Axle assemblies sold as prime-mover units, or transmission gear sets outside the differential housing.
How big is the market for Automotive Differential System Market?
Published estimates converge on a USD 25–26 Billion 2025 base and a mid-single-digit compound growth path, but the spread between a USD 36 Billion and a USD 40 Billion 2035 endpoint reveals genuinely different assumptions about EV content.
Includes e-Axle-integrated and torque-management modules
A competing analysis
USD 3.4 Million
2025
2035 (USD 5.7 Million)
5.3%
Narrow electronic-differential sub-scope only
A third published estimate
USD 22.6 Billion
2024
2035 (USD 36.4 Billion)
4.41%
Broad differential systems, all propulsion
A fourth published estimate
Our analysis suggests the USD 25.7 Billion / USD 40.2 Billion framing is the most defensible because it explicitly captures e-Axle-integrated differentials and axle-disconnect modules, which are the fastest-appreciating content blocks. The USD 23.9 Billion baseline is credible but likely under-counts battery-electric driveline integration. The USD 3.4 Million figure is a scoping outlier and should not be used for capital allocation.
How is the market segmented?
Segmentation is driven by three engineering axes — torque-management capability, driveline architecture and propulsion — with electronic variants growing two to three times faster than mechanical baselines.
Passenger car, SUV/crossover, Light commercial, Heavy truck, Bus, Off-highway
By Propulsion
ICE, Hybrid, Battery electric
By Sales Channel
OEM, Aftermarket
Electronic variants combined (ELSD ~22.7%, torque vectoring ~9.8%) already represent roughly 32.5% of the 2025 type mix. This is the single most important segmentation signal: the revenue mix is re-weighting toward software-differentiated hardware.
Which region leads in Automotive Differential System Market?
Asia-Pacific leads with approximately 43% of 2025 global differential revenue, anchored by China's 30-million-unit-plus annual vehicle output and India's passenger-car production above 4.5 million units.
Automotive Differential System Market Regional Market Share
Loading chart...
Automotive Differential System Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.43%
Europe
0.24%
North America
0.2%
South America
0.07%
Middle East & Africa
0.06%
Global
Asia-Pacific — China, India, Japan, South Korea, ASEAN
Europe — Germany, UK, France, Italy, Spain, Nordics
North America — USA, Canada, Mexico
Latin America — Brazil, Mexico, Argentina, Colombia
Middle East & Africa — Saudi Arabia, UAE, South Africa
Region
2025 share
Asia-Pacific
43%
Europe
24%
North America
20%
South America
7%
Middle East & Africa
6%
Europe's 24% share is disproportionate to its vehicle output, reflecting premium AWD mix and concentrated driveline engineering. North America's 20% is pickup- and SUV-led, where each unit carries front, rear and sometimes center differential content.
What is driving growth — and what is holding it back?
Growth is being pulled by content-per-vehicle expansion, not unit volume: global production of 92.5 million units in 2024 is roughly flat, yet AWD SUVs require two differential assemblies versus one for FWD.
Factor
Direction
Evidence strength
Mechanism
SUV/AWD super-cycle
Driver
High
Two differentials per AWD unit; AWD/4WD growing ~5.5% CAGR
EV e-Axle integration
Driver
High
EV differential segment ~8.2% CAGR; new architecture content
Electronic torque management
Driver
Medium-high
ELSD/torque vectoring outgrowing mechanical types
Aftermarket parc
Driver
Medium
1.4 Billion global vehicle parc sustains replacement demand
EV cannibalization of conventional formats
Restraint
Medium
Fewer shafts and housings per BEV driveline
Raw material and tooling cost
Restraint
Medium
Steel, aluminum and bearing cost volatility compresses margins
The balance favors growth, but the composition is shifting. Our analysis suggests the restraint that matters is not volume but value migration: BEVs eliminate some mechanical content while adding controls content, so suppliers positioned only in gears and housings capture a shrinking share of the value pool even as the headline market grows.
Who are the leading vendors?
No supplier holds more than roughly 5% global share, and the top five together control just over 20%, making this a fragmented market where program wins — not scale alone — determine position.
Company
HQ
Strategic positioning
Differential relevance
ZF Friedrichshafen
Germany
Full driveline and chassis systems
Market leader, ~4.7% share (2025)
American Axle & Manufacturing
USA
Axle and driveline specialist
Strong in pickups and AWD
Dana Incorporated
USA
Driveline and e-Axle
Broad ICE and EV portfolio
BorgWarner
USA
Torque management and e-drive
eTVD production programs
GKN Automotive
UK
Driveline and e-Axle
Strong AWD and EV integration
Eaton
Ireland
Differential and traction control
Off-highway and commercial
JTEKT
Japan
Driveline and bearings
Asian OEM depth
Competitive moats are shifting from machining capacity toward controls calibration, functional safety (ISO 26262) and vehicle-level software integration. A supplier that wins the torque-management software spec early in an OEM program effectively locks out competitors for that platform's lifecycle — a seven-to-ten-year revenue annuity.
What do buyers and operators need to know?
Buyers evaluating differential suppliers should weight five criteria: torque-management software maturity, e-Axle packaging capability, functional-safety certification depth, regional manufacturing footprint alignment with OEM assembly, and aftermarket parts availability. Procurement risk concentrates in single-source electronic modules, where switching costs are high because calibration is co-developed with the OEM's vehicle dynamics team.
Regulatory compliance is increasingly non-negotiable. UNECE braking and stability regulations, combined with Euro 7 and China 6 emissions rules, effectively mandate electronic traction intervention, which pulls ELSD and torque vectoring from optional to required content on higher-segment vehicles. Operators should also model raw material pass-through clauses, since steel and bearing cost volatility in 2023–24 materially compressed Tier 1 margins.
The aftermarket presents a distinct decision: with a parc above 1.4 billion vehicles, replacement differential demand is stable but price-sensitive, and counterfeit risk in emerging markets is a real quality exposure. Buyers should require traceability and OEM-equivalent validation.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a content-migration thesis over a volume-growth thesis. The market compounds at a steady 4.6%, but the value pool inside it is reallocating fast: electronic and torque-vectoring content is growing at roughly twice the market rate while open differential hardware tracks global production. Investors and operators who treat this as a stable mechanical-parts market will misprice the opportunity.
The strongest counter-argument is that open differentials still hold 34.5% share and will not disappear, because cost-sensitive FWD platforms in India, ASEAN and Latin America depend on mechanical simplicity. That is true, but it describes volume, not margin. The defensible position is that mechanical scale funds the transition while controls capability determines who earns above-cost-of-capital returns after 2030.
Vendors: Qualify torque-management software with at least two OEMs by 2027 to escape commodity pricing on mechanical housings.
Investors: Prioritize suppliers with e-Axle-integrated differential revenue exposure above 15% of driveline sales.
Operators: Build dual-sourcing for electronic control modules to hedge calibration lock-in and single-source risk.
What would change this conclusion: if BEV driveline architectures standardize on in-wheel motors that eliminate central differentials faster than expected, the torque-management premium would compress. Evidence of that shift — rising in-wheel motor patent activity or OEM platform announcements — should trigger a re-rating of the thesis.
Automotive Differential System Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Automotive Differential System Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.6% from 2020-2034
Segmentation
By Type
Open Differential
Limited Slip Differential
Locking Differential
Electronic Limited Slip Differential
Torque Vectoring Differential
By Drive Type
FWD
RWD
AWD/4WD
2WD
By Component
Differential Gear
Differential Case
Differential Bearing
Seals & Gaskets
Control Modules
By Vehicle Type
Passenger Car
SUV/Crossover
Light Commercial Vehicle
Heavy Truck
Bus
Off-Highway Vehicle
By Propulsion
ICE
Hybrid
Battery Electric
By Sales Channel
OEM
Aftermarket
By Geography
Asia Pacific
China
India
Japan
South Korea
ASEAN
Europe
Germany
UK
France
Italy
Spain
Nordics
North America
USA
Canada
Mexico
Latin America
Brazil
Mexico
Argentina
Colombia
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Open Differential
5.1.2. Limited Slip Differential
5.1.3. Locking Differential
5.1.4. Electronic Limited Slip Differential
5.1.5. Torque Vectoring Differential
5.2. Market Analysis, Insights and Forecast - by Drive Type
5.2.1. FWD
5.2.2. RWD
5.2.3. AWD/4WD
5.2.4. 2WD
5.3. Market Analysis, Insights and Forecast - by Component
5.3.1. Differential Gear
5.3.2. Differential Case
5.3.3. Differential Bearing
5.3.4. Seals & Gaskets
5.3.5. Control Modules
5.4. Market Analysis, Insights and Forecast - by Vehicle Type
5.4.1. Passenger Car
5.4.2. SUV/Crossover
5.4.3. Light Commercial Vehicle
5.4.4. Heavy Truck
5.4.5. Bus
5.4.6. Off-Highway Vehicle
5.5. Market Analysis, Insights and Forecast - by Propulsion
5.5.1. ICE
5.5.2. Hybrid
5.5.3. Battery Electric
5.6. Market Analysis, Insights and Forecast - by Sales Channel
5.6.1. OEM
5.6.2. Aftermarket
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. Asia Pacific
5.7.2. Europe
5.7.3. North America
5.7.4. Latin America
5.7.5. Middle East & Africa
6. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Open Differential
6.1.2. Limited Slip Differential
6.1.3. Locking Differential
6.1.4. Electronic Limited Slip Differential
6.1.5. Torque Vectoring Differential
6.2. Market Analysis, Insights and Forecast - by Drive Type
6.2.1. FWD
6.2.2. RWD
6.2.3. AWD/4WD
6.2.4. 2WD
6.3. Market Analysis, Insights and Forecast - by Component
6.3.1. Differential Gear
6.3.2. Differential Case
6.3.3. Differential Bearing
6.3.4. Seals & Gaskets
6.3.5. Control Modules
6.4. Market Analysis, Insights and Forecast - by Vehicle Type
6.4.1. Passenger Car
6.4.2. SUV/Crossover
6.4.3. Light Commercial Vehicle
6.4.4. Heavy Truck
6.4.5. Bus
6.4.6. Off-Highway Vehicle
6.5. Market Analysis, Insights and Forecast - by Propulsion
6.5.1. ICE
6.5.2. Hybrid
6.5.3. Battery Electric
6.6. Market Analysis, Insights and Forecast - by Sales Channel
6.6.1. OEM
6.6.2. Aftermarket
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Open Differential
7.1.2. Limited Slip Differential
7.1.3. Locking Differential
7.1.4. Electronic Limited Slip Differential
7.1.5. Torque Vectoring Differential
7.2. Market Analysis, Insights and Forecast - by Drive Type
7.2.1. FWD
7.2.2. RWD
7.2.3. AWD/4WD
7.2.4. 2WD
7.3. Market Analysis, Insights and Forecast - by Component
7.3.1. Differential Gear
7.3.2. Differential Case
7.3.3. Differential Bearing
7.3.4. Seals & Gaskets
7.3.5. Control Modules
7.4. Market Analysis, Insights and Forecast - by Vehicle Type
7.4.1. Passenger Car
7.4.2. SUV/Crossover
7.4.3. Light Commercial Vehicle
7.4.4. Heavy Truck
7.4.5. Bus
7.4.6. Off-Highway Vehicle
7.5. Market Analysis, Insights and Forecast - by Propulsion
7.5.1. ICE
7.5.2. Hybrid
7.5.3. Battery Electric
7.6. Market Analysis, Insights and Forecast - by Sales Channel
7.6.1. OEM
7.6.2. Aftermarket
8. North America Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Open Differential
8.1.2. Limited Slip Differential
8.1.3. Locking Differential
8.1.4. Electronic Limited Slip Differential
8.1.5. Torque Vectoring Differential
8.2. Market Analysis, Insights and Forecast - by Drive Type
8.2.1. FWD
8.2.2. RWD
8.2.3. AWD/4WD
8.2.4. 2WD
8.3. Market Analysis, Insights and Forecast - by Component
8.3.1. Differential Gear
8.3.2. Differential Case
8.3.3. Differential Bearing
8.3.4. Seals & Gaskets
8.3.5. Control Modules
8.4. Market Analysis, Insights and Forecast - by Vehicle Type
8.4.1. Passenger Car
8.4.2. SUV/Crossover
8.4.3. Light Commercial Vehicle
8.4.4. Heavy Truck
8.4.5. Bus
8.4.6. Off-Highway Vehicle
8.5. Market Analysis, Insights and Forecast - by Propulsion
8.5.1. ICE
8.5.2. Hybrid
8.5.3. Battery Electric
8.6. Market Analysis, Insights and Forecast - by Sales Channel
8.6.1. OEM
8.6.2. Aftermarket
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Open Differential
9.1.2. Limited Slip Differential
9.1.3. Locking Differential
9.1.4. Electronic Limited Slip Differential
9.1.5. Torque Vectoring Differential
9.2. Market Analysis, Insights and Forecast - by Drive Type
9.2.1. FWD
9.2.2. RWD
9.2.3. AWD/4WD
9.2.4. 2WD
9.3. Market Analysis, Insights and Forecast - by Component
9.3.1. Differential Gear
9.3.2. Differential Case
9.3.3. Differential Bearing
9.3.4. Seals & Gaskets
9.3.5. Control Modules
9.4. Market Analysis, Insights and Forecast - by Vehicle Type
9.4.1. Passenger Car
9.4.2. SUV/Crossover
9.4.3. Light Commercial Vehicle
9.4.4. Heavy Truck
9.4.5. Bus
9.4.6. Off-Highway Vehicle
9.5. Market Analysis, Insights and Forecast - by Propulsion
9.5.1. ICE
9.5.2. Hybrid
9.5.3. Battery Electric
9.6. Market Analysis, Insights and Forecast - by Sales Channel
9.6.1. OEM
9.6.2. Aftermarket
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Open Differential
10.1.2. Limited Slip Differential
10.1.3. Locking Differential
10.1.4. Electronic Limited Slip Differential
10.1.5. Torque Vectoring Differential
10.2. Market Analysis, Insights and Forecast - by Drive Type
10.2.1. FWD
10.2.2. RWD
10.2.3. AWD/4WD
10.2.4. 2WD
10.3. Market Analysis, Insights and Forecast - by Component
10.3.1. Differential Gear
10.3.2. Differential Case
10.3.3. Differential Bearing
10.3.4. Seals & Gaskets
10.3.5. Control Modules
10.4. Market Analysis, Insights and Forecast - by Vehicle Type
10.4.1. Passenger Car
10.4.2. SUV/Crossover
10.4.3. Light Commercial Vehicle
10.4.4. Heavy Truck
10.4.5. Bus
10.4.6. Off-Highway Vehicle
10.5. Market Analysis, Insights and Forecast - by Propulsion
10.5.1. ICE
10.5.2. Hybrid
10.5.3. Battery Electric
10.6. Market Analysis, Insights and Forecast - by Sales Channel
10.6.1. OEM
10.6.2. Aftermarket
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Automotive Differential System Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia Pacific Automotive Differential System Market Revenue (Billion), by Type 2026 & 2034
Figure 3: Asia Pacific Automotive Differential System Market Revenue Share (%), by Type 2026 & 2034
Figure 4: Asia Pacific Automotive Differential System Market Revenue (Billion), by Drive Type 2026 & 2034
Figure 5: Asia Pacific Automotive Differential System Market Revenue Share (%), by Drive Type 2026 & 2034
Figure 6: Asia Pacific Automotive Differential System Market Revenue (Billion), by Component 2026 & 2034
Figure 7: Asia Pacific Automotive Differential System Market Revenue Share (%), by Component 2026 & 2034
Figure 8: Asia Pacific Automotive Differential System Market Revenue (Billion), by Vehicle Type 2026 & 2034
Figure 9: Asia Pacific Automotive Differential System Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 10: Asia Pacific Automotive Differential System Market Revenue (Billion), by Propulsion 2026 & 2034
Figure 11: Asia Pacific Automotive Differential System Market Revenue Share (%), by Propulsion 2026 & 2034
Figure 12: Asia Pacific Automotive Differential System Market Revenue (Billion), by Sales Channel 2026 & 2034
Figure 13: Asia Pacific Automotive Differential System Market Revenue Share (%), by Sales Channel 2026 & 2034
Figure 14: Asia Pacific Automotive Differential System Market Revenue (Billion), by Country 2026 & 2034
Figure 15: Asia Pacific Automotive Differential System Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Automotive Differential System Market Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Automotive Differential System Market Revenue Billion Forecast, by Drive Type 2020 & 2034
Table 3: Automotive Differential System Market Revenue Billion Forecast, by Component 2020 & 2034
Table 4: Automotive Differential System Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 5: Automotive Differential System Market Revenue Billion Forecast, by Propulsion 2020 & 2034
Table 6: Automotive Differential System Market Revenue Billion Forecast, by Sales Channel 2020 & 2034
Table 7: Automotive Differential System Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: Asia Pacific Automotive Differential System Market Revenue Billion Forecast, by Type 2020 & 2034
Table 9: Asia Pacific Automotive Differential System Market Revenue Billion Forecast, by Drive Type 2020 & 2034
Table 10: Asia Pacific Automotive Differential System Market Revenue Billion Forecast, by Component 2020 & 2034
Table 11: Asia Pacific Automotive Differential System Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 12: Asia Pacific Automotive Differential System Market Revenue Billion Forecast, by Propulsion 2020 & 2034
Table 13: Asia Pacific Automotive Differential System Market Revenue Billion Forecast, by Sales Channel 2020 & 2034
Table 14: Asia Pacific Automotive Differential System Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: China Automotive Differential System Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the automotive differential system market size in 2025?
It was approximately USD 25.7 Billion globally in 2025, across OEM and replacement channels. A competing estimate places it at USD 23.9 Billion, with the gap largely explained by whether e-Axle-integrated differentials are counted.
2. What is the automotive differential system market CAGR?
The market grows at approximately 4.6% annually from 2026 to 2035. Electronic limited-slip and torque-vectoring sub-segments expand faster, at roughly 6.9% and 8.2% respectively, well above the headline rate.
3. Which region dominates the automotive differential system market?
Asia-Pacific leads with roughly 43% of global revenue, supported by China's output above 30 million units and India's passenger-car expansion. Europe follows at about 24%, reflecting premium AWD mix over raw volume.
4. Who are the key players in the automotive differential system market?
ZF Friedrichshafen, American Axle & Manufacturing, Dana, BorgWarner and GKN Automotive lead, collectively holding about 20.3% of 2025 revenue. Eaton, JTEKT and Magna also hold meaningful positions.
5. Why is torque vectoring the fastest-growing differential type?
Torque vectoring grows at roughly 8.2% CAGR because it delivers safety and driving-dynamics value, integrates with ESC and ADAS controllers, and is becoming standard on premium crossovers and electric SUVs.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our 70/30 primary-to-secondary research split underpins every figure in this report. We conducted structured in-depth interviews across the differential value chain, including Tier 1 axle and driveline manufacturers, gear and bearing producers, electronic control module suppliers, and authorized aftermarket distributors. Interviewees were drawn from VP Sourcing, Head of Driveline R&D, Vehicle Dynamics Technical Director, and Commercial Operations leadership roles to capture both procurement and engineering perspectives.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Driveline R&D and Vehicle Dynamics Directors
35%
Procurement and Sourcing Leads
30%
Commercial Operations Leads
20%
Quality and Functional Safety Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Tier 1 Axle & Driveline Manufacturers
40%
Gear, Bearing & Housing Producers
25%
Electronic Control Module Suppliers
20%
Aftermarket Distributors & Traders
15%
Secondary Benchmarking & Public Trade Validation
We validated demand and trade flows against UN Comtrade and Eurostat automotive component data, US ITC schedules, corporate 10-K and annual investor filings, patent databases for torque-vectoring and e-Axle IP, and technical standards published by SAE International, ISO and UNECE on functional safety and vehicle stability.
Demand Modeling & Market Sizing Triangulation
We simultaneously ran a Top-Down allocation from global vehicle production and drivetrain mix against a Bottom-Up build from manufacturer capacity, unit pricing and end-use consumption by vehicle class. Divergences above 8% were re-interrogated with primary respondents before reconciliation.
 Automotive Differential System Market