 On Demand Car Wash Service Market
: 2026 Global Outlook
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 273

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 On Demand Car Wash Service Market
Sadashiv Parab
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 25.00 B |
| 2026 | 26.40 B |
| 2027 | 27.90 B |
| 2028 | 29.50 B |
| 2029 | 31.20 B |
| 2030 | 33.00 B |
| 2031 | 34.80 B |

On demand car wash service is a mobile app- or web-based vehicle cleaning model where professional crews arrive at a customer's home, office or selected location, or reserve a connected station bay, at a scheduled time. Booking, payment and real-time tracking are handled digitally, removing the trip, queue and cash-handling friction of traditional washing.
This analysis covers the global on demand car wash service category, segmented by service type (exterior, interior, full), package tier (basic, standard, premium), service location (doorstep, car wash station) and region. It includes consumer, fleet and corporate contract revenue for scheduled and app-initiated washes.
This analysis does not cover conventional fixed-site automatic tunnel washing that is booked only at the pay station, self-service coin-operated bays, vehicle detailing consumables sold at retail, or fleet-leasing and fuel-card adjacent services. Collision repair, ceramic coating warranties and insurance-backed reconditioning are also excluded.
The most defensible base-year figure is 25.0 Billion for 2025, because it triangulates with the 6.8 billion global smartphone base and 1.4 billion vehicles on road. A second analysis sits roughly 500 Million lower, and the gap is almost entirely a definitional dispute rather than a demand dispute.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 25.0 Billion | 2025 | 2033 | 5.7% | Full category incl. doorstep and station booking | One published estimate |
| 24.5 Billion | 2025 | 2033 | 6.3% | Excludes some franchise station revenue | A competing analysis |
| 3.34 Billion | 2025 | 2033 | 5.5% | Standard package tier only, not total market | A third-party databook |
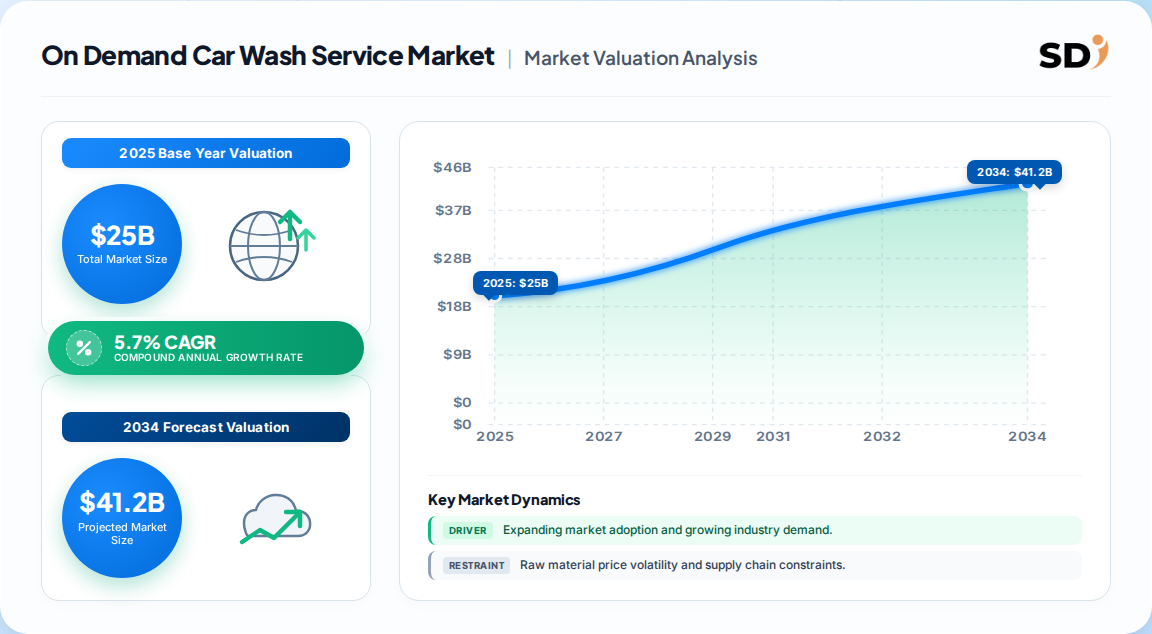
The 25.0 Billion figure is the most defensible for total-market planning. The 24.5 Billion figure implies a narrower scope and a 6.3% CAGR that is credible only if doorstep penetration accelerates faster than station revenue dilutes. Our analysis suggests the true CAGR sits between 5.7% and 6.0% for the full category, with the premium packaging and interior detailing mix doing the uplift.
Segmentation follows four axes: type, package, service location and region. The interior type and the doorstep location are the two fastest-moving cuts, and package tier determines contribution margin far more than revenue share implies.
| Parent | Children | Fastest-growing child |
|---|---|---|
| By Type | Exterior, Interior, Full | Interior (6.9% CAGR) |
| By Package | Basic, Standard, Premium, Others | Standard (5.5% CAGR) |
| By Service Location | Doorstep, Car Wash Station | Doorstep |
Exterior washing remains the volume engine, but it is a commoditised, price-transparent line. Interior and full washes carry higher ticket and higher labour intensity, and the 6.9% interior CAGR is the clearest signal that buyers are trading frequency for depth. The basic package's 39.3% share confirms that entry pricing still recruits customers; the premium and standard tiers are where retention economics are decided.
North America leads with 43.7% of 2025 revenue, driven by near-universal smartphone ownership, high vehicle density and mature app-based booking habits. Asia Pacific is the fastest-growing region, anchored by India, Japan and China.
| Region | Market Share (%) |
|---|---|
| North America | 0.44% |
| Europe | 0.2% |
| Asia Pacific | 0.25% |
| Latin America | 0.07% |
| Middle East & Africa | 0.05% |
| Region | 2025 share | Growth posture |
|---|---|---|
| North America | 43.7% | Mature, app-saturated, subscription-led |
| Asia Pacific | 24.7% | Fastest, vehicle-ownership driven |
| Europe | 19.8% | Water regulation accelerates waterless models |
| Latin America | 7.1% | Urban, price-sensitive, franchise-led |
| Middle East & Africa | 4.7% | Emerging, fleet and corporate demand |
Our analysis suggests North America's share will erode slowly through 2033 as Asia Pacific compounds faster from a smaller base. Japan is expected to register the highest country-level CAGR within the standard package tier. The implication for operators is that North America funds expansion while Asia Pacific builds the next revenue pool.
Convenience-first consumer behaviour and app-native booking are the dominant drivers, reinforced by water-scarcity regulation that favours low-water doorstep methods. Operating-model fragility, weather exposure and labour consistency are the principal restraints on scaling.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Convenience and digital booking | Driver | High | App scheduling, cashless payment, real-time tracking |
| Vehicle ownership and urbanisation | Driver | High | 1.4 billion vehicles; 68.4% urban by 2050 |
| Eco-friendly and waterless methods | Driver | Medium-High | Water recycling, liquid CO and ZLD systems |
| Subscription and wallet integration | Driver | Medium | Recurring bookings and retention |
| Workforce scheduling and quality variance | Restraint | High | Labour turnover, inconsistent service outcomes |
| Weather and seasonal exposure | Restraint | Medium | Outdoor washing interruptions and idle capacity |
The balance favours growth, but not evenly. Drivers are structural and demand-side; restraints are operational and execution-side. This asymmetry implies that capital and management attention should flow to scheduling density and quality assurance rather than to customer acquisition. The 62% of U.S. consumers who prefer real-time tracking and updates shows that technology is now a retention lever, not merely a booking convenience.
Five names frame the competitive set: WashMyCar, Eco Clean Car, Zippy Auto Wash, TidyCars and Washify. Each is differentiating on platform capability, eco-positioning or subscription mechanics rather than on wash quality alone.
| Vendor | Primary differentiation | Recent signal |
|---|---|---|
| WashMyCar | Mobile-first booking and doorstep coverage | Expanding app-based footprint |
| Eco Clean Car | Waterless and biodegradable cleaning | Sustainability positioning |
| Zippy Auto Wash | Subscription and digital wallet | 2025 subscription launch |
| TidyCars | Neighbourhood density and detailing | Local network depth |
| Washify | SaaS management for station networks | 2025 cloud platform expansion |
Our analysis suggests the durable moat is not the wash itself but scheduling density per service radius combined with recurring payment relationships. Washify's SaaS pivot is strategically important: by selling the operating layer to franchise and station networks, it monetises rivals' growth rather than competing for the same doorstep customer. That is a second-order effect many buyers miss when they benchmark only consumer-facing apps.
Selection should hinge on five criteria: coverage radius and guaranteed arrival windows; quality assurance and crew training consistency; water and chemical compliance; payment, subscription and data integration; and insurance and damage-liability terms.
Procurement risk concentrates in service-level consistency. Variations across locations and personnel directly affect satisfaction and brand reputation, and weather-driven cancellations create rebooking spikes that strain capacity. Switching costs are moderate for households but high for fleets and corporate contracts once recurring bookings and vehicle history are embedded in the platform.
Regulatory exposure differs by jurisdiction. Water-use restrictions in Europe and parts of Asia Pacific increasingly favour waterless and recycling-based methods, while discharge rules affect station-based operators. Buyers should require documented water consumption per wash and chemical-handling compliance before signing multi-year contracts. Insurance and liability allocation for paint or interior damage should be contractually explicit rather than assumed.
The balance of evidence favours the full-category 25.0 Billion base and a 5.7% CAGR, with prudent planning at 5.9% to account for premium mix uplift. The strongest counter-argument is that the 6.3% competing estimate is correct and the category is growing faster than consensus assumes. That case rests on doorstep penetration compounding beyond urban cores, which we consider plausible but not yet evidenced at scale.
Our judgement is that value migration is running from station revenue toward recurring doorstep subscriptions. Station service remains 75.7% of revenue and will not disappear, but its share of incremental growth is shrinking. Operators who treat doorstep as a premium add-on rather than a core channel will cede the highest-retention customers to subscription-native rivals.
What would change our conclusion: a verified doorstep share above 30% of category revenue by 2028, or regulatory mandates that make waterless washing compulsory in two or more major European markets. Either would justify upgrading the growth case toward 6.5%. Precise sub-segment forecasting by country and package tier requires the full dataset, where the regional splits and vendor capacity mappings are available in detail.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.7% from 2020-2034 |
| Segmentation |
|
The global on demand car wash service market is estimated at 26.4 Billion in 2026, up from 25.0 Billion in 2025. It is forecast to reach 38.9 Billion by 2033 at a 5.7% CAGR over the 2026 to 2033 period.
North America leads with 43.7% of 2025 revenue, supported by high vehicle ownership and near-universal smartphone adoption. Asia Pacific is the fastest-growing region, with India and Japan posting the strongest country-level momentum.
Interior car wash is the fastest-growing type at a 6.9% CAGR from 2026 to 2033, as customers trade wash frequency for higher-ticket depth. Doorstep service is the fastest-growing location, expanding faster than station-based booking.
Estimates diverge because of scope, not demand. The 25.0 Billion figure includes doorstep and station booking revenue, while lower figures exclude some franchise station revenue or isolate a single package tier such as standard.
Operational complexity and service quality consistency are the primary restraints. Workforce scheduling, geographic coverage, weather-driven cancellations and variation in quality across crews all constrain scaling and affect brand reputation.
Leading players include WashMyCar, Eco Clean Car, Zippy Auto Wash, TidyCars and Washify. Differentiation rests on platform capability, eco-friendly cleaning methods and subscription mechanics rather than on wash quality alone.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research programme applies a 70/30 primary-to-secondary split. In-depth interviews were conducted across the value chain with mobile wash operators, franchise network owners, equipment and chemical suppliers, SaaS platform providers and corporate fleet buyers. Within those organisations we interviewed VP-level commercial operations leads, heads of service delivery, procurement directors and regulatory compliance managers.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Commercial Operations Leads | 35% |
| Heads of Service Delivery | 30% |
| Procurement Directors | 20% |
| Regulatory Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Mobile Wash Operators & Franchise Networks | 40% |
| Equipment & Chemical Suppliers | 25% |
| SaaS & Booking Platform Providers | 20% |
| Corporate Fleet & Contract Buyers | 15% |
We validate findings against UN Comtrade and WTO trade statistics, US ITC filings, Eurostat service-sector data, corporate 10-K and annual investor presentations, patent databases, and recognised technical standards from vehicle-care and water-efficiency associations.
We run simultaneous top-down allocation from vehicle parc, urbanisation and smartphone penetration, and bottom-up modelling from operator capacity, average ticket and wash frequency. Divergences are reconciled at segment level rather than in aggregate.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up operator revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border service flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |