Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Walk In Cooler Freezer Market: Size, Share & 2035 Forecast
Walk In Cooler Freezer Market
Walk In Cooler Freezer Market: Size, Share & 2035 Forecast
Walk In Cooler Freezer Market by Type (Walk-in Coolers, Walk-in Freezers, Combination Units), by Construction (Pre-Engineered, Custom-Built, Modular), by Application (Food and Beverage, Pharmaceuticals, Floral Preservation, Chemical Storage), by End Use (Retail Stores, Restaurants, Catering Services, Food Processing Units), by Technology (Remote Condensing, Self-Contained, Multiple Condensing), by Place of Use (Indoor, Outdoor), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Turkey) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 219
Why this matters for decision-makers: The gap between 5% and 12% CAGR narratives is not academic — it dictates whether capex should chase new-build volume or replacement/retrofit and refrigerant-compliance cycles. Vendors that anchor strategy to the slower base case must win on service, energy efficiency, and regulatory readiness, not unit volume.
Walk In Cooler Freezer Market Size (In Billion)
15.0B
10.0B
5.0B
0
8.630 B
2024
9.060 B
2025
9.510 B
2026
9.980 B
2027
10.47 B
2028
10.99 B
2029
11.54 B
2030
Walk In Cooler Freezer Market Size (In Billion)
Year
Market Size
2024
8.630 B
2025
9.060 B
2026
9.510 B
2027
9.980 B
2028
10.47 B
2029
10.99 B
2030
11.54 B
What is the Walk In Cooler Freezer Market?
The Walk In Cooler Freezer Market comprises refrigerated walk-in rooms — modular or pre-engineered enclosures with remote or self-contained condensing — used for above- or below-freezing storage of food, pharmaceuticals, floral, and chemicals. Revenue includes panels, refrigeration packages, installation, and bundled service contracts across retail, foodservice, cold-chain, and healthcare end uses.
This analysis covers walk-in coolers, walk-in freezers, and combination units — pre-engineered, custom-built, and modular — across food & beverage, pharmaceutical, floral, and chemical applications. It includes indoor and outdoor installations, remote, self-contained, and multiple-condensing technologies, and revenue from equipment, installation, and bundled service.
This analysis does not cover reach-in refrigerators, display cases, blast chillers/freezers, transport refrigeration (reefer trailers/containers), industrial ammonia rack systems, or residential refrigeration. It also excludes cold-storage warehouse construction as a standalone category except where walk-in rooms are procured as part of that build.
How big is the market for Walk In Cooler Freezer Market?
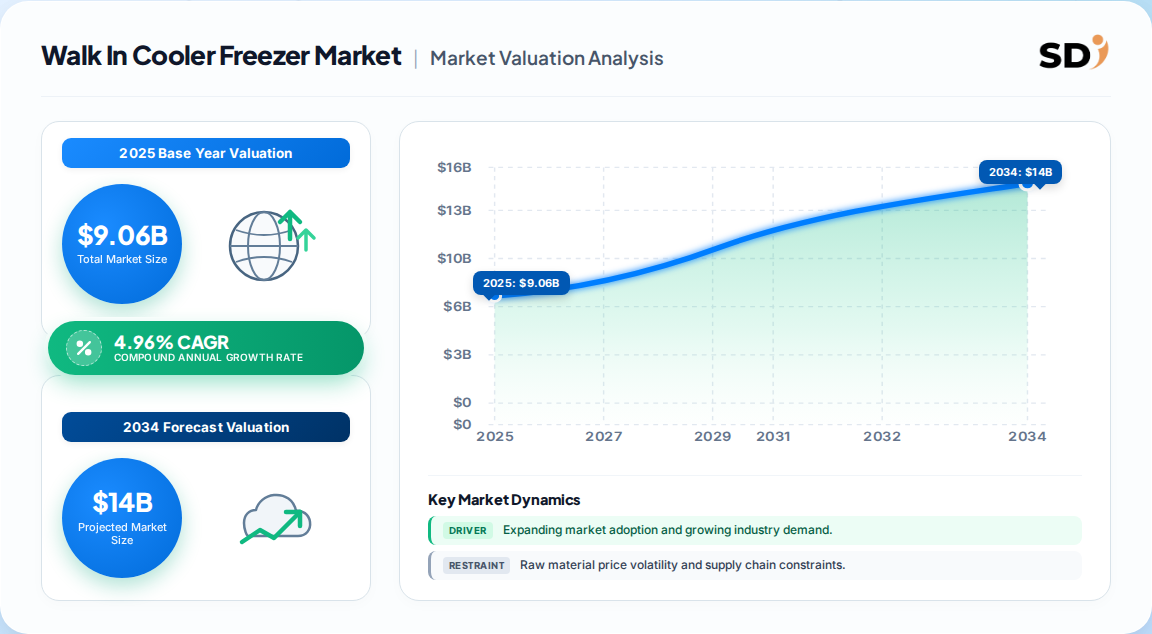
The most defensible global base is roughly 9.06 Billion in 2025, growing to 14.7 Billion by 2035 at 4.96% CAGR — a moderate, replacement-led trajectory consistent with mature commercial refrigeration economics.
Estimate (USD)
Base year
Horizon
CAGR
Definition / scope
Attribution
8.63B → 14.7B
2024
2035
4.96%
Global walk-in coolers, freezers, combination; equipment + install
One published estimate (secondary benchmark)
10.5B → 27.9B
2025
2033
12.3%
Global, incl. indoor/outdoor, broad end-use
Competing analysis
10.94B → 23.92B
2026
2033
11.8%
Global, food + pharma storage focus
Competing analysis
11.2B → 20.7B
2025
2036
5.7%
Global, place-of-use + technology segmentation
Competing analysis
$0.73B → $1.17B (U.S.)
2025
2035
5.0%
U.S. walk-in coolers only
Primary benchmark (regional)
Our analysis suggests the ~5% CAGR cluster (4.96%, 5.7%, 5.0% U.S.) is more defensible than the 11–12% cohort. The high-growth estimates appear to bundle broader cold-chain construction and equipment into the walk-in definition, inflating the base. The U.S. cooler-only benchmark growing at 5% is a strong sanity check for a mature, replacement-driven category.
How is the market segmented?
Segmentation is best read along four axes — product type, construction, application, and end use — with technology and place-of-use as operational overlays.
Parent segment
Children
Largest / fastest signal
By Type
Walk-in Coolers, Walk-in Freezers, Combination Units
Coolers largest (~61%); Freezers fastest
By Construction
Pre-Engineered, Custom-Built, Modular
Pre-engineered largest; Modular fastest
By Application
Food & Beverage, Pharmaceuticals, Floral Preservation, Chemical Storage
Which region leads in Walk In Cooler Freezer Market?
North America leads with roughly 34% of global revenue in 2025, underpinned by a dense U.S. installed base and a regulatory-driven replacement cycle; Asia Pacific is the fastest-growing region, led by China and India.
Walk In Cooler Freezer Market Regional Market Share
Loading chart...
Walk In Cooler Freezer Market Regional Market Share
Region
Market Share (%)
North America
0.34%
Europe
0.24%
Asia-Pacific
0.28%
South America
0.06%
Middle East & Africa
0.08%
North America — USA, Canada, Mexico
U.S. is the single largest country market (~$0.73B coolers-only in 2025); replacement demand dominates.
Europe — Germany, UK, France, Italy, Spain
F-gas regulation and energy-efficiency mandates drive retrofit activity.
Asia Pacific — China, Japan, India, South Korea, Australia
Fastest CAGR; organized retail and cold-chain build-out.
Latin America — Brazil, Mexico, Argentina
Brazil among highest-growth countries (~7.5% CAGR).
Middle East & Africa — Saudi Arabia, UAE, South Africa, Turkey
Saudi Arabia and Turkey show elevated growth (~7.1–7.3%).
What is driving growth — and what is holding it back?
Growth is anchored by replacement demand and refrigerant-transition compliance, with foodservice expansion and pharmaceutical cold chain adding incremental volume — but high installed-base maturity and construction softness cap the upside.
Factor
Direction
Evidence strength
Mechanism
Foodservice scale & QSR expansion
Driver
High
U.S. foodservice >$1.1T (2024); dense installed base sustains replacement
Pharmaceutical cold chain (GLP-1 biologics)
Driver
High
Validated 2–8°C storage at every node; highest-CAGR application
EPA AIM Act HFC phase-down
Driver
High
GWP ≤700 from 2026; ≤150/≤300 by 2032; accelerated replacement 2028–2031
U.S. construction $120.9B (2024); constrains greenfield installs
DOE WICF efficiency-standard withdrawal
Restraint
High
May 2025 withdrawal defers 2025–2027 compliance replacements
High upfront install cost & energy opex
Restraint
Medium
Site prep, electrical, professional install add to equipment price
Mature produce/dairy segment (~36–40°F)
Restraint
Medium
~4.2% CAGR; long replacement cycles dilute aggregate growth
The balance of evidence favors a compliance-paced, replacement-led market rather than a boom. The DOE standard withdrawal is a near-term negative for upgrade demand, but the AIM Act HFC schedule creates a predictable 2028–2031 replacement wave. So what? Vendors should treat 2025–2027 as a service and retrofit window, positioning A2L/natural-refrigerant-ready product for the 2028+ surge.
Who are the leading vendors?
The global market is moderately consolidated: Carrier leads with roughly 11–12% share, while Hussmann (Panasonic) leads the U.S. cooler segment at ~19%; the top five U.S. players hold ~61%.
Company
HQ
Positioning / moat
Carrier Global
US
Broadest refrigeration portfolio; global distribution; ~11.8% share
Hussmann (Panasonic)
US
U.S. cooler leader (~19%); Evolve low-GWP platform
Thermo King (Trane)
US
Transport + stationary cold chain integration
Hoshizaki
JP
Asia strength; ice + refrigeration systems
True Manufacturing
US
Foodservice brand equity; dealer network
Nor-Lake
US
Custom/modular walk-ins; mid-market
Master-Bilt
US
Value-tier commercial refrigeration
Kolpak
US
U.S. cooler installed base; service reach
Daikin
JP
Integrated HVAC-R; refrigerant technology
Differentiation is shifting from enclosure capacity to refrigerant architecture, monitoring compatibility, and commissioning service. Our analysis suggests service coverage — not panel price — is becoming the decisive moat, because installation disruption is as costly to operators as the equipment itself.
What do buyers and operators need to know?
Walk-in procurement is a system purchase, not a box purchase. The room must hold its specified temperature during real loading and door use, which links panel insulation, refrigeration capacity, and installation detail into one acceptance test. Buyers who compare nominal capacity alone systematically under-specify.
Three decision criteria matter most. First, refrigerant pathway: AIM Act GWP limits mean a unit bought today must be serviceable through 2032+; A2L and natural-refrigerant options carry a compliance premium but avoid stranded assets. Second, heat-rejection and service access: remote condensing (~48% of demand) frees kitchen space but adds piping and maintenance planning. Third, documentation and monitoring: pharmaceutical buyers require validated temperature records and IoT compatibility, a procurement logic distinct from foodservice.
Switching costs are high — installation disruption, electrical work, and floor/wall interfaces make replacement a planned event, not a spot purchase. Operators should lock service contracts and acceptance protocols at purchase, and confirm which DOE/EPA provisions apply to their specific model and jurisdiction.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors the ~5% CAGR base case over the 11–12% cohort. The high-growth estimates likely conflate broader cold-chain construction with walk-in equipment; the convergence of three independent ~5% benchmarks (global 4.96%, global 5.7%, U.S. 5.0%) is too consistent to dismiss. The strongest counter-argument: if pharmaceutical cold-chain investment and the 2028–2031 HFC replacement wave compound faster than modeled, the true CAGR could land in the 7–9% band. We weight that scenario at roughly 25% probability.
For buyers, the strategic imperative is compliance-led modernization. The DOE standard withdrawal creates a temporary lull, but the AIM Act schedule is the binding constraint; procuring A2L/natural-refrigerant-ready rooms now avoids a forced 2031 replacement at peak pricing. For vendors, growth will come from service attach and retrofit, not greenfield volume — the U.S. construction contraction and mature produce segment cap new-build upside.
Actionable strategy:
Operators: Time replacements to the 2028–2030 window, but specify low-GWP, monitoring-ready equipment now to avoid stranded assets.
Vendors: Build service and commissioning capability in North America and Asia Pacific; differentiate on refrigerant pathway, not panel price.
Investors: Favor players with installed-base service reach and pharmaceutical-grade documentation capability over pure equipment manufacturers.
What would change our conclusion: a sustained rebound in U.S. commercial construction above $140B or an acceleration in GLP-1 cold-chain capex beyond 20% CAGR would justify the higher-growth scenario and shift our base case upward.
Walk In Cooler Freezer Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Walk In Cooler Freezer Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.96% from 2020-2034
Segmentation
By Type
Walk-in Coolers
Walk-in Freezers
Combination Units
By Construction
Pre-Engineered
Custom-Built
Modular
By Application
Food and Beverage
Pharmaceuticals
Floral Preservation
Chemical Storage
By End Use
Retail Stores
Restaurants
Catering Services
Food Processing Units
By Technology
Remote Condensing
Self-Contained
Multiple Condensing
By Place of Use
Indoor
Outdoor
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Turkey
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Walk-in Coolers
5.1.2. Walk-in Freezers
5.1.3. Combination Units
5.2. Market Analysis, Insights and Forecast - by Construction
5.2.1. Pre-Engineered
5.2.2. Custom-Built
5.2.3. Modular
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Food and Beverage
5.3.2. Pharmaceuticals
5.3.3. Floral Preservation
5.3.4. Chemical Storage
5.4. Market Analysis, Insights and Forecast - by End Use
5.4.1. Retail Stores
5.4.2. Restaurants
5.4.3. Catering Services
5.4.4. Food Processing Units
5.5. Market Analysis, Insights and Forecast - by Technology
5.5.1. Remote Condensing
5.5.2. Self-Contained
5.5.3. Multiple Condensing
5.6. Market Analysis, Insights and Forecast - by Place of Use
5.6.1. Indoor
5.6.2. Outdoor
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Latin America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Walk-in Coolers
6.1.2. Walk-in Freezers
6.1.3. Combination Units
6.2. Market Analysis, Insights and Forecast - by Construction
6.2.1. Pre-Engineered
6.2.2. Custom-Built
6.2.3. Modular
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Food and Beverage
6.3.2. Pharmaceuticals
6.3.3. Floral Preservation
6.3.4. Chemical Storage
6.4. Market Analysis, Insights and Forecast - by End Use
6.4.1. Retail Stores
6.4.2. Restaurants
6.4.3. Catering Services
6.4.4. Food Processing Units
6.5. Market Analysis, Insights and Forecast - by Technology
6.5.1. Remote Condensing
6.5.2. Self-Contained
6.5.3. Multiple Condensing
6.6. Market Analysis, Insights and Forecast - by Place of Use
6.6.1. Indoor
6.6.2. Outdoor
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Walk-in Coolers
7.1.2. Walk-in Freezers
7.1.3. Combination Units
7.2. Market Analysis, Insights and Forecast - by Construction
7.2.1. Pre-Engineered
7.2.2. Custom-Built
7.2.3. Modular
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Food and Beverage
7.3.2. Pharmaceuticals
7.3.3. Floral Preservation
7.3.4. Chemical Storage
7.4. Market Analysis, Insights and Forecast - by End Use
7.4.1. Retail Stores
7.4.2. Restaurants
7.4.3. Catering Services
7.4.4. Food Processing Units
7.5. Market Analysis, Insights and Forecast - by Technology
7.5.1. Remote Condensing
7.5.2. Self-Contained
7.5.3. Multiple Condensing
7.6. Market Analysis, Insights and Forecast - by Place of Use
7.6.1. Indoor
7.6.2. Outdoor
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Walk-in Coolers
8.1.2. Walk-in Freezers
8.1.3. Combination Units
8.2. Market Analysis, Insights and Forecast - by Construction
8.2.1. Pre-Engineered
8.2.2. Custom-Built
8.2.3. Modular
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Food and Beverage
8.3.2. Pharmaceuticals
8.3.3. Floral Preservation
8.3.4. Chemical Storage
8.4. Market Analysis, Insights and Forecast - by End Use
8.4.1. Retail Stores
8.4.2. Restaurants
8.4.3. Catering Services
8.4.4. Food Processing Units
8.5. Market Analysis, Insights and Forecast - by Technology
8.5.1. Remote Condensing
8.5.2. Self-Contained
8.5.3. Multiple Condensing
8.6. Market Analysis, Insights and Forecast - by Place of Use
8.6.1. Indoor
8.6.2. Outdoor
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Walk-in Coolers
9.1.2. Walk-in Freezers
9.1.3. Combination Units
9.2. Market Analysis, Insights and Forecast - by Construction
9.2.1. Pre-Engineered
9.2.2. Custom-Built
9.2.3. Modular
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Food and Beverage
9.3.2. Pharmaceuticals
9.3.3. Floral Preservation
9.3.4. Chemical Storage
9.4. Market Analysis, Insights and Forecast - by End Use
9.4.1. Retail Stores
9.4.2. Restaurants
9.4.3. Catering Services
9.4.4. Food Processing Units
9.5. Market Analysis, Insights and Forecast - by Technology
9.5.1. Remote Condensing
9.5.2. Self-Contained
9.5.3. Multiple Condensing
9.6. Market Analysis, Insights and Forecast - by Place of Use
9.6.1. Indoor
9.6.2. Outdoor
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Walk-in Coolers
10.1.2. Walk-in Freezers
10.1.3. Combination Units
10.2. Market Analysis, Insights and Forecast - by Construction
10.2.1. Pre-Engineered
10.2.2. Custom-Built
10.2.3. Modular
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Food and Beverage
10.3.2. Pharmaceuticals
10.3.3. Floral Preservation
10.3.4. Chemical Storage
10.4. Market Analysis, Insights and Forecast - by End Use
10.4.1. Retail Stores
10.4.2. Restaurants
10.4.3. Catering Services
10.4.4. Food Processing Units
10.5. Market Analysis, Insights and Forecast - by Technology
10.5.1. Remote Condensing
10.5.2. Self-Contained
10.5.3. Multiple Condensing
10.6. Market Analysis, Insights and Forecast - by Place of Use
10.6.1. Indoor
10.6.2. Outdoor
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Walk In Cooler Freezer Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Walk In Cooler Freezer Market Revenue (Billion), by Type 2026 & 2034
Figure 3: North America Walk In Cooler Freezer Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Walk In Cooler Freezer Market Revenue (Billion), by Construction 2026 & 2034
Figure 5: North America Walk In Cooler Freezer Market Revenue Share (%), by Construction 2026 & 2034
Figure 6: North America Walk In Cooler Freezer Market Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Walk In Cooler Freezer Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Walk In Cooler Freezer Market Revenue (Billion), by End Use 2026 & 2034
Figure 9: North America Walk In Cooler Freezer Market Revenue Share (%), by End Use 2026 & 2034
Figure 10: North America Walk In Cooler Freezer Market Revenue (Billion), by Technology 2026 & 2034
Figure 11: North America Walk In Cooler Freezer Market Revenue Share (%), by Technology 2026 & 2034
Figure 12: North America Walk In Cooler Freezer Market Revenue (Billion), by Place of Use 2026 & 2034
Figure 13: North America Walk In Cooler Freezer Market Revenue Share (%), by Place of Use 2026 & 2034
Figure 14: North America Walk In Cooler Freezer Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Walk In Cooler Freezer Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Walk In Cooler Freezer Market Revenue (Billion), by Type 2026 & 2034
List of Tables
Table 1: Walk In Cooler Freezer Market Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Walk In Cooler Freezer Market Revenue Billion Forecast, by Construction 2020 & 2034
Table 3: Walk In Cooler Freezer Market Revenue Billion Forecast, by Application 2020 & 2034
Table 4: Walk In Cooler Freezer Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 5: Walk In Cooler Freezer Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 6: Walk In Cooler Freezer Market Revenue Billion Forecast, by Place of Use 2020 & 2034
Table 7: Walk In Cooler Freezer Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Walk In Cooler Freezer Market Revenue Billion Forecast, by Type 2020 & 2034
Table 9: North America Walk In Cooler Freezer Market Revenue Billion Forecast, by Construction 2020 & 2034
Table 10: North America Walk In Cooler Freezer Market Revenue Billion Forecast, by Application 2020 & 2034
Table 11: North America Walk In Cooler Freezer Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 12: North America Walk In Cooler Freezer Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 13: North America Walk In Cooler Freezer Market Revenue Billion Forecast, by Place of Use 2020 & 2034
Table 14: North America Walk In Cooler Freezer Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA Walk In Cooler Freezer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Canada Walk In Cooler Freezer Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the Walk In Cooler Freezer Market?
The global market was valued at roughly 9.06 Billion in 2025 and is forecast to reach 14.7 Billion by 2035, growing at a 4.96% CAGR. North America leads regional demand with about 34% share.
2. What is the fastest-growing segment in the Walk In Cooler Freezer Market?
Walk-in freezers are the fastest-growing product type, and pharmaceutical cold-chain storage is the fastest-growing application, driven by biologics and GLP-1 injectables requiring validated 2–8°C storage.
3. Who are the leading companies in the Walk In Cooler Freezer Market?
Carrier leads globally with roughly 11–12% share. Hussmann (Panasonic) leads the U.S. cooler segment at about 19%. Other key players include Thermo King, Hoshizaki, True Manufacturing, Nor-Lake, and Master-Bilt.
4. What is driving demand for walk-in coolers and freezers?
Replacement demand, refrigerant-transition compliance under the EPA AIM Act, foodservice expansion, and pharmaceutical cold-chain investment are the primary drivers. Commercial construction softness and the DOE efficiency-standard withdrawal moderate near-term growth.
5. Which region is expected to grow fastest?
Asia Pacific is the fastest-growing region, led by China and India. Among individual countries, Brazil, Saudi Arabia, and Turkey show the highest CAGRs at roughly 7–7.5%.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the walk-in cold-storage value chain, including insulated-panel and refrigeration-component suppliers, specialized walk-in manufacturers, contract installers and commissioning specialists, and global commercial-refrigeration distributors. Interviewees were drawn from decision-maker roles including VP of Sourcing, Heads of Refrigeration Engineering, Technical Directors, and Commercial Operations Leads, ensuring specification, procurement, and service perspectives are represented.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Refrigeration Engineering Heads
35%
Procurement & Sourcing Directors
30%
Technical & Compliance Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Insulated Panel & Component Suppliers
30%
Specialized Walk-In Manufacturers
35%
Installers & Commissioning Specialists
20%
Commercial Refrigeration Distributors
15%
Secondary Benchmarking & Public Trade Validation
Findings were benchmarked against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards and industry associations. Regulatory timelines from the U.S. EPA AIM Act and DOE appliance standards were incorporated to anchor the compliance-driven replacement cycle.
Demand Modeling & Market Sizing Triangulation
Market sizing uses simultaneous Top-Down (macroeconomic and end-use segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption) triangulation. Divergent published estimates were reconciled by normalizing scope definitions — separating walk-in equipment from broader cold-chain construction — to produce a defensible base case.
 Walk In Cooler Freezer Market