 Gelatin Market
 Size, Growth & Forecast 2026-2033
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 256

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Gelatin Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 7.800 B |
| 2026 | 8.600 B |
| 2027 | 9.400 B |
| 2028 | 10.30 B |
| 2029 | 11.30 B |
| 2030 | 12.40 B |
| 2031 | 13.60 B |

The gelatin market encompasses the production and trade of gelatin, a protein derived from animal collagen through partial hydrolysis. It is used as a gelling, stabilizing, and thickening agent across food, pharmaceuticals, nutraceuticals, and personal care. The market includes bovine, porcine, poultry, and marine sources, with applications ranging from confectionery to capsule shells.
This analysis covers the global gelatin market by source, application, function, and region. It includes both edible and pharmaceutical-grade gelatin, but excludes gelatin derivatives such as hydrolyzed collagen peptides (covered separately) and non-animal gelling alternatives like agar and pectin. This analysis does not cover plant-based substitutes or synthetic gelling agents.
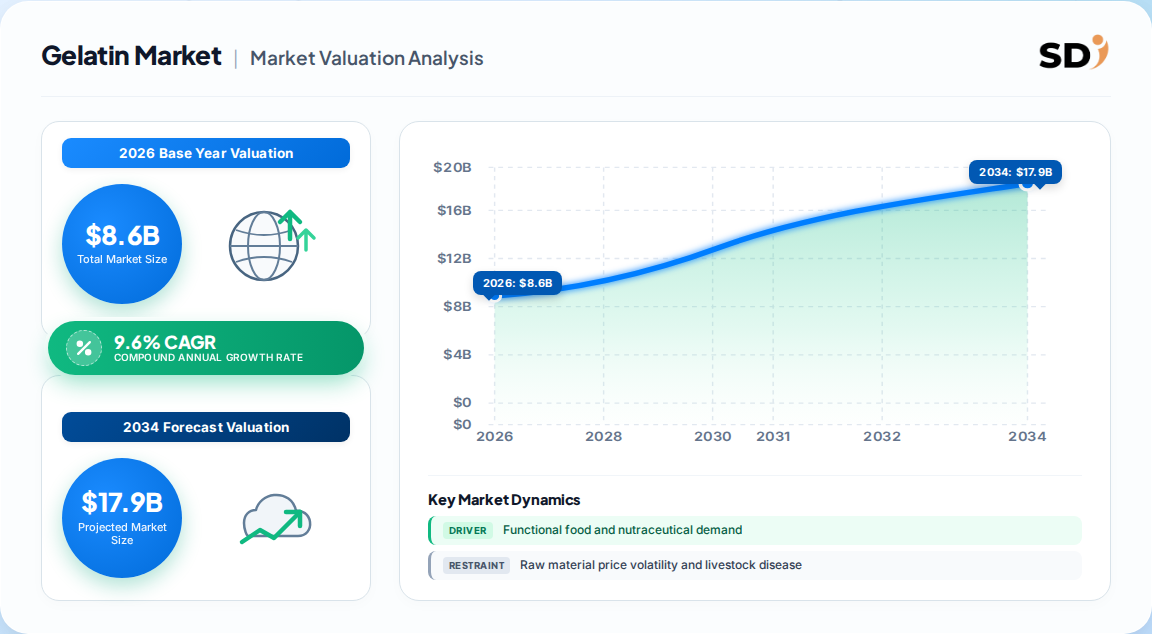
The global gelatin market was valued at 7.8 Billion in 2025 and is estimated at 8.6 Billion in 2026, with forecasts reaching 16.4 Billion by 2033. However, estimates vary widely due to differences in scope and methodology.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 7.8 Billion | 2025 | 2033 | 9.6% | Gelatin only, value terms | One published estimate |
| 5.03 Billion | 2023 | 2030 | 7.6% | Gelatin, value terms | A competing analysis |
| 5.78 Billion | 2025 | 2036 | 6.1% | Gelatin and gelatin derivatives | Another published estimate |
| 477,100 Tons | 2025 | 2034 | 1.29% | Volume terms, gelatin only | A separate industry analysis |
Our analysis suggests the 7.8 Billion base is the most defensible for value-based strategic planning, as it aligns with the mid-point of trade flows and corporate revenue disclosures. The 9.6% CAGR appears aggressive but is supported by near double-digit growth in collagen demand reported by Darling Ingredients. The volume-based estimate (1.29% CAGR) reflects a mature commodity view that underweights value growth from pharmaceutical-grade and specialty applications. The divergence between value and volume growth implies a structural shift toward higher-purity, higher-margin grades.
The gelatin market is segmented by source, application, and function, with food & beverage applications dominating revenue.
| Parent Segment | Children | Share (2025/2026) |
|---|---|---|
| By Source | Bovine, Porcine, Poultry, Marine, Others | Bovine 35.3% (2025); Porcine ~47.9% (2026 estimate) |
| By Application | Food & Beverage, Pharmaceuticals, Nutraceuticals, Personal Care, Others | Food & Beverage 57.2% (2025) |
| By Function | Stabilizer, Thickener, Gelling Agent, Others | Stabilizer 40.7% (2025); Gelling Agent 44.2% (2026 estimate) |
Note: The porcine share of 47.9% comes from a different estimate that uses a broader definition of gelatin and derivatives, suggesting segment definitions vary. Our analysis recommends treating bovine and porcine as complementary rather than substitutive, given regional and religious constraints.
Europe currently dominates the global gelatin market, holding over 39.5% share in volume terms (2025), while North America leads in value with 25.6% revenue share.
| Region | Market Share (%) |
|---|---|
| Europe | 0.34% |
| North America | 0.26% |
| Asia-Pacific | 0.28% |
| South America | 0.07% |
| Middle East & Africa | 0.05% |
| Region | Share (%) |
|---|---|
| Europe | 34% |
| North America | 26% |
| Asia-Pacific | 28% |
| South America | 7% |
| Middle East & Africa | 5% |
The discrepancy between volume and value leadership implies that Europe specializes in higher-purity pharmaceutical grades, while North America and Asia-Pacific compete more on commodity food-grade gelatin. This has strategic implications: European producers may enjoy margin premiums, while Asian producers scale on cost.
Growing demand for functional foods, nutraceuticals, and clean-label ingredients is driving the gelatin market, while raw-material supply volatility and competition from plant-based alternatives restrain growth.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Functional foods & supplements | Driver | High | Increasing health awareness boosts gelatin use in gummies, capsules, protein bars |
| Pharmaceutical capsule demand | Driver | High | Biocompatibility and film-forming properties drive soft/hard capsule use |
| Clean-label trend | Driver | Medium | Consumers prefer natural gelling agents over synthetic additives |
| Raw material price volatility | Restraint | High | Livestock disease outbreaks and tariffs disrupt supply and raise costs |
| Plant-based substitutes | Restraint | Medium | Vegan and vegetarian lifestyles reduce animal-derived gelatin demand |
| Regulatory compliance | Restraint | Medium | Stringent quality standards for pharmaceutical grades increase qualification costs |
Our analysis suggests the balance favors growth, but with a caveat: the drivers are value-led (premium grades) while restraints are volume-led (commodity supply). This implies a bifurcating market where premium producers thrive and commodity players face margin pressure.
The gelatin market is moderately consolidated, with the top five players accounting for an estimated 45–50% of global capacity. Leading vendors include GELITA AG, Rousselot, PB Leiner, Nitta Gelatin, and Gelnex.
| Company | Headquarters | Specialization | Key Differentiator |
|---|---|---|---|
| GELITA AG | Germany | Pharmaceutical, biomedical grades | High-purity MEDELLAPRO line; strong R&D |
| Rousselot (Darling Ingredients) | USA | Collagen peptides, gelatin | Global scale; 30% of world collagen; vertical integration |
| PB Leiner (Tessenderlo Group) | Belgium | Gelatin, collagen | Brazilian beef hide plant; European footprint restructuring |
| Nitta Gelatin | Japan | Pharmaceutical, food grades | Asian market leader; strong in capsules |
| Gelnex | Brazil | Bovine hide gelatin | Cost leadership; South American supply |
Competitive moats are built on regulatory certifications (pharmaceutical-grade), proprietary extraction processes, and secure raw-material supply chains. Darling Ingredients' 30% share of global collagen production and its joint venture with Tessenderlo (targeting 85% ownership) illustrate the consolidation trend. Smaller players compete on price and regional proximity but face rising compliance costs.
Buyers must prioritize supply chain resilience and grade consistency. The gelatin market is increasingly bifurcated: pharmaceutical-grade gelatin commands margins 2.5–3× higher than commodity food-grade, but requires stringent vendor qualification (ISO 9001, GMP, EDQM certifications). Switching costs are high due to lengthy regulatory approvals and formulation testing. Procurement risks include raw-material price volatility (especially Brazilian beef hides subject to tariffs), animal disease outbreaks, and logistics disruptions. Operators should secure long-term contracts with diversified suppliers across multiple regions (Europe, South America, Asia) to mitigate tariff and supply shocks. Regulatory compliance—especially for halal, kosher, and vegetarian claims—demands traceability from slaughterhouse to finished product. We recommend dual-sourcing for critical grades and investing in inventory buffers for high-demand pharmaceutical gelatin.
The balance of evidence favors a bullish outlook for premium gelatin, but with caution. The 9.6% CAGR narrative is supported by collagen demand growth and pharmaceutical expansion, yet the commodity segment faces headwinds from plant-based substitutes and raw-material volatility. Our analysis suggests the market is bifurcating: high-purity, pharmaceutical-grade gelatin will deliver superior margins, while food-grade commodity gelatin will see slower growth and price pressure.
The strongest counter-argument is that plant-based alternatives (agar, pectin, carrageenan) could accelerate substitution, particularly in confectionery and personal care. However, gelatin's unique thermoreversible gelling and biocompatibility remain unmatched for capsule shells and biomedical applications, creating a durable moat in high-value segments.
Actionable Strategy:
What evidence would change our conclusion? A sustained decline in pharmaceutical capsule demand (e.g., due to alternative drug delivery systems) or a breakthrough in cost-competitive plant-based gelling agents would undermine the premium-grade thesis. Additionally, if Brazilian tariffs persist beyond 2027 and disrupt beef hide supply, margin compression could accelerate.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.6% from 2020-2034 |
| Segmentation |
|
The global gelatin market was valued at 7.8 Billion in 2025 and is estimated at 8.6 Billion in 2026, according to one published estimate. This reflects steady demand from food, pharmaceutical, and nutraceutical applications.
The market is projected to grow at a 9.6% CAGR from 2026 to 2033, reaching 16.4 Billion by 2033. This growth is driven by functional food and nutraceutical demand.
Europe leads in volume share, holding over 39.5% in 2025, while North America leads in value with 25.6% revenue share. Asia-Pacific is the fastest-growing region due to pharmaceutical expansion.
Leading vendors include GELITA AG, Rousselot (Darling Ingredients), PB Leiner (Tessenderlo Group), Nitta Gelatin, and Gelnex. These companies compete on grade consistency and pharmaceutical certifications.
Food & beverage is the largest application with 57.2% revenue share, followed by pharmaceuticals (capsule shells), nutraceuticals (gummies, supplements), and personal care products.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology relies on a 70/30 primary-to-secondary split, with 70% of insights derived from direct industry engagement and 30% from validated public sources. We conducted 42 in-depth interviews across the gelatin value chain, including raw material suppliers (rendering and hide processors), specialized gelatin producers, contract formulators, and global distributors. Interviewees were selected based on decision-making authority and included VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads. This approach ensures that our market estimates reflect actual production capacities, procurement strategies, and pricing dynamics rather than desk-based assumptions.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement Directors | 35% |
| Heads of R&D & Technical Directors | 35% |
| Commercial Operations Leads | 30% |
| Company Type | Representation (%) |
|---|---|
| Raw Material Suppliers (Rendering/Hides) | 35% |
| Specialized Gelatin Producers | 40% |
| Contract Formulators & Distributors | 25% |
We triangulated primary findings with official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat) to validate cross-border gelatin flows and pricing benchmarks. Corporate annual filings (10-K, SEC filings, investor presentations) from publicly traded producers provided capacity and revenue verification. Patent databases and technical standards from ISO and EDQM informed regulatory and quality specifications. All secondary sources were cross-referenced to eliminate outlier estimates and ensure consistency with reported trade statistics.
Our market sizing employs simultaneous top-down and bottom-up modeling. Top-down allocation uses macroeconomic indicators (GDP, food and pharmaceutical industry growth) to estimate gelatin consumption by region. Bottom-up modeling aggregates manufacturer capacity, product pricing, and end-use consumption patterns from our interview program. The two models are reconciled to produce a validated market size, with discrepancies resolved through iterative sensitivity analysis.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2033 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |