 Vcsel Market
VCSEL Market Size, Forecast & Trends to 2035
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 212

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Vcsel Market
Srinwanti Kar
Senior Research Analyst
| Year | Market Size |
|---|---|
| 2024 | 1.780 B |
| 2025 | 2.040 B |
| 2026 | 2.350 B |
| 2027 | 2.690 B |
| 2028 | 3.090 B |
| 2029 | 3.550 B |
| 2030 | 4.080 B |

The VCSEL (vertical-cavity surface-emitting laser) market covers semiconductor lasers that emit light perpendicular to the chip surface, used for high-speed data links, 3D sensing, LiDAR, industrial heating, and infrared illumination. It spans single- and multi-mode devices across GaAs, InP, and GaN material systems.
This report covers global VCSEL device revenue across type, material, wavelength, application, and end-user verticals from 2024 to 2035. It addresses both merchant sales and captive supply. This analysis does not cover edge-emitting lasers, silicon photonics transceivers as standalone products, LED-based sensing modules, or the broader optical transceiver market except where VCSEL content is directly implicated.
The most defensible reading is a USD 1.78 Billion 2024 base growing at ~14.8% CAGR to USD 8.15 Billion by 2035 — a figure consistent with the shipment trajectory implied by earlier benchmark studies. Competing published estimates diverge sharply because they define the market differently.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 1.78 Bn → USD 8.15 Bn | 2024 | 2035 | 14.83% | VCSEL devices, all applications, global | One published market estimate |
| >USD 1 Bn → ~USD 5 Bn | 2020 | 2027 | >20% | VCSEL devices incl. captive; 3.5 Bn units/yr | A competing analysis |
| Implied ~USD 1.9 Bn (2024) | 2020 | 2027 | 20% | Same scope, earlier vintage | Derived from the above |
The older 20% CAGR figure reflects a 2020–2021 vintage that captured the smartphone 3D-sensing ramp; the newer 14.83% figure is a more mature, post-smartphone-saturation view. Our analysis suggests the truth lies between: data-center optical interconnect demand is accelerating faster than the 2035 curve assumes, while consumer 3D sensing is decelerating. Buyers should treat USD 8.15 Billion as a conservative central case.
Segmentation is dominated by application and type, with material and wavelength acting as proxies for performance tier and cost.
| Parent segment | Children |
|---|---|
| By Type | Single-mode, Multi-mode |
| By Material | Gallium Arsenide (GaAs), Indium Phosphide (InP), Gallium Nitride (GaN), Others |
| By Wavelength | 850 nm, 850–940 nm, 940–1,050 nm, >1,050 nm |
| By Application | Data communication, Sensing, Industrial heating & laser printing, Infrared illumination, Others |
| By End-User | Consumer electronics, IT & telecom, Automotive, Industrial, Healthcare, Aerospace & defense |
GaAs dominates revenue (historically >65%) because 850–940 nm devices serve both short-reach data links and sensing. Multi-mode is the growth engine: it delivers higher power density for time-of-flight and LiDAR, and its share is rising fastest in automotive.
Asia-Pacific leads on volume and is the fastest-growing region, anchored by consumer-electronics assembly in China, Taiwan, South Korea, and Japan; North America leads on innovation and data-center demand. Europe is a strong second in automotive and industrial photonics.
| Region | Market Share (%) |
|---|---|
| North America | 0.28% |
| Europe | 0.19% |
| Asia-Pacific | 0.44% |
| South America | 0.03% |
| Middle East & Africa | 0.06% |
| Parent region | Countries / sub-markets |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy |
| Asia Pacific | China, Japan, India, South Korea, Taiwan |
| Latin America | Brazil, Mexico, Argentina |
| Middle East & Africa | Saudi Arabia, UAE, South Africa |
Asia-Pacific's lead is structural: the region hosts the smartphone OEMs and contract manufacturers that embed VCSELs in 3D-sensing modules, and it is where automotive LiDAR supply chains are coalescing. North America's share is defended by hyperscaler data-center capex and by the headquarters of the leading VCSEL vendors.
The demand side is strong and broadening; the supply side and a few technical limits are the real constraints.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Data-center optical interconnect | Driver | High | 400G/800G links and AI clusters require high-bandwidth, low-power short-reach lasers |
| Smartphone 3D sensing | Driver | High | Facial recognition and proximity sensing embed VCSELs in flagship devices |
| Automotive LiDAR & driver monitoring | Driver | Medium-High | Multi-mode VCSELs enable ToF ranging and in-cabin sensing |
| Energy-efficiency mandates | Driver | Medium | Low power draw vs. edge-emitters; regulatory pressure on data-center PUE |
| Limited transmission range | Restraint | Medium | VCSELs suit short reach; longer links need alternative lasers |
| Manufacturing yield & GaAs capacity | Restraint | Medium | Epitaxy and wafer-level packaging constrain scale-up |
| Consumer demand cyclicality | Restraint | Medium | Smartphone shipment swings transmit directly into sensing revenue |
The balance favors growth: data-center and automotive demand are structural multi-year cycles, whereas the restraints are largely execution issues that capital can solve. The key risk is timing — if AI-driven data-center capex normalizes before automotive LiDAR volumes scale, the 2027–2029 window could undershoot the consensus curve.
The vendor landscape is moderately concentrated at the top, with vertically integrated photonics players dominating and specialist VCSEL houses occupying niche sensing and automotive slots.
| Company | HQ | Primary strength |
|---|---|---|
| Coherent (II-VI) | USA | Broad photonics portfolio, data-com and sensing VCSELs |
| Lumentum | USA | High-volume consumer 3D sensing and data-center optics |
| Broadcom | USA | Optical interconnect and data-center transceiver integration |
| ams-Osram | Austria/Germany | Automotive LiDAR and sensing VCSELs |
| TRUMPF | Germany | Industrial and high-power photonics |
| Sony | Japan | Consumer sensing and image-sensor adjacency |
| Mitsubishi Electric | Japan | Optical communication and industrial lasers |
Differentiation rests on three moats: epitaxial growth capability (GaAs wafer quality), wafer-level packaging and test yield, and design-in lock-in with smartphone OEMs and automotive Tier-1s. The last is the stickiest — once a VCSEL is qualified into a flagship phone or LiDAR module, switching costs are high and requalification cycles are long.
Procurement decisions hinge on qualification, not price alone. Buyers should prioritize vendors with demonstrated wafer-level packaging yield at volume, because VCSEL cost is dominated by test and packaging rather than epitaxy. Automotive buyers must confirm AEC-Q102 qualification and IATF 16949 supply-chain compliance before design freeze.
Switching costs are significant: requalifying a VCSEL into a consumer module typically takes two to three quarters, and into an automotive platform 12–18 months. That asymmetry favors multi-sourcing early in the design cycle rather than after ramp. Regulatory exposure is moderate but rising — eye-safety classification (IEC 60825) and data-center energy-efficiency rules increasingly shape module design. Operators should also stress-test supply continuity, since GaAs epitaxy capacity is concentrated among a handful of fabs.
The balance of evidence favors a constructive, capacity-constrained growth thesis: demand from AI data centers, automotive LiDAR, and premium smartphones is real and multi-year, but the winners will be decided by who can scale qualified capacity rather than who can design the best device.
The strongest counter-argument is that consumer 3D sensing — historically the single largest VCSEL demand pool — is maturing, and if automotive LiDAR adoption slips, the 14.83% CAGR could prove optimistic. We weight this risk as material but not decisive, because data-center interconnect demand is now large enough to absorb the slack.
Our analysis suggests the market's center of gravity is shifting from smartphone sensing toward data-center and automotive, which changes the competitive requirements from consumer-grade cost leadership to reliability and qualification depth.
Actionable strategy:
What would change our conclusion: a sustained slowdown in hyperscaler data-center capex, or evidence that silicon photonics displaces VCSELs in short-reach links faster than expected. Either would pull the forecast toward the low end of the range. Precise sub-segment forecasting — by wavelength and by end-user vertical — requires the full report's model.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 14.83% from 2020-2034 |
| Segmentation |
|
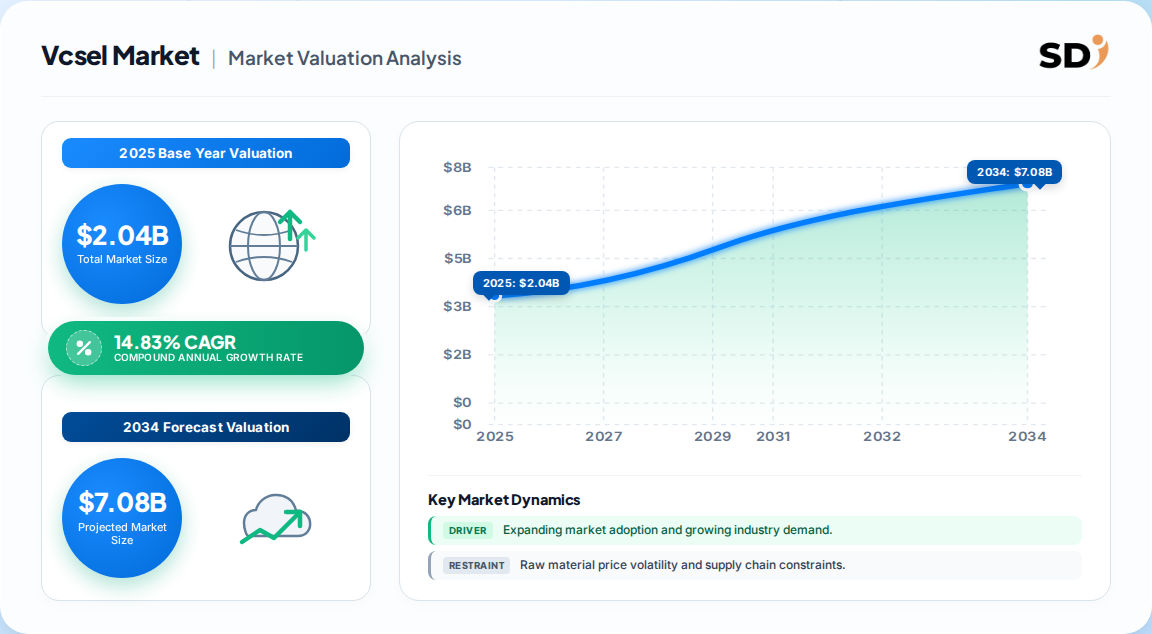
The global VCSEL market is estimated at USD 2.04 Billion in 2025, up from USD 1.78 Billion in 2024. It is projected to reach USD 8.15 Billion by 2035 at a 14.83% CAGR, driven by data communication and sensing demand.
Asia-Pacific leads on volume and growth, anchored by consumer-electronics manufacturing in China, Taiwan, South Korea, and Japan. North America leads on innovation and data-center demand and hosts most leading VCSEL vendors.
Single-mode VCSELs offer narrower spectral width for longer-reach data links and dominate revenue today. Multi-mode VCSELs deliver higher power density for time-of-flight and LiDAR and are the fastest-growing type.
Data communication is the largest application, followed by sensing (facial recognition, gesture detection, LiDAR), industrial heating and laser printing, and infrared illumination. Sensing is the fastest-growing application segment.
Leading players include Coherent (II-VI), Lumentum, Broadcom, ams-Osram, TRUMPF, Sony, and Mitsubishi Electric. Competition centers on epitaxial wafer quality, packaging yield, and design-in lock-in with OEMs.
Growth is driven by AI and 5G data-center interconnect demand, smartphone 3D sensing, automotive LiDAR and driver monitoring, and energy-efficiency mandates. Limited transmission range and GaAs capacity constrain the pace.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study follows a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the VCSEL value chain with GaAs epitaxy and wafer suppliers, specialized VCSEL device producers, optical-module and transceiver formulators, and global photonics distributors. Within these organizations we engaged decision-makers including VP-level sourcing leads, Heads of Photonics R&D, Technical Directors for qualification, and Commercial Operations Leads responsible for design-win pipelines.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Photonics Directors | 38% |
| Procurement & Sourcing Leads | 32% |
| Qualification & Regulatory Managers | 18% |
| Commercial Operations Leads | 12% |
| Company Type | Representation (%) |
|---|---|
| GaAs Epitaxy & Wafer Suppliers | 30% |
| VCSEL Device Producers | 40% |
| Optical Module & Transceiver Formulators | 18% |
| Photonics Distributors & Traders | 12% |
Findings were cross-checked against multilateral trade statistics (UN Comtrade, WTO), national customs and ITC databases, Eurostat, corporate 10-K and annual investor filings, patent databases, and recognized technical-standards bodies including IEC and ISO working groups relevant to laser safety and optoelectronic reliability.
We run Top-Down allocation (macroeconomic ICT capex, smartphone shipment forecasts, automotive ADAS penetration) simultaneously with Bottom-Up modeling (manufacturer capacity, wafer starts, unit pricing, and end-use consumption). Convergence between the two approaches sets the reported range.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
