Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Pediatric Wheelchair Market: Size, CAGR & 2031 Outlook
Pediatric Wheelchair Market: Size, CAGR & 2031 Outlook
Pediatric Wheelchair Market
Pediatric Wheelchair Market: Size, CAGR & 2031 Outlook
Pediatric Wheelchair Market by Product Type (Manual, Powered, Specialized), by Frame Type (Rigid, Foldable, Tilt-in-Space), by Mobility (Basic, Complex), by Application (Cerebral Palsy, Muscular Dystrophy, Spinal Cord Injury, Others), by End User (Hospitals & Clinics, Homecare, Rehabilitation Centers, Schools), by Distribution Channel (Direct Sales, Medical Equipment Retailers, Online, Hospitals), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 223
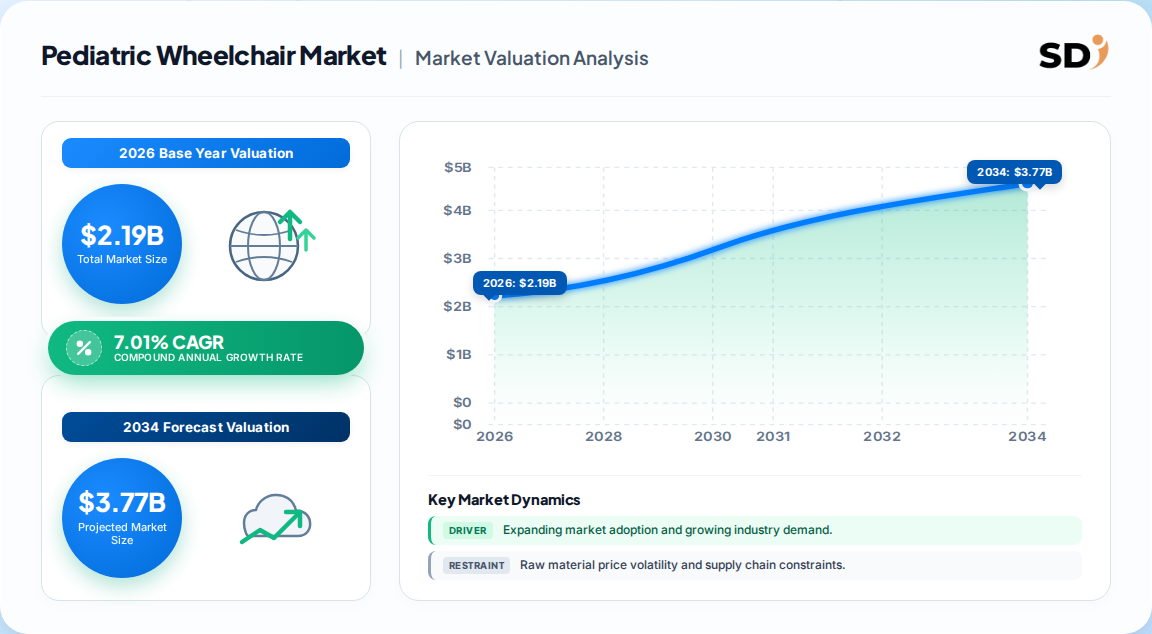
The global pediatric wheelchair market is estimated at 2.19 Billion in 2026, with a forecast of 3.08 Billion by 2031.
Projected CAGR of 7.01% (2026–2031), outpacing historical growth of ~5.2% as early intervention and home care expand.
Manual wheelchairs lead with 60.85% revenue share; powered chairs are the fastest-growing product type at 9.18% CAGR.
North America holds 39.02% share; Asia-Pacific is the fastest-growing region at 11.72% CAGR through 2031.
Leading vendors include Sunrise Medical, Permobil, Invacare, Ottobock, and Pride Mobility, with medium market concentration.
Why this matters for decision-makers: Vendors must pivot toward modular, growth-adjustable designs and powered mobility to capture Asia-Pacific demand and avoid margin compression in mature manual-chair segments.
Pediatric Wheelchair Market Size (In Billion)
4.0B
3.0B
2.0B
1.0B
0
2.050 B
2025
2.190 B
2026
2.340 B
2027
2.510 B
2028
2.680 B
2029
2.870 B
2030
3.080 B
2031
Pediatric Wheelchair Market Size (In Billion)
Year
Market Size
2025
2.050 B
2026
2.190 B
2027
2.340 B
2028
2.510 B
2029
2.680 B
2030
2.870 B
2031
3.080 B
What is the Pediatric Wheelchair Market?
The pediatric wheelchair market covers mobility devices engineered for children with congenital, neuromuscular, or acquired disabilities. Products include manual, powered, and specialized chairs with growth-adjustable seating, tilt-in-space, and postural support, sold through hospitals, dealers, and online channels to support early mobility, rehabilitation, and inclusion.
Scope: what this report covers and excludes
This report covers pediatric wheelchairs by product type (manual, powered, specialized), frame type, mobility complexity, application, end user, and distribution channel across five global regions. It includes revenue forecasts, competitive landscape, and regulatory analysis. This analysis does not cover adult wheelchairs, mobility scooters, exoskeletons, or general rehabilitation equipment.
How big is the market for Pediatric Wheelchair Market?
The pediatric wheelchair market is valued between 1.6 and 2.8 Billion for the 2025–2026 base period, with forecasts diverging due to scope differences. The table below compares leading published estimates.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
2.19 Billion
2026
2031
7.01%
Manual + powered, all end users, global
One published estimate
2.80 Billion
2026
2033
6.3%
Includes specialized and smart mobility
A competing analysis
1.61 Billion
2026
2035
6.79%
Core manual + powered, narrower scope
A competing analysis
Our analysis suggests the 2.19 Billion figure is most defensible as a baseline, because it excludes recreational and specialty chairs that inflate broader estimates, while still capturing homecare and rehabilitation demand. The higher 2.8 Billion figure likely bundles tilt-in-space and smart-assist systems into the core count, which is useful for premium-segment sizing but overstates the addressable manual-chair market. The lower 1.61 Billion estimate likely undercounts emerging-market volume and direct sales.
How is the market segmented?
The market segments by product type, frame type, mobility complexity, application, end user, and distribution channel. Manual chairs dominate volume, while powered and tilt-in-space systems drive value growth.
Direct Sales, Medical Equipment Retailers, Online, Hospitals
Manual chairs held 60.85% share in 2025, but powered chairs are growing at 9.18% CAGR. Foldable frames represent 48.76% of the market, while tilt-in-space systems are advancing at 8.72% CAGR. Homecare is the fastest-growing end-user segment at 8.31% CAGR, reflecting care decentralization.
Which region leads in Pediatric Wheelchair Market?
North America leads the pediatric wheelchair market with 39.02% share in 2025, driven by advanced rehabilitation infrastructure and strong reimbursement. Asia-Pacific is the fastest-growing region at 11.72% CAGR through 2031.
Pediatric Wheelchair Market Regional Market Share
Loading chart...
Pediatric Wheelchair Market Regional Market Share
Region
Market Share (%)
North America
0.39%
Europe
0.26%
Asia-Pacific
0.24%
Latin America
0.06%
Middle East & Africa
0.05%
North America — 39.02% share; U.S. dominates with mature insurance and clinical prescribing.
USA, Canada, Mexico
Europe — ~26% share; Germany, UK, and France lead on inclusive-school mandates.
Germany, UK, France, Italy, Spain
Asia-Pacific — ~24% share; fastest growth from rising disposable income and public insurance.
China, Japan, India, South Korea, Australia
Latin America — ~6% share; Brazil and Mexico drive adoption.
Brazil, Mexico, Argentina
Middle East & Africa — ~5% share; UAE and Saudi Arabia lead premium demand.
Saudi Arabia, UAE, South Africa
This divergence implies that vendors should localize manufacturing and financing in Asia-Pacific while defending premium share in North America through complex rehabilitation technology positioning. Europe's growth will hinge on reimbursement reform and school-access mandates.
What is driving growth — and what is holding it back?
Rising pediatric disability prevalence (+1.8% CAGR impact) and government funding (+1.2%) are the strongest growth drivers. High device cost and insurance gaps in emerging markets (−1.4%) are the primary restraints.
Factor
Direction
Evidence Strength
Mechanism
Rising pediatric disabilities
Driver
High
Improved neonatal survival and earlier diagnosis expand the eligible population
Government funding programs
Driver
High
IDEA, Section 504, and state loan programs lower out-of-pocket costs
Lightweight & power-assist tech
Driver
Medium
Carbon-fiber frames and smart hubs improve independence and prescription rates
Devices cost 3–5x monthly income in lower-income markets
Rapid child growth
Restraint
Medium
Short product lifecycle accelerates replacement but raises total cost
Rare-earth motor supply volatility
Restraint
Medium
Powered-chair makers face input-cost and lead-time risk
The balance favors growth, but the restraint impact is geographically concentrated. Our analysis suggests manufacturers that offer modular growth-adjustable frames can neutralize the child-growth restraint while improving margins through accessory and refit revenue.
Who are the leading vendors?
The market is moderately concentrated, with Sunrise Medical, Permobil, Invacare, Ottobock, and Pride Mobility leading. Differentiation rests on seating customization, reimbursement expertise, and pediatric-specific clinical validation.
Company
HQ
Portfolio Strength
Competitive Moat
Sunrise Medical
USA
Manual, powered, seating
Broad pediatric portfolio and U.S. reimbursement relationships
Permobil
Sweden
Powered, tilt-in-space
Clinical evidence and complex rehab technology leadership
Invacare
USA
Manual, powered
Distribution scale and dealer network
Ottobock
Germany
Specialized seating
Prosthetics-adjacent rehab integration
Pride Mobility
USA
Powered, manual
Cost-effective powered platforms
Ki Mobility
USA
Manual, growth-adjustable
Modular pediatric design focus
Our analysis suggests the strongest moats are built on payer relationships and clinician training, not hardware alone. Vendors without reimbursement navigation capabilities will struggle in North America and Europe, where complex rehab technology requires documented clinical justification.
What do buyers and operators need to know?
Buyers should prioritize growth-adjustable seating, repairability, and local service access over upfront price. Procurement risk is highest in powered chairs, where rare-earth motor supply volatility and battery compliance create lead-time and safety exposure. Switching costs rise sharply once a child is fitted to a specific seating system, so initial specification should account for a five-year growth trajectory. Regulatory compliance varies by region: U.S. buyers need FDA-registered devices and documented complex rehab justification, while EU buyers require CE marking under MDR and ISO 7176 wheelchair standards. Operators should also verify dealer training and warranty terms, as maintenance complexity in advanced models can extend downtime and affect reimbursement.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a 7% CAGR trajectory, anchored by 2.19 Billion in 2026 and 3.08 Billion by 2031. The strongest counter-argument is that high device costs and insurance gaps in emerging markets could suppress growth below 6%, particularly if powered-chair supply volatility persists. However, early-intervention clinical consensus and government funding programs are sufficiently strong to offset these headwinds.
Our analysis suggests the most underappreciated opportunity lies in modular, growth-adjustable frames that reduce total cost of ownership and support recurring refit revenue. Vendors that pair this with online configuration platforms can shorten lead times and capture Asia-Pacific demand, where growth is 11.72% CAGR but price sensitivity is acute.
Actionable Strategy:
Investors should prioritize vendors with reimbursement navigation capabilities and pediatric-specific clinical evidence, as these command premium multiples.
Operators should localize assembly or partnership manufacturing in Asia-Pacific to defend against price competition from low-feature alternatives.
Vendors should invest in powered mobility and smart monitoring integration to capture the 9.18% CAGR powered segment.
What evidence would change our conclusion: a sustained decline in powered-chair reimbursement or a sharp rise in rare-earth motor costs that pushes device prices beyond insurance thresholds would force a downward revision to the forecast.
Pediatric Wheelchair Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Pediatric Wheelchair Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.01% from 2020-2034
Segmentation
By Product Type
Manual
Powered
Specialized
By Frame Type
Rigid
Foldable
Tilt-in-Space
By Mobility
Basic
Complex
By Application
Cerebral Palsy
Muscular Dystrophy
Spinal Cord Injury
Others
By End User
Hospitals & Clinics
Homecare
Rehabilitation Centers
Schools
By Distribution Channel
Direct Sales
Medical Equipment Retailers
Online
Hospitals
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Manual
5.1.2. Powered
5.1.3. Specialized
5.2. Market Analysis, Insights and Forecast - by Frame Type
5.2.1. Rigid
5.2.2. Foldable
5.2.3. Tilt-in-Space
5.3. Market Analysis, Insights and Forecast - by Mobility
5.3.1. Basic
5.3.2. Complex
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Cerebral Palsy
5.4.2. Muscular Dystrophy
5.4.3. Spinal Cord Injury
5.4.4. Others
5.5. Market Analysis, Insights and Forecast - by End User
5.5.1. Hospitals & Clinics
5.5.2. Homecare
5.5.3. Rehabilitation Centers
5.5.4. Schools
5.6. Market Analysis, Insights and Forecast - by Distribution Channel
5.6.1. Direct Sales
5.6.2. Medical Equipment Retailers
5.6.3. Online
5.6.4. Hospitals
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Latin America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Manual
6.1.2. Powered
6.1.3. Specialized
6.2. Market Analysis, Insights and Forecast - by Frame Type
6.2.1. Rigid
6.2.2. Foldable
6.2.3. Tilt-in-Space
6.3. Market Analysis, Insights and Forecast - by Mobility
6.3.1. Basic
6.3.2. Complex
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Cerebral Palsy
6.4.2. Muscular Dystrophy
6.4.3. Spinal Cord Injury
6.4.4. Others
6.5. Market Analysis, Insights and Forecast - by End User
6.5.1. Hospitals & Clinics
6.5.2. Homecare
6.5.3. Rehabilitation Centers
6.5.4. Schools
6.6. Market Analysis, Insights and Forecast - by Distribution Channel
6.6.1. Direct Sales
6.6.2. Medical Equipment Retailers
6.6.3. Online
6.6.4. Hospitals
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Manual
7.1.2. Powered
7.1.3. Specialized
7.2. Market Analysis, Insights and Forecast - by Frame Type
7.2.1. Rigid
7.2.2. Foldable
7.2.3. Tilt-in-Space
7.3. Market Analysis, Insights and Forecast - by Mobility
7.3.1. Basic
7.3.2. Complex
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Cerebral Palsy
7.4.2. Muscular Dystrophy
7.4.3. Spinal Cord Injury
7.4.4. Others
7.5. Market Analysis, Insights and Forecast - by End User
7.5.1. Hospitals & Clinics
7.5.2. Homecare
7.5.3. Rehabilitation Centers
7.5.4. Schools
7.6. Market Analysis, Insights and Forecast - by Distribution Channel
7.6.1. Direct Sales
7.6.2. Medical Equipment Retailers
7.6.3. Online
7.6.4. Hospitals
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Manual
8.1.2. Powered
8.1.3. Specialized
8.2. Market Analysis, Insights and Forecast - by Frame Type
8.2.1. Rigid
8.2.2. Foldable
8.2.3. Tilt-in-Space
8.3. Market Analysis, Insights and Forecast - by Mobility
8.3.1. Basic
8.3.2. Complex
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Cerebral Palsy
8.4.2. Muscular Dystrophy
8.4.3. Spinal Cord Injury
8.4.4. Others
8.5. Market Analysis, Insights and Forecast - by End User
8.5.1. Hospitals & Clinics
8.5.2. Homecare
8.5.3. Rehabilitation Centers
8.5.4. Schools
8.6. Market Analysis, Insights and Forecast - by Distribution Channel
8.6.1. Direct Sales
8.6.2. Medical Equipment Retailers
8.6.3. Online
8.6.4. Hospitals
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Manual
9.1.2. Powered
9.1.3. Specialized
9.2. Market Analysis, Insights and Forecast - by Frame Type
9.2.1. Rigid
9.2.2. Foldable
9.2.3. Tilt-in-Space
9.3. Market Analysis, Insights and Forecast - by Mobility
9.3.1. Basic
9.3.2. Complex
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Cerebral Palsy
9.4.2. Muscular Dystrophy
9.4.3. Spinal Cord Injury
9.4.4. Others
9.5. Market Analysis, Insights and Forecast - by End User
9.5.1. Hospitals & Clinics
9.5.2. Homecare
9.5.3. Rehabilitation Centers
9.5.4. Schools
9.6. Market Analysis, Insights and Forecast - by Distribution Channel
9.6.1. Direct Sales
9.6.2. Medical Equipment Retailers
9.6.3. Online
9.6.4. Hospitals
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Manual
10.1.2. Powered
10.1.3. Specialized
10.2. Market Analysis, Insights and Forecast - by Frame Type
10.2.1. Rigid
10.2.2. Foldable
10.2.3. Tilt-in-Space
10.3. Market Analysis, Insights and Forecast - by Mobility
10.3.1. Basic
10.3.2. Complex
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Cerebral Palsy
10.4.2. Muscular Dystrophy
10.4.3. Spinal Cord Injury
10.4.4. Others
10.5. Market Analysis, Insights and Forecast - by End User
10.5.1. Hospitals & Clinics
10.5.2. Homecare
10.5.3. Rehabilitation Centers
10.5.4. Schools
10.6. Market Analysis, Insights and Forecast - by Distribution Channel
10.6.1. Direct Sales
10.6.2. Medical Equipment Retailers
10.6.3. Online
10.6.4. Hospitals
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Pediatric Wheelchair Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Pediatric Wheelchair Market Revenue (Billion), by Product Type 2026 & 2034
Figure 3: North America Pediatric Wheelchair Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Pediatric Wheelchair Market Revenue (Billion), by Frame Type 2026 & 2034
Figure 5: North America Pediatric Wheelchair Market Revenue Share (%), by Frame Type 2026 & 2034
Figure 6: North America Pediatric Wheelchair Market Revenue (Billion), by Mobility 2026 & 2034
Figure 7: North America Pediatric Wheelchair Market Revenue Share (%), by Mobility 2026 & 2034
Figure 8: North America Pediatric Wheelchair Market Revenue (Billion), by Application 2026 & 2034
Figure 9: North America Pediatric Wheelchair Market Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Pediatric Wheelchair Market Revenue (Billion), by End User 2026 & 2034
Figure 11: North America Pediatric Wheelchair Market Revenue Share (%), by End User 2026 & 2034
Figure 12: North America Pediatric Wheelchair Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 13: North America Pediatric Wheelchair Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 14: North America Pediatric Wheelchair Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Pediatric Wheelchair Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Pediatric Wheelchair Market Revenue (Billion), by Product Type 2026 & 2034
List of Tables
Table 1: Pediatric Wheelchair Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 2: Pediatric Wheelchair Market Revenue Billion Forecast, by Frame Type 2020 & 2034
1. How big is the pediatric wheelchair market in 2026?
The pediatric wheelchair market is estimated at 2.19 Billion in 2026, based on a scope covering manual and powered chairs across all end users globally. Broader estimates including specialized and smart mobility systems reach as high as 2.8 Billion.
2. What is the pediatric wheelchair market growth rate?
The market is projected to grow at a 7.01% CAGR from 2026 to 2031, reaching 3.08 Billion by 2031. This outpaces historical growth of approximately 5.2%, driven by early intervention and homecare adoption.
3. Which region dominates the pediatric wheelchair market?
North America leads with 39.02% share in 2025, supported by advanced rehabilitation infrastructure and strong reimbursement. Asia-Pacific is the fastest-growing region at 11.72% CAGR through 2031.
4. What are the key segments in the pediatric wheelchair market?
Key segments include product type (manual, powered, specialized), frame type (rigid, foldable, tilt-in-space), application (cerebral palsy, muscular dystrophy, spinal cord injury), and distribution channel (direct, retail, online, hospitals).
5. Who are the leading pediatric wheelchair manufacturers?
Leading manufacturers include Sunrise Medical, Permobil, Invacare, Ottobock, Pride Mobility, Ki Mobility, and R82. Differentiation rests on seating customization, reimbursement expertise, and pediatric clinical validation.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research is built on a 70/30 primary-to-secondary split. We conducted in-depth interviews with stakeholders across the value chain, including raw material suppliers (aluminum and carbon-fiber), specialized pediatric wheelchair producers, seating and component formulators, and global distributors. Decision-makers interviewed included VP-level Sourcing Leads, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of design, procurement, and market access.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
35%
Procurement & Sourcing Leads
30%
Commercial Operations Leads
35%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Specialized Pediatric Wheelchair Producers
40%
Component & Seating Formulators
30%
Global Distributors & Dealers
30%
Secondary Benchmarking & Public Trade Validation
We validated findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized standards bodies including ISO (ISO 7176 wheelchair standards) and national assistive-technology associations. No third-party market research publishers were used as primary sources.
Demand Modeling & Market Sizing Triangulation
We applied simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption) modeling. This triangulation reconciles divergent published estimates by isolating scope differences.
 Pediatric Wheelchair Market