 Calcium Formate Market
: Size, Forecast & Strategy 2026
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 226

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Calcium Formate Market
Srinwanti Kar
Senior Research Analyst

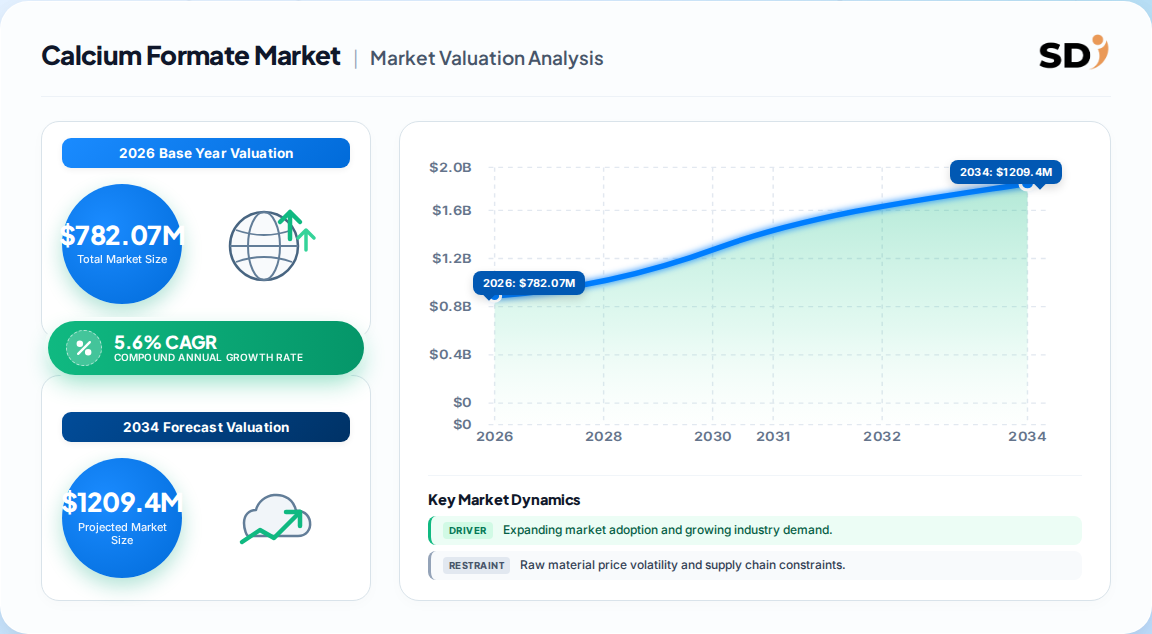
| Year | Market Size |
|---|---|
| 2026 | 782.0 M |
| 2027 | 826.0 M |
| 2028 | 872.0 M |
| 2029 | 921.0 M |
| 2030 | 973.0 M |
| 2031 | 1.030 B |
| 2032 | 1.080 B |

The Calcium Formate Market covers the production, distribution and consumption of calcium formate (the calcium salt of formic acid), a white crystalline powder used chiefly as a concrete accelerator and setting agent, a feed additive and acidifier in animal nutrition, and a pH regulator in leather tanning and textile processing.
This analysis covers industrial-grade and feed-grade calcium formate across construction, animal husbandry, leather and textile, power generation and chemical end uses, spanning all major regions. It includes value and volume demand, pricing dynamics and vendor positioning. This analysis does not cover formic acid or calcium carbonate upstream markets, alternative concrete accelerators such as calcium chloride, or unrelated organic acid salts.
The market is best sized at approximately 782 Million in 2026, rising toward 1.35 Billion by 2036 at a 5.6% CAGR. Published estimates diverge modestly on both base value and horizon, largely because of differing scope definitions.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 782 Million | 2026 | 2036 | 5.6% | Broad multi-application, global | One published estimate |
| 900 Million | 2025 | 2033 | 5.2% | Includes emerging drilling-fluid and de-icing uses | A competing analysis |
| 610 Million | 2023 | 2032 | 5.8% | Construction-weighted, narrower application set | A competing analysis |
| 699 Million | 2023 | 2032 | 5.6% | Grade + application + end-use triangulation | A competing analysis |
Our analysis suggests the 5.6% central figure is the most defensible because four independent publishers converge within 0.6 percentage points despite different base years. This tight band implies underlying demand is genuinely structural rather than cyclical, which is unusual for a construction-linked specialty chemical. The divergence in base value, by contrast, reflects scope breadth more than genuine market disagreement.
The market segments primarily by grade, application and end use, with industrial grade and concrete-related applications anchoring revenue.
| Parent | Children |
|---|---|
| By Grade | Industrial Grade; Feed Grade |
| By Application | Concrete Setting; Feed Additive; Tile & Stone Additive; Leather Tanning; Textile Additive; Drilling Fluids; Flue Gas Desulfurization; Others |
| By End Use | Construction; Animal Husbandry; Leather & Textile; Power Generation; Chemicals; Others |
Industrial grade holds roughly 60% of revenue, but the feed-grade line is the faster-compounding pocket as livestock producers replace antibiotic growth promoters with acidifiers. That asymmetry is the most commercially significant structural fact in the segmentation.
Asia Pacific leads the global Calcium Formate Market with approximately 36.1% of revenue, driven by China's outsized cement production and India's infrastructure buildout. North America and Europe follow, with the US construction complex and European animal-feed regulation shaping distinct demand profiles.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.36% |
| North America | 0.28% |
| Europe | 0.22% |
| Latin America | 0.08% |
| Middle East & Africa | 0.06% |
| Region | Share |
|---|---|
| Asia Pacific | 36% |
| North America | 28% |
| Europe | 22% |
| Latin America | 8% |
| Middle East & Africa | 6% |
This divergence implies a two-speed market: Asia Pacific volumes scale with cement tonnage, while Western demand tracks higher-value feed-grade and performance-additive applications. Vendors must therefore run dual strategies — volume economics in Asia, margin economics in the West.
Construction demand and feed-additive substitution are the twin engines, while raw-material volatility and regulatory compliance costs cap the upside.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Global construction & infrastructure spend | Driver | Strong | Raises cement additive and accelerator volumes |
| Feed-grade antibiotic-alternative shift | Driver | Strong | Acidifier demand in livestock nutrition |
| Urbanization in emerging economies | Driver | Strong | Structural cement consumption growth |
| Leather & textile processing demand | Driver | Moderate | pH regulation in chrome tanning |
| Formic acid / calcium carbonate price volatility | Restraint | Strong | Compresses producer margins |
| Environmental & handling regulation | Restraint | Moderate | Raises compliance and capex |
| Alternative accelerator competition | Restraint | Moderate | Substitution in price-sensitive markets |
The balance favors growth, but quality of growth is uneven. Our reading is that volume expansion is near-certain while margin expansion is not — a distinction that matters enormously for anyone underwriting capacity investments.
The market is moderately concentrated at the top with a long tail of Chinese producers. Perstorp and LANXESS anchor the Western specialty position, while Chinese firms dominate cost-competitive volume.
| Company | Positioning | Notable strength |
|---|---|---|
| Perstorp Holding AB | Specialty, feed & industrial | Application documentation, brand trust |
| LANXESS | Global specialty chemicals | Distribution reach, technical service |
| Geo Specialty Chemicals | Industrial additives | North American footprint |
| Chongqing Chuandong Chemical | Volume producer | Scale and cost position |
| Shandong Baoyuan Chemical | Volume producer | Export competitiveness |
| Zibo Ruibao Chemical | Regional producer | Domestic Chinese demand |
Differentiation rests on application engineering and supply reliability, not product chemistry — calcium formate is fundamentally a commodity molecule. Moats therefore form around qualification cycles with concrete admixture formulators and feed integrators, where switching carries real re-validation cost.
Procurement decisions hinge on grade consistency, purity verification and supplier qualification depth rather than headline price. Feed-grade buyers must confirm regulatory authorization and batch-level traceability, since feed additive compliance varies by jurisdiction. Industrial buyers should scrutinize setting-time performance under low-temperature conditions, where inferior product causes costly rework on poured concrete.
Switching costs are moderate but asymmetric: re-qualifying a supplier with a feed integrator typically takes longer than re-specifying a concrete admixture input. Supply risk concentrates in formic acid availability, so dual-sourcing across regions is prudent. Buyers should also model freight exposure, since calcium formate is a relatively low-value-density product where logistics can erode apparent price advantages.
The balance of evidence favors a steady-growth, infrastructure-anchored market rather than a disruptive one. The 5.2%–5.8% consensus band is unusually tight, which tells us demand is structural and forecast risk is low. The strongest counter-argument is that construction cyclicality could compress the lower end of that band sharply in a downturn — but the feed-grade diversification provides a genuine, if partial, hedge.
Our judgment is that the strategic battleground is not price but qualification. Feed-grade regulation and admixture formulator specifications create sticky, defensible positions that reward patient suppliers. Conversely, pure volume players in Asia face perennial margin compression, and the raw-material volatility challenge is most acute for them.
What would change this conclusion: a sustained collapse in formic acid pricing that commoditizes the feed-grade segment, or a regulatory shift restricting calcium formate in animal feed in a major market. Either would materially reorder the competitive hierarchy.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.6% from 2020-2034 |
| Segmentation |
|
The global Calcium Formate Market is estimated at approximately 782 Million in 2026, with projections reaching roughly 1.35 Billion by 2036. Estimates from different publishers range from about 610 Million to 900 Million depending on base year and scope definition.
Consensus forecasts cluster at 5.6% CAGR, with published estimates spanning 5.2% to 5.8%. The tight convergence reflects structurally driven demand tied to global construction activity and expanding animal feed additive adoption rather than cyclical factors.
Asia Pacific leads with approximately 36.1% of global revenue, driven by China's cement production and India's infrastructure investment. North America and Europe follow, with demand profiles shaped by construction activity and animal feed regulation respectively.
Concrete setting is the largest application at over 25% of revenue, followed by feed additives, tile and stone additives, leather tanning, textile additives, drilling fluids and flue gas desulfurization. Industrial grade accounts for roughly 60% of total revenue.
Key players include Perstorp, LANXESS, Geo Specialty Chemicals, Chongqing Chuandong Chemical, Shandong Baoyuan Chemical and Zibo Ruibao Chemical. Western firms compete on application engineering and service, while Chinese producers lead on scale and cost.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a deliberate 70/30 primary-to-secondary research split. In-depth interviews were conducted across the calcium formate value chain with four company archetypes: upstream formic acid and calcium carbonate suppliers, specialized calcium formate producers, contract formulators and blenders serving admixture and feed customers, and global industrial distributors. Within these organizations we engaged designated decision-makers including Vice Presidents of Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads. This fieldwork captured application-specific performance expectations, qualification timelines and pricing mechanics that published data alone cannot reveal.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| R&D & Technical Directors | 35% |
| Commercial Operations Leads | 30% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Chemical Producers | 40% |
| Specialized Formulators & Blenders | 35% |
| Industrial Distributors & Traders | 25% |
Secondary validation draws exclusively on official and non-commercial sources. We triangulate against UN Comtrade and national customs databases for cross-border flow verification, Eurostat and US ITC trade statistics for regional import-export balances, corporate annual filings and investor presentations for capacity and revenue signals, patent databases for formulation innovation tracking, and recognized technical standards bodies and industry associations for grade and specification frameworks. No competitor market-research publications are used as validation inputs.
We run simultaneous top-down and bottom-up modeling. The top-down track allocates macroeconomic construction and livestock output to calcium formate intensity per application segment. The bottom-up track aggregates manufacturer capacity, realized pricing and end-use consumption estimates. Divergence between the two tracks is reconciled through iterative weighting, producing the final base-year valuation and compound projection.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |