 Correspondence Management System Market
 Outlook 2026
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 180

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Correspondence Management System Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 52.46 B |
| 2026 | 60.33 B |
| 2027 | 69.37 B |
| 2028 | 79.76 B |
| 2029 | 91.71 B |
| 2030 | 105.5 B |
| 2031 | 121.1 B |

The correspondence management system market covers software and services that design, generate, personalize, deliver, and archive regulated customer communications across print, email, web portals, SMS, and chatbots. It replaces manual mail-merge and template sprawl with auditable, data-driven workflows that satisfy retention, accessibility, and consent mandates.
This definition is deliberately narrow: it excludes the underlying CRM, ERP, and core recordkeeping systems with which CCM platforms integrate.
This report covers global correspondence management software and associated professional and managed services, segmented by component, delivery channel, deployment model, organization size, and industry vertical, with a 2020–2031 study period.
This analysis does not cover adjacent document management system spending, enterprise content management platforms, transactional print hardware, or standalone CPaaS messaging infrastructure except where they directly intersect CCM orchestration.
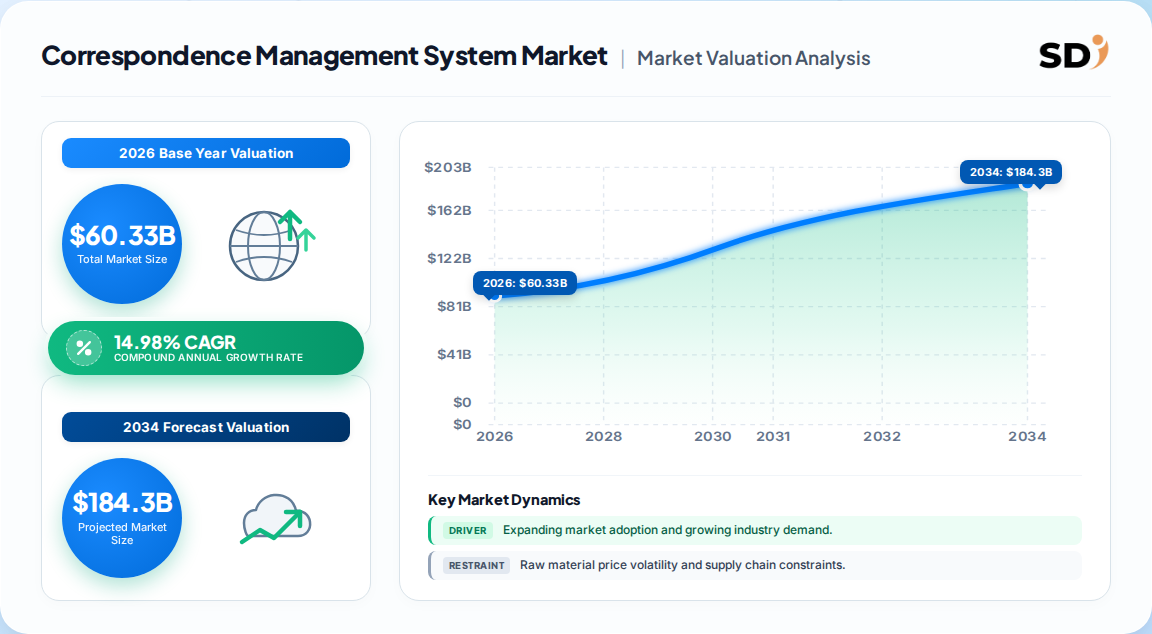
The market is most defensibly sized at USD 60.33 billion for 2026, with a 2031 forecast of USD 121.12 billion. Published estimates diverge materially because analysts bundle services, print fulfillment, and adjacent DMS spend into scope in different proportions.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 60.33 Billion | 2026 | 2031 | 14.98% | Software, services, all delivery channels, all verticals | One published estimate |
| USD 54.67 Billion | 2025 | 2034 | 7.47% | Form-centric (paper, email/fax, web, electronic) with mailroom automation | A competing analysis |
| USD 52.46 Billion | 2025 | 2031 | 14.98% | Same framework as lead estimate, prior base year | One published estimate |
Our analysis favors the 14.98% trajectory rather than the 7.47% alternative. The lower figure appears to weight paper-document and legacy mailroom revenue heavily, a segment we expect to decline as email, RCS, and chatbot channels absorb volume. Notably, the two frameworks agree on the 2025 base within roughly 4%, which implies the divergence is forecast methodology, not current-year measurement.
| Framework | 2025 base | Implied 2031 value | Gap driver |
|---|---|---|---|
| High-growth | USD 52.46 Billion | USD 121.12 Billion | Cloud-native mix shift |
| Conservative | USD 54.67 Billion | Above USD 84 Billion (interpolated) | Paper-era weighting |
Segmentation is component-led: software supplies the recurring license and subscription base, while services capture the integration, template migration, and compliance work that determines whether deployments actually go live.
| Parent Segment | Children |
|---|---|
| Component | Software; Services |
| Delivery Channel | Web-Based; Email-Based; SMS/MMS; Social & Chatbots; Print |
| Deployment Model | On-Premises; Cloud (Public, Hybrid, Private) |
| Organization Size | SMEs; Large Enterprises |
| Industry Vertical | BFSI; Telecom & IT; Healthcare & Life Sciences; Government; Retail; Utilities; Others |
Three structural readouts follow. Software's 62.10% share proves buyers pay for reference platforms, not one-off consulting. Cloud's 68.05% share signals that on-premises CCM is now largely a regulated-niche option. And the 16.05% SME CAGR implies the low-code tier—not enterprise suites—will absorb the next wave of first-time buyers.
North America leads with 35.30% of 2025 share, anchored by mature compliance spending and early cloud adoption. Asia-Pacific is the fastest-growing region at 16.02% CAGR, reflecting digital-government mandates and mobile-first channel usage.
| Region | Market Share (%) |
|---|---|
| North America | 0.36% |
| Europe | 0.28% |
| Asia-Pacific | 0.24% |
| Latin America | 0.07% |
| Middle East & Africa | 0.05% |
| Region | 2025 Share | Growth Outlook |
|---|---|---|
| North America | 35.30% | Mature, compliance-led |
| Europe | 27.00% | Accessibility Act and data residency driven |
| Asia Pacific | 24.00% | Fastest, mobile-first |
| Latin America | 8.00% | Channel-led expansion |
| Middle East & Africa | 5.70% | Government digitization |
The geographic skew carries an operational implication: North American vendors hold pricing power today, but the marginal CCM dollar in 2029 will be decided in Asia-Pacific. Our analysis suggests localization—multilingual templates, local data residency, RCS readiness—will matter more than feature breadth in that contest.
Growth is driven primarily by cloud-native migration (+3.2% CAGR impact) and the personalization imperative (+2.8%), while restrictive up-front implementation costs (-1.4%) and legacy data silos (-1.2%) cap the pace of displacement.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Cloud-native CCM adoption | Driver | Strong | Elastic peak scaling; opex conversion; hyperscaler APIs |
| Automated, personalized communication | Driver | Strong | Real-time data ingestion; measured engagement uplift |
| Regulatory audit mandates | Driver | Strong | Retention, tamper-evidence, accessibility tagging |
| Omnichannel and digital transformation | Driver | Moderate | RCS and chatbot scale; single decision layer |
| AI sentiment and low-code tools | Driver | Moderate | Shorter template cycles; in-flight channel tuning |
| Up-front implementation cost | Restraint | Moderate | Acute in price-sensitive SME segment |
| Data silos and skills shortage | Restraint | Moderate | Legacy integration debt; scarce template talent |
The balance of evidence indicates demand is regulation-anchored, not discretionary. Buyers cannot defer compliance-driven correspondence upgrades the way they can defer analytics projects, which explains why the market compounds near 15% despite implementation friction. The genuine brake is integration talent, not budget.
IBM, Adobe, Open Text, Microsoft, and Rosslyn (enChoice) are the major players in a moderately concentrated field, complemented by specialists such as Hyland, Xerox, Ideagen, and DocPoint Solutions serving vertical niches.
| Vendor | Primary Strength | Typical Buyer | Moats |
|---|---|---|---|
| IBM Corporation | Enterprise content and automation breadth | Large regulated enterprises | Installed base; integration depth |
| Adobe Inc. | Template design and document generation | BFSI, insurance | Design tooling; AEM ecosystem |
| Open Text Corporation | Content cloud and records governance | Government, healthcare | Compliance footprint |
| Microsoft Corporation | Dynamics 365 orchestration and cloud reach | Mid-market to enterprise | Azure economics; bundling |
| Rosslyn / enChoice | CCM specialism and migration services | Insurance, utilities | Template migration expertise |
| Hyland Software | Content platform adjacency | Healthcare, public sector | Vertical workflows |
| Xerox Corporation | Print and mailroom hybrid output | High-volume print operators | Physical-digital bridge |
| Ideagen PLC | Regulated quality documentation | Life sciences | Validation rigor |
Differentiation is compressing at the feature layer and widening at the governance layer. Our analysis suggests API-first entrants are unbundling legacy suites into composable microservices, eroding license economics while leaving audit, retention, and accessibility deep enough that outright replacement remains rare.
Selection criteria should be weighted toward auditability, channel orchestration, and integration surface—not template aesthetics. Buyers should require demonstrable audit trails, version control, tamper-evident archiving, and accessibility conformance before commercial negotiation begins. A rendering demo proves output quality; it proves nothing about retention integrity.
Procurement risk concentrates in migration and switching costs. Legacy template estates are frequently undocumented, and remediation of disclosure language across thousands of templates is where budgets overrun. Contracts should specify template inventory obligations, parallel-run periods, and exit-data portability.
Regulatory exposure is jurisdiction-specific and non-transferable. Retention windows, breach-logging deadlines, and accessibility timelines differ across regimes, so buyers should map obligations to platform configuration rather than assume vendor default templates comply. Hybrid topologies—private nodes for residency, public object storage for archive—are the pragmatic compromise in regulated markets.
Finally, total cost of ownership favors subscription models but only when volume-based rendering charges are stress-tested against peak cycles such as tax season and open enrollment. Fixed-fee assumptions here routinely fail.
The balance of evidence favors the 14.98% growth trajectory and a cloud-first buying posture. Regulation anchors demand, personalization raises willingness to pay, and the SME segment remains structurally underserved—three conditions rarely aligned in enterprise software. The strongest counter-argument is that API-first entrants could commoditize template generation faster than incumbents reprice, compressing license revenue even as volumes rise.
Our judgment is that this commoditization is real but narrow: it attacks output, not governance. Vendors who defend audit, retention, and accessibility depth while exposing composable APIs will hold pricing power; those selling template engines alone will not.
Actionable strategy:
Evidence that would change this conclusion: sustained sub-10% cloud migration rates, or regulatory rollback of retention and accessibility mandates in North America or the EU. While this overview covers market-level dynamics, precise sub-segment forecasting by channel and vertical requires the full report's modeling.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 14.98% from 2020-2034 |
| Segmentation |
|
USD 60.33 billion, according to the leading published estimate, with a forecast of USD 121.12 billion by 2031 at a 14.98% CAGR across all regions and verticals.
Asia-Pacific, at a 16.02% CAGR through 2031, driven by digital-government programs, mobile-first channel behavior, and expanding SME adoption of low-code correspondence platforms.
Software, at 62.10% of 2025 share, followed by services growing at 16.18% CAGR as integration and compliance work expands alongside platform deployments.
Frameworks weight paper-document and mailroom revenue differently; base-year values cluster within roughly 4%, but forecast CAGRs diverge from 7.47% to 14.98% depending on cloud-mix assumptions.
IBM, Adobe, Open Text, Microsoft, and Rosslyn (enChoice), alongside specialists including Hyland, Xerox, Ideagen, and DocPoint Solutions serving regulated verticals.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the correspondence management value chain, including enterprise software producers, systems integrators and template-migration specialists, managed print and mailroom service providers, cloud infrastructure partners, and regulated end-user organizations. Decision-maker designations interviewed included VP-level Sourcing and Procurement leads, Heads of Customer Communications and R&D/Product Directors, Chief Compliance and Information Governance Officers, and Commercial Operations Leads responsible for channel mix and cost-per-communication.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| Customer Communications & Product Directors | 30% |
| Compliance & Information Governance Officers | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Enterprise Software Producers | 40% |
| System Integrators & Migration Specialists | 30% |
| Managed Print & Mailroom Providers | 18% |
| Cloud Infrastructure Partners | 12% |
Secondary validation draws on official multilateral and standards sources—UN Comtrade and WTO services trade data, US ITC and Eurostat ICT services statistics—alongside corporate annual filings (10-K, SEC disclosures, investor presentations), patent databases for document-generation and workflow automation, and recognized non-profit standards bodies including ISO technical committees on records management and accessibility conformance frameworks.
Sizing triangulates Top-Down allocation from macroeconomic ICT and enterprise software spend against Bottom-Up modeling of vendor revenue, seat and volume pricing, and end-use communication volumes by channel. Divergent published CAGRs are reconciled by isolating scope differences in paper, print, and services inclusion.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up revenue and volume triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & channel elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border services trade & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |