 Us Women Grooming Market
 Outlook 2025
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 236

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Women Grooming Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 68.20 B |
| 2025 | 72.77 B |
| 2026 | 77.64 B |
| 2027 | 82.84 B |
| 2028 | 88.39 B |
| 2029 | 94.31 B |
| 2030 | 100.6 B |

The U.S. women's grooming market covers retail consumer goods used by women to maintain hygiene, appearance, and wellbeing: skincare, haircare, oral care, color cosmetics, shower and bath, and fragrances. It spans mass and premium price tiers, sold through supermarkets, specialty beauty stores, pharmacies, and online/DTC channels.
This analysis covers U.S. retail sales of women's skincare, haircare, oral care, color cosmetics, shower and bath, and perfume/fragrance products across mass, premium, and prestige tiers, through all major distribution channels. Revenue reflects retail value including sales taxes. This analysis does not cover salon and spa services, professional-only channel products, medical/aesthetic procedures, beauty-tech hardware, or men's and unisex grooming adjacencies.
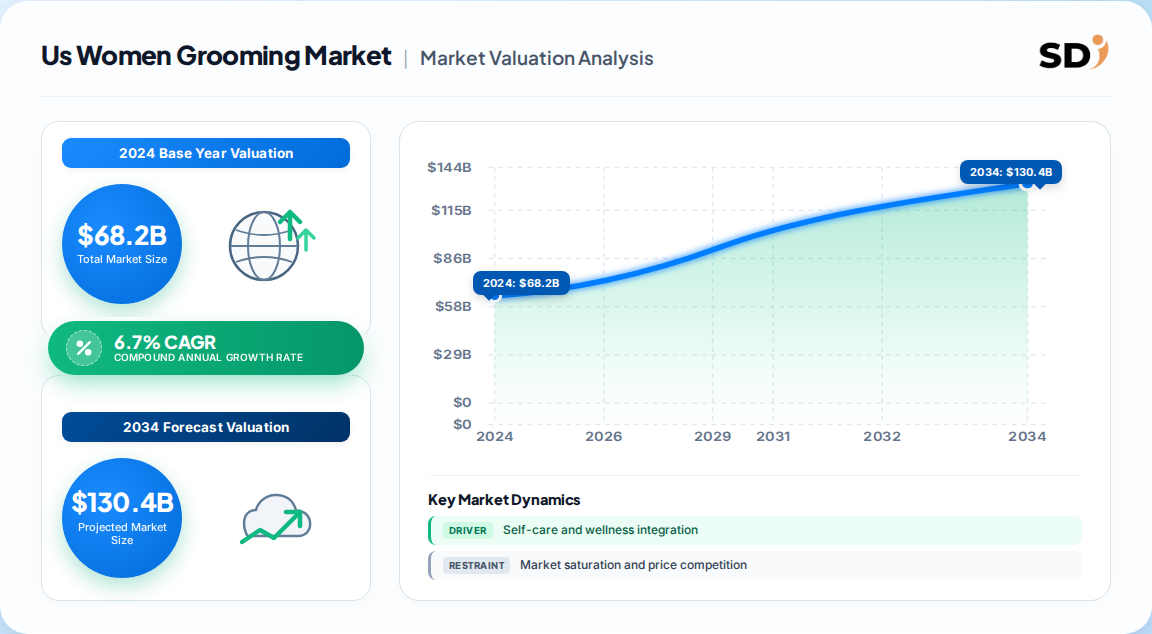
One published estimate values the U.S. women's grooming market at 68.20 Billion in 2024, growing at 6.7% CAGR through 2030. A broader-scope analysis puts 2024 at 74.68 Billion with a 7.41% CAGR to 2035. The divergence is definitional, not directional.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 68.20 Billion | 2024 | 2030 | 6.7% | Six product categories; all retail channels; excludes beauty tech | One published estimate |
| 74.68 Billion | 2024 | 2035 | 7.41% | Broader basket including personal hygiene and premium beauty equipment | A competing analysis |
| 55.43 Billion | 2024 | 2030 | 6.85% | Tighter basket: skincare, haircare, hair removal, cosmetics, hygiene | A third-party research release |
| 163.92 Billion | 2035 | 2035 | 7.41% | Terminal value from broader-scope estimate | Derived from competing analysis |
| ~133.05 Billion | 2026 | 2031 | 2.76% | All beauty and personal care incl. men's, unisex, beauty tech | Public market tracker |
Our analysis suggests the 68.20 Billion figure is the most defensible base for a women-specific grooming mandate: it avoids double-counting men's and unisex lines and excludes salon services that are not retail-purchased. The higher 74.68 Billion number is more useful as an upper-bound scenario for investors underwriting premium and wellness-adjacent adjacencies. The 2.76% CAGR visible in the all-gender beauty tracker is not a contradiction — it reflects a mature, broader basket where women's grooming is a faster-growing subset.
Segment structure is product-led, with skincare the anchor and color cosmetics the growth engine. Distribution segmentation matters because channel mix is shifting faster than product mix, reshaping margin pools across the value chain.
| Parent Segment | Children | 2024 Position |
|---|---|---|
| By Product | Skin Care, Hair Care, Oral Care, Color Cosmetics, Shower & Bath, Perfume/Fragrances | Skincare ~32.6% share; color cosmetics 8.3% CAGR |
| By Price Range | Mass, Premium | Premium outpacing mass on value growth |
| By Distribution Channel | Hypermarkets & Supermarkets, Specialty Beauty Stores, Pharmacies & Drugstores, Online/E-Commerce, Others | Supermarkets lead volume; online fastest-growing |
The West is the fastest-growing U.S. region, led by California, Washington, and Oregon, where clean-beauty, sustainability, and wellness priorities are most pronounced. The South remains the largest volume region on population and store density, while the Northeast leads on premium and prestige spend per capita.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.21% |
| South | 0.26% |
| West | 0.24% |
| Midwest | 0.18% |
| Pacific Northwest | 0.11% |
| Parent | Children |
|---|---|
| Northeast | New York, Massachusetts, Pennsylvania, New Jersey |
| South | Florida, Texas, Georgia, North Carolina |
| West | California, Arizona, Nevada, Colorado |
| Midwest | Illinois, Ohio, Michigan, Minnesota |
| Pacific Northwest | Washington, Oregon, Idaho |
Regional data is unevenly disclosed. The West's growth leadership is well-attested; precise state-level revenue splits are not consistently published, which is why the full report triangulates regional consumption through retail scanner data, e-commerce fulfilment geography, and Census retail trade benchmarks rather than relying on a single regional table.
The primary driver is the fusion of grooming with broader wellness and self-care spending, amplified by social media discovery and teen spending re-acceleration. Restraints are structural: market saturation, ingredient-transparency compliance costs, and counterfeit risk in online channels.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Self-care and wellness integration | Driver | High | Grooming reclassified as wellbeing spend; lifts routine frequency and basket size |
| Social media and influencer discovery | Driver | High | TikTok/Instagram shorten discovery-to-purchase cycles, especially for indie brands |
| Teen spending re-acceleration | Driver | Medium-High | Teen makeup spend +32% YoY; skincare +11% YoY (2023 survey) |
| Clean and sustainable formulation demand | Driver | High | Millennial/Gen Z preference for transparent, eco-friendly ingredients |
| E-commerce and DTC expansion | Driver | High | Personalized shopping, subscription models, direct consumer data |
| Category saturation and price competition | Restraint | High | High marketing spend; difficulty differentiating in skincare and cosmetics |
| Ingredient transparency and regulatory compliance | Restraint | Medium | Higher formulation and labeling costs, disproportionately hitting small brands |
| Counterfeit and grey-market products | Restraint | Medium | Erodes trust and premium pricing in online channels |
Our analysis suggests the driver-restraint balance favors growth, but the composition of growth is shifting. Volume growth is modest; value growth is being carried by premiumization and routine expansion. This implies vendors relying on unit expansion in mass tiers face the weakest economics in the market. The second-order effect is consolidation pressure on mid-tier brands that lack either a clean-beauty story or a price advantage.
The U.S. women's grooming market is led by diversified global consumer goods groups with multi-category portfolios, contested by fast-scaling celebrity, indie, and DTC brands that win on authenticity and community.
| Company | Portfolio Strength | Channel Position | Strategic Moat |
|---|---|---|---|
| Procter & Gamble | Haircare, skincare, oral care | Mass and online | Scale, brand equity, retail relationships |
| L'Oréal | Skincare, haircare, cosmetics | Mass to prestige | R&D pipeline, category breadth |
| Unilever | Personal care, haircare, skincare | Mass and emerging channels | Global supply chain, value pricing |
| Estée Lauder | Prestige skincare, cosmetics, fragrance | Specialty and online | Prestige brand portfolio, loyalty |
| Coty | Color cosmetics, fragrance | Mass to prestige | Licensed brands, fragrance scale |
| Johnson & Johnson | Skincare, oral care | Mass and pharmacy | Dermatology heritage, trust |
| Beiersdorf | Skincare | Mass and pharmacy | Dermo-cosmetic credibility |
| Shiseido | Skincare, cosmetics | Prestige and specialty | J-beauty formulation expertise |
Differentiation is increasingly narrative-led rather than formulation-led. Celebrity-backed brands and DTC challengers have compressed the time from trend to shelf, forcing incumbents to shorten innovation cycles and acquire rather than build in growing niches. The strongest moats remain distribution scale and dermatological credibility; the weakest positions are undifferentiated mid-tier brands with neither.
Procurement and market-entry decisions hinge on four criteria: segment growth durability, channel margin structure, regulatory compliance burden, and brand substitutability. Skincare and color cosmetics offer the strongest growth, but skincare carries higher formulation and claims-substantiation risk under FDA oversight, while color cosmetics carries faster trend obsolescence.
Channel choice is the highest-leverage decision. Online and DTC channels offer richer consumer data and better margin control but require sustained acquisition spend; supermarkets and specialty stores offer reach but compress margin and limit brand storytelling. Switching costs for consumers are low in mass tiers and high in prestige and dermo-cosmetic tiers, which is why premium brands retain pricing power during downturns.
Compliance risk is concentrated in clean-beauty claims, ingredient traceability, and counterfeit exposure in third-party online marketplaces. Buyers should treat supplier transparency and channel authorization as selection criteria, not afterthoughts. Precise sub-segment margin and forecast data require the full report's bottom-up channel models.
The balance of evidence favors a premium-and-specialist positioning over broad mid-tier participation. The market is growing at a credible 6.7% base-case CAGR, but growth is concentrated in skincare, color cosmetics, and online channels, while mass and mid-tier generalists face saturation-driven margin compression. The strongest counter-argument is that mass-tier volume resilience during economic softness could reward scale players more than specialists — but even there, value growth is flowing to private label and clean-positioned mass brands, not undifferentiated incumbents.
Actionable strategy for operators and investors:
What would change our conclusion: a sustained reversal in teen and Gen Z spending, a sharp regulatory tightening on clean-beauty claims that raises compliance costs for specialists, or evidence that mass-tier volume growth re-accelerates faster than premium. Absent those signals, the premium-specialist thesis holds.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.7% from 2020-2034 |
| Segmentation |
|
One published estimate values the U.S. women's grooming market at 68.20 Billion in 2024. Broader-scope analyses place it near 74.68 Billion. The difference is definitional, driven by whether personal hygiene and premium beauty equipment are included.
The base-case CAGR is 6.7% from 2025 to 2030. Broader-scope estimates cite 7.41%, and tighter-basket estimates cite 6.85%. All three point to mid-single-digit to low-double-digit value growth driven by premiumization.
Skincare held roughly 32.6% of 2024 revenue, making it the largest segment. Color cosmetics is the fastest-growing at an 8.3% CAGR, driven by celebrity brands and social media discovery.
The West is the fastest-growing region, led by California, Washington, and Oregon. Clean-beauty demand, sustainability priorities, and beauty-tech startups concentrate there. The South remains the largest volume region on population and store density.
Procter & Gamble, L'Oréal, Unilever, Estée Lauder, Coty, Johnson & Johnson, Beiersdorf, and Shiseido lead the market. Fast-scaling celebrity, indie, and DTC brands contest share in skincare and color cosmetics.
Online and DTC channels are the fastest-growing route to market. Online is expected to approach 60% of U.S. beauty and personal care revenue by 2026, driven by convenience, personalization, and subscription models.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research applies a 70/30 primary-to-secondary split. In-depth interviews were conducted across the value chain with raw material and ingredient suppliers, specialized formulators and contract manufacturers, brand owners and marketers, and national distributors and retail buyers. Decision-maker participants included VP-level Sourcing leads, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads, ensuring both technical and commercial perspectives inform every forecast.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement | 30% |
| Heads of R&D & Formulation | 30% |
| Technical Directors | 20% |
| Commercial Operations Leads | 20% |
| Company Type | Representation (%) |
|---|---|
| Ingredient & Raw Material Suppliers | 30% |
| Contract Formulators & Manufacturers | 30% |
| Brand Owners & Marketers | 25% |
| Distributors & Retail Buyers | 15% |
We cross-validate primary inputs against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and 10-K disclosures, patent and trademark databases, and recognized non-profit technical standards and industry associations. Competitor market research publications are never used as validation sources.
Market sizing triangulates Top-Down macroeconomic allocation (GDP, personal consumption expenditure, category share of wallet) with Bottom-Up demand modeling (manufacturer capacity, SKU-level pricing, retail scanner velocity, and end-use consumption). Divergences between the two models are reconciled through channel-level interviews.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |