 Protein Purification Isolation Market
: 2033 Outlook
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 218

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Protein Purification Isolation Market
Srinwanti Kar
Senior Research Analyst

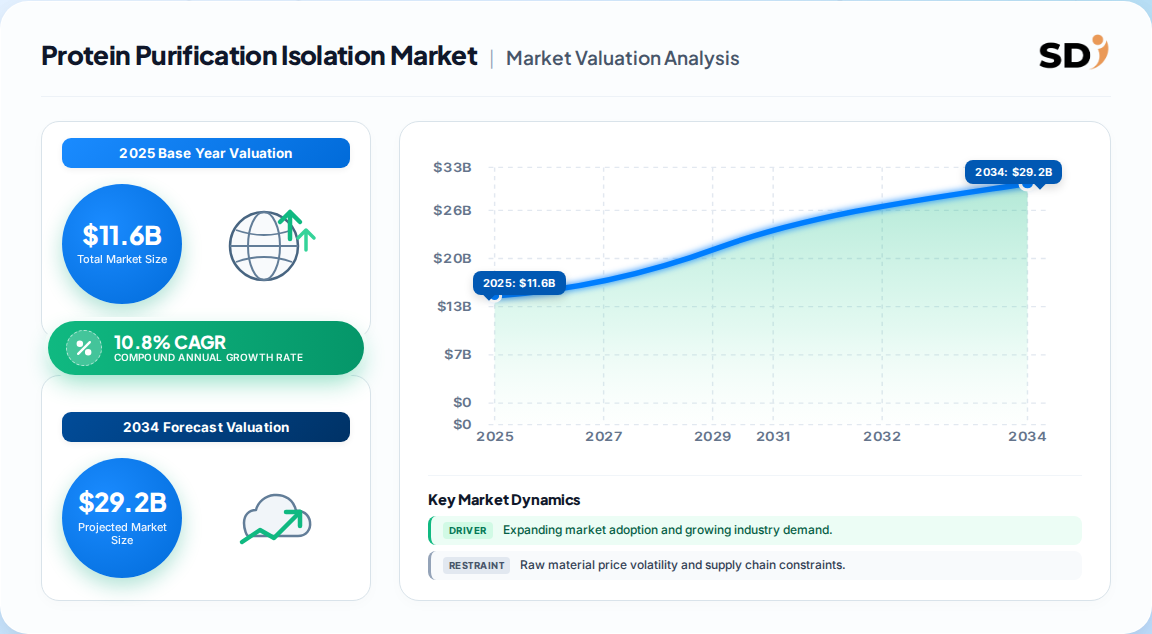
| Year | Market Size |
|---|---|
| 2025 | 11.60 B |
| 2026 | 12.85 B |
| 2027 | 14.24 B |
| 2028 | 15.78 B |
| 2029 | 17.48 B |
| 2030 | 19.37 B |
| 2031 | 21.46 B |

The protein purification and isolation market encompasses instruments, consumables, and technologies used to separate target proteins from complex biological mixtures while preserving structure and activity. It serves biopharmaceutical manufacturing, drug discovery, diagnostics, proteomics research, and academic laboratories through chromatography, filtration, precipitation, and electrophoresis workflows.
This report covers global demand for protein purification and isolation across instruments and consumables, by technology, application, and end user, with segment and regional forecasts through 2035. This analysis does not cover upstream cell culture media, fermentation equipment, analytical characterization instruments, or clinical diagnostic testing services as standalone markets.
The market is estimated at roughly 11.6 Billion in 2025, with forecasts converging on a 10.2–10.8% CAGR through the mid-2030s. Published estimates differ primarily because of definitional scope, not demand disagreement.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 10.4 Billion | 2024 | 2033 | 10.8% | Instruments + consumables, global | One published estimate |
| 12.51 Billion | 2026 | 2035 | 10.14% | Includes broader technology set | A competing analysis |
| 11.6 Billion | 2025 | 2035 | 10.8% | Core purification and isolation | A third published estimate |
| 11.7 Billion | 2025 | 2034 | 10.2% | Type, technology, application scope | A fourth published estimate |
The 11.6 Billion figure for 2025 is the most defensible anchor because it sits between narrow instrument-only estimates and broader workflow definitions. Our analysis suggests the 10.8% CAGR consensus is credible given biologics pipeline expansion and proteomics investment, though upside exists if continuous manufacturing adoption accelerates faster than currently observed.
Segments are defined by product, technology, application, and end user. Consumables and chromatography consistently lead their respective parent categories across every published source.
| Parent | Children |
|---|---|
| By Product | Instruments, Consumables (resins, columns, kits, buffers, filters) |
| By Technology | Chromatography, Membrane Filtration, Ultrafiltration, Precipitation, Electrophoresis, Western Blotting & Dialysis |
| By Application | Protein-Protein Interaction Studies, Drug Screening & Development, Biomarker Discovery, Diagnostics |
| By End User | Academic & Research Institutes, Pharmaceutical & Biotech Companies, Hospitals, CROs & Clinical Laboratories |
Consumables represent 62–64% of product revenue because purification is a recurring operational expense rather than a one-time capital purchase. Chromatography's dominance reflects its unmatched selectivity in high-purity biologics production, where regulatory scrutiny is most intense.
North America leads with approximately 39% revenue share, driven by concentrated biopharma manufacturing, NIH-funded research, and advanced proteomics infrastructure. Asia-Pacific is the fastest-growing region at a double-digit CAGR.
| Region | Market Share (%) |
|---|---|
| North America | 0.39% |
| Europe | 0.25% |
| Asia-Pacific | 0.23% |
| Latin America | 0.07% |
| Middle East & Africa | 0.06% |
| Region | Share (approx.) |
|---|---|
| North America | 39% |
| Europe | 25% |
| Asia-Pacific | 23% |
| Latin America | 7% |
| Middle East & Africa | 6% |
Our analysis suggests Asia-Pacific's growth is structurally underappreciated: domestic biologics manufacturing mandates in China and India, combined with biosimilar development, create a demand pool that Western vendors cannot serve with legacy pricing models.
Biologics expansion and proteomics investment are the dominant growth engines, while high consumable costs and protein stability challenges constrain adoption. The net balance favors expansion through 2035.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Biopharmaceutical & biologics manufacturing expansion | Growth | High | Sustained demand for downstream purification of mAbs, recombinant proteins, vaccines |
| Plasma biomarker and proteomics research | Growth | High | Trace-level protein isolation requires sensitive, scalable purification platforms |
| Government R&D investment (e.g., NIH, NSF programs) | Growth | Medium-High | Funds infrastructure, automation, and high-throughput workflows |
| High resin and consumable costs | Restraint | High | Pressures operating budgets, especially for smaller labs and cost-sensitive manufacturers |
| Protein stability during processing | Restraint | Medium | Aggregation and denaturation reduce yield, complicating multi-step workflows |
| Regulatory compliance complexity | Restraint | Medium | Biologics manufacturing controls raise validation and documentation burden |
The balance of evidence favors drivers over restraints. High consumable costs are a genuine margin issue, but they also create stickiness: once a validated purification workflow is embedded in a regulatory filing, switching costs are substantial. This dynamic favors incumbents with installed-base economics.
The competitive landscape is moderately concentrated, with Thermo Fisher Scientific, Danaher, and Merck KGaA as the most frequently cited leaders, followed by Bio-Rad, Agilent, and QIAGEN.
| Company | Primary positioning | Notable strength |
|---|---|---|
| Thermo Fisher Scientific | Broad portfolio across instruments and consumables | Scale and workflow integration |
| Danaher (Cytiva) | Chromatography and bioprocessing | Bioprocess installed base |
| Merck KGaA | Consumables, resins, filtration | Life-science reagent depth |
| Bio-Rad Laboratories | Electrophoresis, chromatography | Research-lab penetration |
| Agilent Technologies | Analytical and purification instrumentation | Technology integration |
| QIAGEN | Sample preparation and automation | Automated workflows |
Differentiation rests on workflow breadth and regulatory validation support rather than raw instrument specification. Our analysis suggests the strongest moats belong to vendors whose consumables are embedded in approved biologics manufacturing processes, where requalification costs deter switching.
Buyers should prioritize binding capacity, recovery yield, scalability, and regulatory documentation over upfront price. Procurement risk concentrates in single-source resin dependencies and lead-time volatility, so dual-sourcing high-use consumables is prudent for any GMP-adjacent operation.
Switching costs are highest where purification steps appear in regulatory filings; requalification can consume months and significant validation budgets. For research buyers, switching is cheaper but reproducibility risk rises. Operators should also model total cost of ownership, since consumables often exceed instrument capital cost over a three-to-five-year horizon.
Automation and single-use adoption change the procurement calculus: they reduce labor and turnaround time but increase dependence on vendor-specific consumable ecosystems. Buyers should negotiate multi-year supply agreements with capacity guarantees before committing to automated platforms.
The balance of evidence favors a constructive outlook: the 10.8% CAGR consensus is credible, and the market's consumable-heavy structure provides revenue durability that instrument-led sectors lack. The strongest counter-argument is that high consumable costs could push smaller labs toward alternative separation methods or budget-constrained deferrals, but this is unlikely to materially dent aggregate growth given biopharma's dominant spending share.
Our analysis suggests the most underappreciated strategic dynamic is the convergence of automation and regulatory validation. Vendors that pair automated purification platforms with documentation packages that simplify regulatory filings will capture disproportionate share in the biopharma segment, where compliance time, not reagent price, is the true bottleneck.
What would change this conclusion: a sustained slowdown in biologics approvals, aggressive regulatory harmonization that lowers requalification barriers, or a disruptive membrane-based technology achieving GMP adoption at scale. Any of these would compress the premium currently enjoyed by chromatography incumbents.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.8% from 2020-2034 |
| Segmentation |
|
The market was valued at approximately 11.6 Billion in 2025 and is forecast to reach 32.3 Billion by 2035, growing at a 10.8% CAGR. Estimates vary by definitional scope, with some analyses placing 2026 revenue near 12.5 Billion.
Consumables lead with roughly 62–64% of revenue, driven by recurring demand for resins, columns, buffers, and kits. Chromatography is the leading technology, and protein-protein interaction studies dominate applications.
Asia-Pacific is the fastest-growing region, supported by expanding biotechnology industries, biosimilar development, and rising research funding. North America remains the largest market at approximately 39% share.
Key vendors include Thermo Fisher Scientific, Danaher, Merck KGaA, Bio-Rad Laboratories, Agilent Technologies, and QIAGEN. Competition centers on workflow breadth, automation, and regulatory validation support.
Growth is driven by biopharmaceutical and biologics manufacturing expansion, plasma biomarker and proteomics research, and government R&D investment. High consumable costs and protein stability challenges are the primary restraints.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is built on a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the purification value chain, including raw material and resin suppliers, specialized consumable producers, contract manufacturing organizations, and global distributors. Decision-makers interviewed included VP-level Sourcing executives, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of both technical and commercial demand signals.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 30% |
| Regulatory Affairs Managers | 20% |
| Commercial Operations Leads | 10% |
| Company Type | Representation (%) |
|---|---|
| Resin & Consumable Producers | 40% |
| Instrument Manufacturers | 30% |
| Contract Manufacturers & CROs | 20% |
| Distributors & Suppliers | 10% |
We validated demand estimates against official multilateral databases including UN Comtrade, WTO trade statistics, US ITC data, and Eurostat. Corporate annual filings (10-K and SEC submissions), investor presentations, patent databases, and recognized technical standards from industry associations were used to corroborate capacity, pricing, and adoption trends.
We apply simultaneous top-down and bottom-up modeling. Top-down allocation draws on macroeconomic and life-science segment expenditure; bottom-up modeling uses manufacturer capacity, product pricing, and end-use consumption patterns. Divergences between approaches are reconciled through segment-level weighting.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |