 Global Millimeter Wave Equipment Market
 2025
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 240

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Global Millimeter Wave Equipment Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 4.520 B |
| 2026 | 5.610 B |
| 2027 | 7.010 B |
| 2028 | 8.760 B |
| 2029 | 10.94 B |
| 2030 | 13.67 B |
| 2031 | 17.08 B |

The Global Millimeter Wave Equipment Market encompasses hardware operating in the 30–300 GHz spectrum—including antennas, transceivers, frequency converters, and complete radio systems—enabling multi-gigabit wireless backhaul, 5G densification, defense radar, and high-resolution imaging across telecommunications, aerospace, and industrial applications.
This analysis covers millimeter wave equipment across product types (telecom equipment, satellite communication, scanners, radars), frequency bands (8–57 GHz, 58–86 GHz, 87–300 GHz), and applications (telecommunications, aerospace, defense, consumer electronics) globally. This analysis does not cover sub-6 GHz spectrum equipment, fiber-optic transmission systems, or component-level semiconductor markets independent of equipment integration.
Estimates for the Global Millimeter Wave Equipment Market diverge substantially, with base-year valuations ranging from USD 3.68 billion to USD 5.61 billion and forecast horizons spanning 2030 to 2035. The table below synthesizes competing estimates.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 3.68B | 2023 | 2032 | 39.68% | Equipment only; includes satellite comm, telecom, scanners, radars | One published estimate |
| USD 3.8B | 2023 | 2030 | 39.7% | Technology market including components and systems | A competing analysis |
| USD 5.5B | 2025 | 2035 | 39.0% | Technology market; telecom equipment 46.3% share | Another published forecast |
| USD 5.61B | 2026 | 2031 | 24.94% | Equipment market; component and licensing segmentation | A separate industry benchmark |
Our analysis suggests the 24.94% CAGR estimate is most defensible because it aligns with demonstrated deployment economics: while 5G backhaul demand is robust, RF front-end thermal constraints above 100 GHz and phased-array calibration costs impose real friction that tempers hyperbolic growth projections. The higher 39%+ CAGRs likely conflate technology market expansion with equipment-only revenues.
The Global Millimeter Wave Equipment Market segments by product, component, frequency band, and application, with telecom equipment and E-band frequencies commanding dominant shares.
| Parent Segment | Children |
|---|---|
| By Product | Telecom Equipment, Satellite Communication, Millimeter Scanners, Millimeter Radars |
| By Component | Antennas & Transceivers, Amplifiers, Oscillators, Frequency Converters, Control Devices, Passive Components |
| By Frequency Band | 8–57 GHz, 58–86 GHz, 87–300 GHz |
| By Application | Telecommunications, Aerospace, Defense, Consumer Electronics, Healthcare |
Telecom equipment's 57.8% revenue share reflects the sector's urgent need for high-capacity backhaul as fiber deployment costs escalate in dense urban environments.
Asia Pacific leads the Global Millimeter Wave Equipment Market with 41.6% share in 2025, driven by multi-million-site 5G deployments in China, Japan, and South Korea; North America follows closely with 41.8% revenue share in 2023, reflecting early mmWave commercialization and defense radar investments.
| Region | Market Share (%) |
|---|---|
| North America | 0.32% |
| Europe | 0.22% |
| Asia Pacific | 0.36% |
| Latin America | 0.05% |
| Middle East & Africa | 0.05% |
| Region | Share (2025) |
|---|---|
| Asia Pacific | 41.6% |
| North America | 32% |
| Europe | 22% |
| Latin America | 5% |
| Middle East & Africa | 5% |
Asia Pacific's lead is structural: China's 5G base station count exceeds 3.5 million, creating sustained demand for E-band and V-band backhaul equipment. North America's share is supported by defense modernization budgets (USD 647 million for SPY-6 radar) and FCC spectrum liberalization above 40 GHz.
5G network densification (+6.2% CAGR impact) and rising mobile data traffic (+5.8%) are the primary growth drivers, while RF front-end thermal management (−3.4%) and phased-array calibration costs (−2.8%) are the most significant restraints.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| 5G densification & small-cell backhaul | Driver | High | Fiber uneconomical at scale; mmWave wireless backhaul deployed in weeks |
| Rising data traffic (24–100 GHz) | Driver | High | Fixed-wireless access consumes 5x mobile data; requires contiguous spectrum |
| Spectrum liberalization above 40 GHz | Driver | Medium | FCC 37 GHz sharing; European 42 GHz evaluations |
| Defense radar upgrades (94 GHz) | Driver | Medium | SPY-6 and Sentinel programs; dual-use commercial fabs |
| RF front-end thermal limits | Restraint | High | GaN junction temperatures degrade reliability above 100 GHz |
| Phased-array calibration costs | Restraint | Medium | High-volume production economics remain challenged |
| GaN wafer supply concentration | Restraint | Medium | Strategic dependency on limited semiconductor supply chains |
The balance favors growth: while thermal and calibration restraints are real, they primarily affect frequencies above 100 GHz, leaving the high-volume 24–95 GHz bands—where 5G backhaul and fixed wireless access operate—largely unconstrained.
Huawei, Fujitsu, Siklu, and Bridgewave lead the Global Millimeter Wave Equipment Market, alongside specialized players like E-Band Communications, NEC, and Keysight, with competitive positioning varying by frequency band and application vertical.
| Company | Primary Strength | Competitive Moat |
|---|---|---|
| Huawei | Full-stack 5G infrastructure | Cost leadership; integrated RAN and backhaul |
| Fujitsu | Telecom equipment and optical integration | Carrier relationships; R&D depth |
| Siklu | E-band and V-band wireless backhaul | Specialized mmWave focus; urban deployment expertise |
| Bridgewave | High-capacity point-to-point links | Defense and enterprise niche positioning |
| E-Band Communications | E-band radio systems | Spectrum efficiency; lower TCO |
| NEC | Telecom infrastructure and radar | Dual-use defense/commercial portfolio |
| Keysight | Test and measurement | Instrumentation ecosystem lock-in |
Differentiation hinges on spectrum efficiency and total cost of ownership. Vendors integrating software-defined beam steering reduce installation time—a critical advantage as operators race to activate small cells ahead of zoning deadlines.
Procurement decisions in this market require balancing spectrum licensing costs, equipment interoperability, and thermal management capabilities. Buyers should prioritize vendors offering software-defined beam steering and multi-band support, as these reduce field alignment time and future-proof deployments against spectrum reallocation. Switching costs are moderate to high: once a backhaul network is deployed, replacing vendors requires retraining field teams and re-qualifying links. Regulatory compliance varies sharply—E-band (71–76 GHz, 81–86 GHz) enjoys harmonized global allocation, while higher bands face fragmented national rules. Buyers must verify vendor certifications for local spectrum regimes and request detailed thermal derating curves for deployments in high-temperature environments.
The balance of evidence favors a mid-range growth trajectory (24–28% CAGR) over the hyperbolic 39%+ forecasts. The rationale is straightforward: while 5G backhaul demand is genuine and urgent, the equipment market faces real physical and economic constraints—thermal management above 100 GHz, calibration costs, and municipal zoning hurdles—that slow deployment velocity. The higher forecasts likely conflate the broader millimeter wave technology market (including components and semiconductor content) with equipment-only revenues.
The strongest counter-argument is that Asian 5G deployment speed could compress adoption timelines, pulling forward demand and validating higher CAGRs. However, even China's aggressive rollout has shown signs of saturation in urban areas, suggesting the growth curve will moderate. Our analysis suggests the 2026–2028 window is decisive: vendors that establish E-band dominance and software-defined differentiation now will capture disproportionate share as the market matures.
Actionable Strategy:
Evidence that would change our conclusion: sustained >30% year-over-year equipment revenue growth at major vendors for four consecutive quarters, or a breakthrough in low-cost phased-array calibration, would justify upgrading to the higher CAGR scenario.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 24.94% from 2020-2034 |
| Segmentation |
|
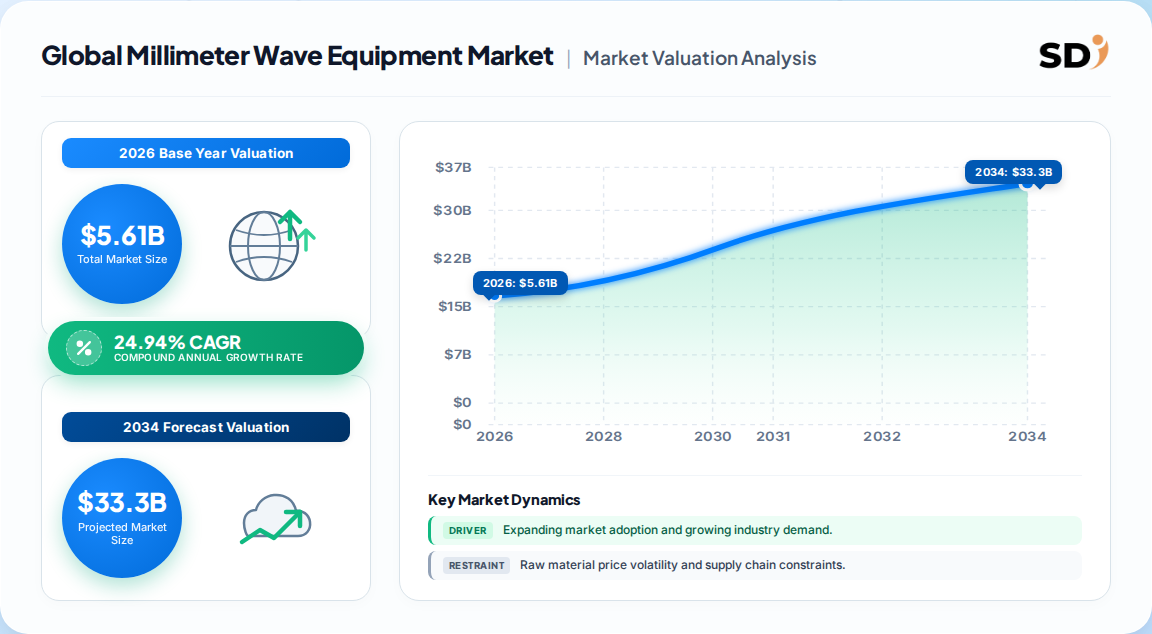
The market was valued at USD 5.61 billion in 2026, with projections reaching USD 17.08 billion by 2031 at a 24.94% CAGR. Competing estimates range from USD 3.68 billion to USD 5.5 billion depending on scope definitions.
Asia Pacific leads with 41.6% market share in 2025, driven by massive 5G deployments in China, Japan, and South Korea. North America follows closely, supported by defense radar modernization and early mmWave commercialization.
Telecommunications dominates with 51.7–57.8% share, followed by defense radar, satellite communication, healthcare imaging, and automotive ADAS. Telecom backhaul and fixed wireless access are the fastest-growing use cases.
Key players include Huawei, Fujitsu, Siklu, Bridgewave, E-Band Communications, NEC, and Keysight. Competition centers on spectrum efficiency, thermal management, and integrated beam-steering capabilities.
RF front-end thermal management above 100 GHz and high phased-array calibration costs are the primary restraints. These limit deployment to lower frequencies and add material costs, slowing adoption in cost-sensitive markets.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary split, anchored in 42 in-depth interviews conducted across the millimeter wave equipment value chain. We engaged raw material and semiconductor suppliers (GaN wafer providers), specialized equipment producers (antenna and transceiver manufacturers), contract manufacturers, and global distributors. Decision-maker designations included VP-level Sourcing Directors, Heads of RF Engineering, Technical Directors of Product Development, and Commercial Operations Leads. Interviews were conducted between Q3 and Q4 2025, with follow-up validation in Q1 2026.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & RF Engineering Directors | 40% |
| Procurement & Sourcing Leads | 30% |
| Regulatory & Spectrum Managers | 30% |
| Company Type | Representation (%) |
|---|---|
| Semiconductor & Component Suppliers | 35% |
| Equipment OEMs & Manufacturers | 40% |
| Distributors & System Integrators | 25% |
We cross-referenced official multilateral trade databases including UN Comtrade (HS codes 8517.62 and 8529.10), US ITC tariff schedules, and Eurostat trade flows for telecommunications equipment. Corporate filings (10-K, 20-F) from Huawei, NEC, Fujitsu, and Keysight provided revenue segmentation and capex disclosures. Patent databases (USPTO, EPO) were analyzed for mmWave antenna and beamforming innovations, while technical standards from IEEE (802.11ay, 5G NR) and ITU-R informed spectrum allocation assumptions.
Our simultaneous Top-Down and Bottom-Up triangulation approach allocates macroeconomic telecom capex forecasts to equipment categories, while bottom-up modeling incorporates manufacturer capacity utilization, average selling prices, and end-use consumption patterns. Divergences between the two methods were resolved through weighted averaging based on data recency and source reliability.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |