Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Super Junction MOSFET Market: Size, CAGR & Outlook 2025
Super Junction Mosfet Market
Super Junction MOSFET Market: Size, CAGR & Outlook 2025
Super Junction Mosfet Market by Type (Through Hole Type (THT), Surface Mount Type (SMT)), by Voltage (High Voltage (>600V), Low Voltage (<600V)), by Technology (Conventional Power MOSFET, Multiple-Epitaxy, Deep-Trench), by Material (Substrate, Transition Layer, Electrode), by Application (Energy & Power, Consumer Electronics, Inverter & UPS, Electric Vehicle, Industrial Systems, Others), by Asia-Pacific (China, Japan, South Korea, India, Taiwan), by North America (United States, Canada, Mexico), by Europe (Germany, United Kingdom, France, Italy), by South America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 272
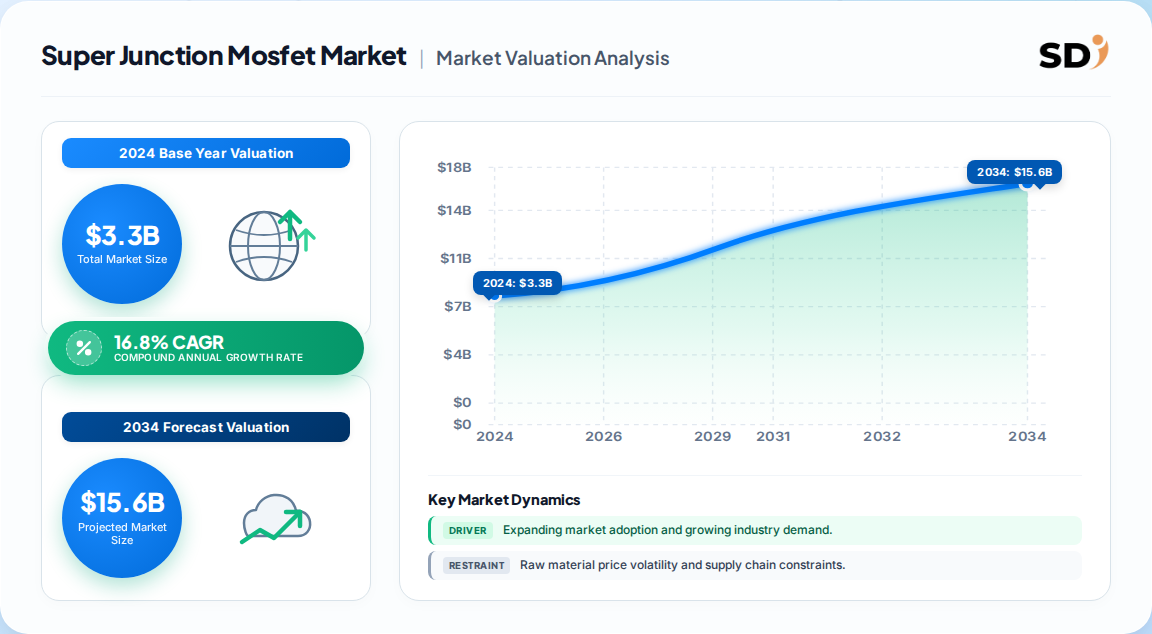
The global super junction MOSFET market was valued at USD 3.3 billion in 2024 and is projected to reach USD 14.8 billion by 2034, expanding at a 16.8% CAGR (2025–2034).
Forecast: Energy-efficiency mandates and EV electrification underpin the aggressive double-digit trajectory through 2034.
Leading segment: Through Hole Type (THT) dominates by packaging, forecast to reach USD 9.1 billion by 2034, while Surface Mount Type (SMT) gains share in compact designs.
Fastest-growing application: Electric vehicles, expanding at an 18.5% CAGR (2025–2034), driven by powertrain and battery-management demand.
Leading regions: Asia-Pacific commands over 50% of global revenue, led by China, Japan, and South Korea; the U.S. accounts for 67.3% of North America.
Key players: Infineon, ON Semiconductor, Toshiba, STMicroelectronics, Fuji Electric, Vishay, Alpha & Omega Semiconductor, and Nexperia lead a moderately concentrated field.
Why this matters for decision-makers: Vendors must pivot toward high-voltage EV and renewable-energy portfolios to avoid margin compression in commoditizing low-voltage consumer segments.
Super Junction Mosfet Market Size (In Billion)
10.0B
8.0B
6.0B
4.0B
2.0B
0
3.300 B
2024
3.850 B
2025
4.500 B
2026
5.260 B
2027
6.140 B
2028
7.170 B
2029
8.380 B
2030
Super Junction Mosfet Market Size (In Billion)
Year
Market Size
2024
3.300 B
2025
3.850 B
2026
4.500 B
2027
5.260 B
2028
6.140 B
2029
7.170 B
2030
8.380 B
What is the Super Junction MOSFET Market?
The super junction MOSFET market comprises power semiconductor devices using charge-balancing structures to achieve low on-resistance and fast switching at high voltages. These devices serve power supplies, solar inverters, EV powertrains, and industrial drives, enabling efficiency gains central to decarbonization and electrification trends worldwide.
Scope: what this report covers and excludes
This report covers the global super junction MOSFET market across type (THT, SMT), voltage class, technology, material, and end-use application, with regional forecasts to 2034. This analysis does not cover discrete IGBT modules, GaN HEMTs, SiC MOSFETs as standalone categories, or broader power MOSFET segments outside the super junction architecture.
How big is the market for Super Junction Mosfet Market?
Estimates diverge materially, reflecting differing base years and definitions. One published estimate places the 2024 base at USD 3.3 billion with a 16.8% CAGR to 2034; a competing analysis pegs 2025 at USD 4.0 billion growing at 10.43% to 2034. Both agree on the direction—robust double-digit expansion—but differ on magnitude.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 3.3 Billion → USD 14.8 Billion
2024
2034
16.8%
Pure super junction MOSFET discrete devices
One published estimate
USD 4.0 Billion → USD 10.0 Billion
2025
2034
10.43%
Super junction MOSFETs incl. high/low voltage split
A competing analysis
USD 17.8 Billion (combined IGBT + SJ MOSFET)
2025
2033
12.2%
Combined IGBT and super junction MOSFET
Another published estimate
Our analysis suggests the USD 3.3 billion figure is the most defensible pure-play baseline, since it isolates super junction devices rather than bundling IGBTs. The 16.8% CAGR may prove optimistic if low-voltage consumer pricing pressure intensifies, but the high-voltage EV and renewable segments justify a premium to the blended 10–12% range.
How is the market segmented?
Segmentation spans packaging, voltage class, fabrication technology, material, and application. The application axis is the most commercially decisive, with electric vehicles growing fastest and energy/power holding the largest revenue base.
Parent Segment
Children
By Type
Through Hole Type (THT), Surface Mount Type (SMT)
By Voltage
High Voltage (>600V), Low Voltage (<600V)
By Technology
Conventional Power MOSFET, Multiple-Epitaxy, Deep-Trench
By Material
Substrate, Transition Layer, Electrode
By Application
Energy & Power, Consumer Electronics, Inverter & UPS, Electric Vehicle, Industrial Systems, Others
Which region leads in Super Junction Mosfet Market?
Asia-Pacific leads the super junction MOSFET market, holding an estimated 53% revenue share in 2025, anchored by China's electronics manufacturing base, Japan's semiconductor incumbents, and South Korea's automotive-electronics ecosystem. North America and Europe follow with roughly 21% and 17% respectively.
Super Junction Mosfet Market Regional Market Share
Loading chart...
Super Junction Mosfet Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.53%
North America
0.21%
Europe
0.17%
South America
0.05%
Middle East & Africa
0.04%
Global
Asia-Pacific — China, Japan, South Korea, India, Taiwan, Rest of APAC
North America — United States, Canada, Mexico
Europe — Germany, United Kingdom, France, Italy, Rest of Europe
South America — Brazil, Argentina, Rest of South America
Middle East & Africa — Saudi Arabia, UAE, South Africa, Rest of MEA
Region
Estimated Share (2025)
Asia-Pacific
53%
North America
21%
Europe
17%
South America
5%
Middle East & Africa
4%
The U.S. dominates North America at 67.3%, underlining a concentrated procurement base tied to data-center, EV, and renewable build-out.
What is driving growth — and what is holding it back?
Energy-efficiency regulation, EV electrification, and renewable-energy deployment are the primary demand engines, while high manufacturing complexity and SiC/GaN substitution pressure restrain pace in select high-voltage niches.
Factor
Direction
Evidence Strength
Mechanism
Energy-efficiency mandates
Driver
High
Low conduction/switching losses improve system efficiency
Server PSUs adopt high-efficiency super junction designs
The balance favors growth: efficiency regulation is durable and global, whereas SiC/GaN substitution is concentrated in extreme high-voltage/thermal niches and remains cost-prohibitive for mainstream consumer and industrial designs.
Who are the leading vendors?
The vendor landscape is moderately concentrated, led by Infineon, ON Semiconductor, Toshiba, and STMicroelectronics, each holding broad super junction portfolios spanning automotive, industrial, and consumer applications. Fuji Electric, Vishay, Alpha & Omega, and Nexperia compete on specialized high-voltage and cost-optimized lines.
Vendor
Notable Strength
Strategic Focus
Infineon Technologies
CoolMOS family, automotive grade
EV, renewable, data center
ON Semiconductor
Broad discrete portfolio
Industrial, automotive
Toshiba
High-voltage reliability
Power supplies, industrial
STMicroelectronics
Automotive & industrial integration
EV powertrain, smart grid
Fuji Electric
Power module adjacency
Industrial drives, renewables
Vishay Intertechnology
Cost-competitive discretes
Consumer, telecom
Alpha & Omega Semiconductor
αMOS5 high-efficiency line
Solar inverters, ESS
Nexperia
High-volume discrete scale
Consumer, automotive
Differentiation rests on voltage-class leadership, automotive qualification (AEC-Q101), and manufacturing yield at deep-trench geometries. Incumbents with proprietary epitaxy IP and fab capacity hold durable moats.
What do buyers and operators need to know?
Buyers should prioritize automotive-qualified parts with verified thermal performance and long-term supply commitments, given fabrication concentration in Asia-Pacific and geopolitical supply risk. Switching costs are moderate—design-in cycles span 12–18 months—so early vendor engagement protects continuity.
Regulatory compliance with efficiency standards and AEC-Q101 automotive qualification is non-negotiable for EV and industrial designs. Operators should dual-source high-voltage parts and monitor SiC pricing, as crossover points could shift procurement strategy in the 2028–2032 window.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a bullish medium-term outlook, but with a quality-of-growth caveat. The pure-play super junction MOSFET market is genuinely expanding at double digits, yet the 16.8% CAGR likely represents an upper bound; a 12–15% trajectory is more defensible once low-voltage consumer commoditization is netted against EV and renewable premiums.
The strongest counter-argument is substitution risk: SiC and GaN are advancing quickly in high-voltage automotive and solar inverters, and if wide-bandgap costs fall faster than expected, super junction's premium segment could compress by the early 2030s. We judge this a 2029+ risk rather than a near-term threat.
Actionable Strategy:
Vendors should prioritize AEC-Q101-qualified high-voltage portfolios for EV and solar to capture the 18.5% application CAGR and defend margins.
Buyers should lock multi-year supply agreements with dual-sourced Asia-Pacific and Western fabs to mitigate geopolitical and capacity risk.
Investors should favor incumbents with proprietary deep-trench IP and automotive design wins over commodity-focused discrete suppliers.
Evidence that would change our conclusion: a sustained SiC price decline below parity at 600–900V, or a sharp contraction in EV production forecasts, would warrant a downward revision to the high-voltage growth thesis.
Super Junction Mosfet Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Super Junction Mosfet Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 16.8% from 2020-2034
Segmentation
By Type
Through Hole Type (THT)
Surface Mount Type (SMT)
By Voltage
High Voltage (>600V)
Low Voltage (<600V)
By Technology
Conventional Power MOSFET
Multiple-Epitaxy
Deep-Trench
By Material
Substrate
Transition Layer
Electrode
By Application
Energy & Power
Consumer Electronics
Inverter & UPS
Electric Vehicle
Industrial Systems
Others
By Geography
Asia-Pacific
China
Japan
South Korea
India
Taiwan
North America
United States
Canada
Mexico
Europe
Germany
United Kingdom
France
Italy
South America
Brazil
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Through Hole Type (THT)
5.1.2. Surface Mount Type (SMT)
5.2. Market Analysis, Insights and Forecast - by Voltage
5.2.1. High Voltage (>600V)
5.2.2. Low Voltage (<600V)
5.3. Market Analysis, Insights and Forecast - by Technology
5.3.1. Conventional Power MOSFET
5.3.2. Multiple-Epitaxy
5.3.3. Deep-Trench
5.4. Market Analysis, Insights and Forecast - by Material
5.4.1. Substrate
5.4.2. Transition Layer
5.4.3. Electrode
5.5. Market Analysis, Insights and Forecast - by Application
5.5.1. Energy & Power
5.5.2. Consumer Electronics
5.5.3. Inverter & UPS
5.5.4. Electric Vehicle
5.5.5. Industrial Systems
5.5.6. Others
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. Asia-Pacific
5.6.2. North America
5.6.3. Europe
5.6.4. South America
5.6.5. Middle East & Africa
6. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Through Hole Type (THT)
6.1.2. Surface Mount Type (SMT)
6.2. Market Analysis, Insights and Forecast - by Voltage
6.2.1. High Voltage (>600V)
6.2.2. Low Voltage (<600V)
6.3. Market Analysis, Insights and Forecast - by Technology
6.3.1. Conventional Power MOSFET
6.3.2. Multiple-Epitaxy
6.3.3. Deep-Trench
6.4. Market Analysis, Insights and Forecast - by Material
6.4.1. Substrate
6.4.2. Transition Layer
6.4.3. Electrode
6.5. Market Analysis, Insights and Forecast - by Application
6.5.1. Energy & Power
6.5.2. Consumer Electronics
6.5.3. Inverter & UPS
6.5.4. Electric Vehicle
6.5.5. Industrial Systems
6.5.6. Others
7. North America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Through Hole Type (THT)
7.1.2. Surface Mount Type (SMT)
7.2. Market Analysis, Insights and Forecast - by Voltage
7.2.1. High Voltage (>600V)
7.2.2. Low Voltage (<600V)
7.3. Market Analysis, Insights and Forecast - by Technology
7.3.1. Conventional Power MOSFET
7.3.2. Multiple-Epitaxy
7.3.3. Deep-Trench
7.4. Market Analysis, Insights and Forecast - by Material
7.4.1. Substrate
7.4.2. Transition Layer
7.4.3. Electrode
7.5. Market Analysis, Insights and Forecast - by Application
7.5.1. Energy & Power
7.5.2. Consumer Electronics
7.5.3. Inverter & UPS
7.5.4. Electric Vehicle
7.5.5. Industrial Systems
7.5.6. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Through Hole Type (THT)
8.1.2. Surface Mount Type (SMT)
8.2. Market Analysis, Insights and Forecast - by Voltage
8.2.1. High Voltage (>600V)
8.2.2. Low Voltage (<600V)
8.3. Market Analysis, Insights and Forecast - by Technology
8.3.1. Conventional Power MOSFET
8.3.2. Multiple-Epitaxy
8.3.3. Deep-Trench
8.4. Market Analysis, Insights and Forecast - by Material
8.4.1. Substrate
8.4.2. Transition Layer
8.4.3. Electrode
8.5. Market Analysis, Insights and Forecast - by Application
8.5.1. Energy & Power
8.5.2. Consumer Electronics
8.5.3. Inverter & UPS
8.5.4. Electric Vehicle
8.5.5. Industrial Systems
8.5.6. Others
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Through Hole Type (THT)
9.1.2. Surface Mount Type (SMT)
9.2. Market Analysis, Insights and Forecast - by Voltage
9.2.1. High Voltage (>600V)
9.2.2. Low Voltage (<600V)
9.3. Market Analysis, Insights and Forecast - by Technology
9.3.1. Conventional Power MOSFET
9.3.2. Multiple-Epitaxy
9.3.3. Deep-Trench
9.4. Market Analysis, Insights and Forecast - by Material
9.4.1. Substrate
9.4.2. Transition Layer
9.4.3. Electrode
9.5. Market Analysis, Insights and Forecast - by Application
9.5.1. Energy & Power
9.5.2. Consumer Electronics
9.5.3. Inverter & UPS
9.5.4. Electric Vehicle
9.5.5. Industrial Systems
9.5.6. Others
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Through Hole Type (THT)
10.1.2. Surface Mount Type (SMT)
10.2. Market Analysis, Insights and Forecast - by Voltage
10.2.1. High Voltage (>600V)
10.2.2. Low Voltage (<600V)
10.3. Market Analysis, Insights and Forecast - by Technology
10.3.1. Conventional Power MOSFET
10.3.2. Multiple-Epitaxy
10.3.3. Deep-Trench
10.4. Market Analysis, Insights and Forecast - by Material
10.4.1. Substrate
10.4.2. Transition Layer
10.4.3. Electrode
10.5. Market Analysis, Insights and Forecast - by Application
10.5.1. Energy & Power
10.5.2. Consumer Electronics
10.5.3. Inverter & UPS
10.5.4. Electric Vehicle
10.5.5. Industrial Systems
10.5.6. Others
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Super Junction Mosfet Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia-Pacific Super Junction Mosfet Market Revenue (Billion), by Type 2026 & 2034
Figure 3: Asia-Pacific Super Junction Mosfet Market Revenue Share (%), by Type 2026 & 2034
Figure 4: Asia-Pacific Super Junction Mosfet Market Revenue (Billion), by Voltage 2026 & 2034
Figure 5: Asia-Pacific Super Junction Mosfet Market Revenue Share (%), by Voltage 2026 & 2034
Figure 6: Asia-Pacific Super Junction Mosfet Market Revenue (Billion), by Technology 2026 & 2034
Figure 7: Asia-Pacific Super Junction Mosfet Market Revenue Share (%), by Technology 2026 & 2034
Figure 8: Asia-Pacific Super Junction Mosfet Market Revenue (Billion), by Material 2026 & 2034
Figure 9: Asia-Pacific Super Junction Mosfet Market Revenue Share (%), by Material 2026 & 2034
Figure 10: Asia-Pacific Super Junction Mosfet Market Revenue (Billion), by Application 2026 & 2034
Figure 11: Asia-Pacific Super Junction Mosfet Market Revenue Share (%), by Application 2026 & 2034
Figure 12: Asia-Pacific Super Junction Mosfet Market Revenue (Billion), by Country 2026 & 2034
Figure 13: Asia-Pacific Super Junction Mosfet Market Revenue Share (%), by Country 2026 & 2034
Figure 14: North America Super Junction Mosfet Market Revenue (Billion), by Type 2026 & 2034
Figure 15: North America Super Junction Mosfet Market Revenue Share (%), by Type 2026 & 2034
Figure 16: North America Super Junction Mosfet Market Revenue (Billion), by Voltage 2026 & 2034
List of Tables
Table 1: Super Junction Mosfet Market Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Super Junction Mosfet Market Revenue Billion Forecast, by Voltage 2020 & 2034
Table 3: Super Junction Mosfet Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 4: Super Junction Mosfet Market Revenue Billion Forecast, by Material 2020 & 2034
Table 5: Super Junction Mosfet Market Revenue Billion Forecast, by Application 2020 & 2034
Table 6: Super Junction Mosfet Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: Asia-Pacific Super Junction Mosfet Market Revenue Billion Forecast, by Type 2020 & 2034
Table 8: Asia-Pacific Super Junction Mosfet Market Revenue Billion Forecast, by Voltage 2020 & 2034
Table 9: Asia-Pacific Super Junction Mosfet Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 10: Asia-Pacific Super Junction Mosfet Market Revenue Billion Forecast, by Material 2020 & 2034
Table 11: Asia-Pacific Super Junction Mosfet Market Revenue Billion Forecast, by Application 2020 & 2034
Table 12: Asia-Pacific Super Junction Mosfet Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: China Super Junction Mosfet Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Japan Super Junction Mosfet Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: South Korea Super Junction Mosfet Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: India Super Junction Mosfet Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the super junction MOSFET market size?
The global super junction MOSFET market was valued at approximately USD 3.3 billion in 2024 and is forecast to reach USD 14.8 billion by 2034, growing at a 16.8% CAGR.
2. Which region dominates the super junction MOSFET market?
Asia-Pacific leads with over 50% revenue share, driven by China, Japan, and South Korea. The U.S. dominates North America at 67.3% of regional revenue.
3. What is the fastest-growing application segment?
Electric vehicles represent the fastest-growing application at an 18.5% CAGR, fueled by powertrain, battery-management, and charging-infrastructure demand.
4. Who are the leading super junction MOSFET vendors?
Infineon, ON Semiconductor, Toshiba, STMicroelectronics, Fuji Electric, Vishay, Alpha & Omega Semiconductor, and Nexperia lead the competitive landscape.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including raw silicon and epitaxial wafer suppliers, specialized discrete device producers, contract manufacturers, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of both technical and commercial perspectives on super junction MOSFET adoption.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP of Sourcing
30%
Heads of R&D
30%
Technical Directors
25%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Silicon & Epitaxial Wafer Suppliers
30%
Specialized Discrete Device Producers
40%
Contract Manufacturers
15%
Global Distributors
15%
Secondary Benchmarking & Public Trade Validation
Secondary validation drew on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards bodies. Automotive qualification benchmarks such as AEC-Q101 and efficiency standards were cross-referenced to validate demand assumptions.
Demand Modeling & Market Sizing Triangulation
Market sizing combined simultaneous Top-Down (macroeconomic and end-use segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption modeling) triangulation. Discrepancies between the two approaches were reconciled through weighted averaging and analyst judgment.
 Super Junction Mosfet Market