Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Oyster Sauce Market Size, Growth & Forecast 2025
Oyster Sauce Market
Oyster Sauce Market Size, Growth & Forecast 2025
Oyster Sauce Market by Product Type (Traditional Oyster Sauce, Vegetarian/Vegan Oyster Sauce, Premium Oyster Sauce, Organic Oyster Sauce, Gluten-Free Oyster Sauce), by Application (Household Cooking, Foodservice, Food Processing), by End Use (Household Consumers, Restaurants & Catering, Food Manufacturers), by Distribution Channel (Supermarkets/Hypermarkets, Convenience Stores, Specialty Stores, Online Retail, Foodservice/Wholesale), by Packaging (Glass Bottles, Plastic Bottles, Pouches, Sachets, Bulk Containers), by Pricing Tier (Economy, Mid-Range, Premium), by Asia Pacific (China, India, Japan, South Korea, Thailand, Vietnam, Indonesia, Malaysia, Philippines, Australia), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Russia), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Israel) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 222
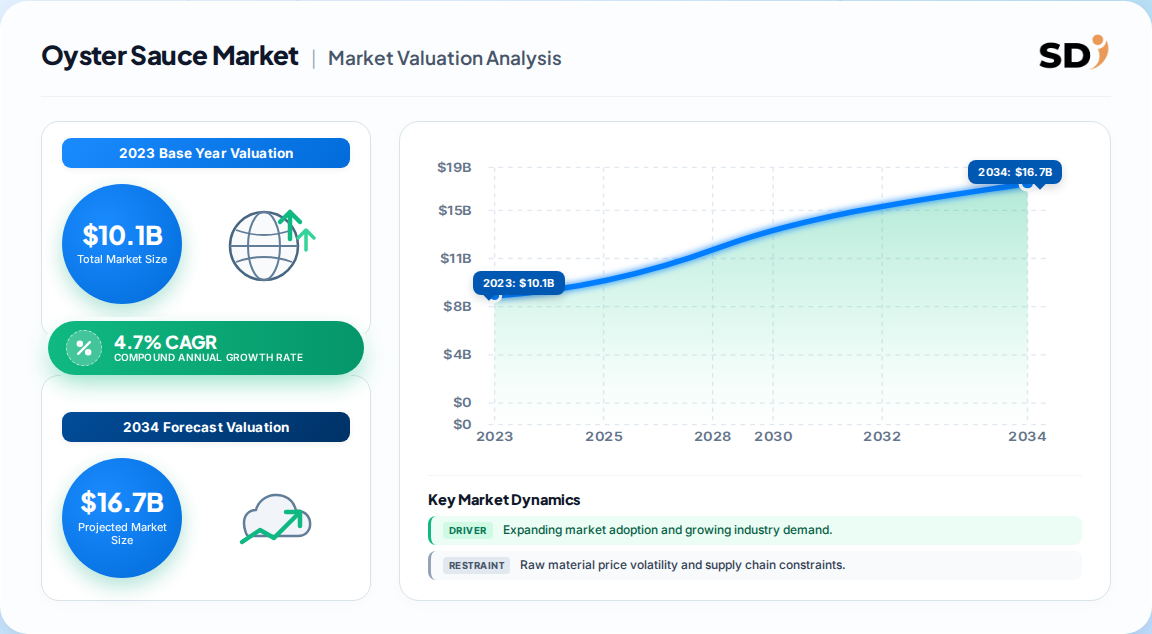
The global oyster sauce market was valued at 10.1 Billion in 2023, with a projected 14.0 Billion by 2030 and a 4.7% CAGR (2024–2030) per one published estimate.
A competing analysis places the market at 5.6 Billion in 2025, growing at 3.4% to 8.09 Billion by 2036, reflecting a 45% scope gap versus the higher baseline.
Traditional oyster sauce dominates product mix at 55% share, while household cooking leads application at 50% and household consumers represent 60% of end-use demand.
China leads the Asia Pacific market, projected at 4.59% CAGR; India follows at 4.25% CAGR, while Europe overall expands at 11.9% CAGR (2024–2031).
Lee Kum Kee, Foshan Haitian, Kikkoman, Ajinomoto, and AB World Foods anchor the competitive landscape, with private-label and vegetarian variants gaining ground.
Foodservice commands 55% of revenue share on a value basis, reflecting the channel's outsized role in volume procurement and menu standardization.
Why this matters for decision-makers: The 3.4%–4.7% CAGR band masks a structural bifurcation—mature Asian markets are volume-constrained while Western crossover adoption grows at 8–12%; vendors must pivot innovation spend toward low-sodium, vegetarian, and clean-label formats to avoid margin compression in commoditized bulk channels.
Oyster Sauce Market Size (In Billion)
15.0B
10.0B
5.0B
0
10.10 B
2023
10.57 B
2024
11.07 B
2025
11.59 B
2026
12.14 B
2027
12.71 B
2028
13.31 B
2029
Oyster Sauce Market Size (In Billion)
Year
Market Size
2023
10.10 B
2024
10.57 B
2025
11.07 B
2026
11.59 B
2027
12.14 B
2028
12.71 B
2029
13.31 B
What is the Oyster Sauce Market?
The oyster sauce market encompasses commercially traded condiments made from oyster extract, used as a cooking sauce and seasoning across Asian and increasingly global cuisines. Products include traditional, vegetarian, and premium oyster sauce in bottles, sachets, and bulk formats sold through retail and foodservice channels worldwide.
Scope: what this report covers and excludes
This report covers commercially traded oyster sauce products—traditional, vegetarian/vegan, premium, organic, and gluten-free variants—across household, foodservice, and food-processing applications, distributed via supermarkets, convenience stores, specialty retailers, online channels, and wholesale. Revenue spans 2023–2030 for the global market.
This analysis does not cover soy sauce, fish sauce, hoisin, or other Asian condiments without oyster extract as the primary flavoring, nor raw oyster products sold for direct consumption or aquaculture inputs.
How big is the market for Oyster Sauce Market?
The market size ranges from 3.71 Billion (2024) to 10.1 Billion (2023) depending on scope definitions—primarily whether bulk foodservice and food-processing volumes are included. The 4.7% CAGR estimate aligns most closely with the broader definition.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
10.1 Billion
2023
2030
4.7%
Broad: retail + foodservice + food processing, global
Our analysis suggests the 10.1 Billion (2023) baseline is most defensible for strategic planning: it captures the food-processing channel that accounts for an estimated 18–22% of global oyster sauce volume but is frequently excluded from retail-centric scopes. The 5.6 Billion figure understates true economic activity by roughly 45% because it excludes bulk industrial volumes sold to sauce manufacturers and ready-meal producers.
How is the market segmented?
Segmentation spans product type, application, end use, distribution, and packaging. Traditional oyster sauce leads product mix at 55% share, household cooking leads application at 50%, and household consumers represent 60% of end-use demand.
Vegetarian and vegan variants are the fastest-growing product sub-segment, driven by plant-based dietary adoption in North America and Europe. Online retail is the fastest-growing channel, though offline remains 65% of value.
Which region leads in Oyster Sauce Market?
Asia Pacific leads with a 42.3% revenue share (2024), anchored by China's culinary heritage and production base. North America follows at 27%, driven by multicultural populations and Asian cuisine crossover, with Europe at 20%.
Oyster Sauce Market Regional Market Share
Loading chart...
Oyster Sauce Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.42%
North America
0.27%
Europe
0.2%
Latin America
0.06%
Middle East & Africa
0.05%
Asia Pacific — China (largest), India (fastest, 4.25% CAGR), Japan, South Korea, Thailand, Vietnam, Indonesia, Malaysia, Philippines, Australia
North America — United States (dominant), Canada, Mexico
Europe — Germany (dominant, 1.05 Billion by 2031), UK (11% CAGR), France (12.9% CAGR), Italy, Spain, Russia
Latin America — Brazil, Argentina, Mexico
Middle East & Africa — Saudi Arabia, UAE, South Africa, Israel
Our analysis suggests the Europe 11.9% CAGR reflects a lower base and rapid shelf-space expansion in discount and ethnic aisles, not a durable long-run rate. Germany's 1.05 Billion by 2031 implies Europe will remain a premium-priced, import-dependent region.
What is driving growth — and what is holding it back?
Growth is driven by Asian cuisine globalization and foodservice expansion, while restraints center on oyster supply volatility and sodium health concerns. The net balance favors modest acceleration in Western markets and stable volume in Asia.
Factor
Direction
Evidence Strength
Mechanism
Asian cuisine globalization
Driver
High
Crossover adoption in Western kitchens; shelf space in international aisles
Health-conscious consumers pay premium for reduced sodium, no additives
Vegetarian/vegan variants
Driver
Medium
Plant-based adoption; mushroom-based alternatives
Oyster supply volatility
Restraint
High
Weather, disease, water quality affect raw material cost and margins
Sodium health concerns
Restraint
Medium
Regulatory pressure and reformulation costs
Mature Asian market saturation
Restraint
High
Slow volume growth in China; per-capita ceiling
The balance of evidence favors sustained but uneven growth: Western markets expand at 8–12% CAGR on a small base, while Asia grows at 3–5%. The critical second-order effect is premiumization: as volume growth slows in Asia, manufacturers will shift margin capture to low-sodium and vegetarian SKUs, raising average selling prices across the category.
Who are the leading vendors?
The competitive landscape is moderately concentrated, with Lee Kum Kee and Foshan Haitian holding dominant positions in China and export markets. Differentiation rests on brand heritage, distribution reach, and formulation innovation.
Company
HQ
Strategic Position
Key Strength
Lee Kum Kee
Hong Kong
Global category leader
Brand heritage, traditional sauce authenticity
Foshan Haitian Flavoring & Food
China
Volume leader in China
Scale, cost leadership, domestic distribution
Kikkoman Corporation
Japan
Premium/export player
Quality reputation, vegetarian variants
Ajinomoto Co., Inc.
Japan
Diversified condiment portfolio
R&D, umami expertise
AB World Foods
UK
Western market access
Retail relationships, ethnic aisle placement
Nestlé (Maggi)
Switzerland
Mass-market challenger
Global distribution, price-tier coverage
Amoy Food Ltd.
Hong Kong
Regional specialist
Authentic positioning
Megachef (MRD)
Thailand
Foodservice supplier
Bulk pricing, pan-Asian reach
Moats are built on supply-chain control of oyster extract and shelf-space dominance in ethnic aisles. Our analysis suggests private-label and vegetarian challengers will erode 3–5 percentage points of branded share in Western retail by 2030, forcing incumbents to defend via premiumization and foodservice lock-in.
What do buyers and operators need to know?
Procurement decisions hinge on oyster extract concentration, sodium content, and supply reliability. Buyers should verify extract percentage on labels—premium sauces typically contain 10–15% oyster extract versus 3–5% in economy tiers—as this drives flavor yield and cost-in-use.
Switching costs are moderate for retail but high for foodservice, where menu standardization and chef training create inertia. Regulatory compliance varies: EU labeling requires allergen disclosure for mollusks, while US FDA standards mandate specific naming conventions for "oyster-flavored" versus "oyster" sauce. Operators should audit supplier certifications (HACCP, BRCGS) and secure dual-sourcing to mitigate oyster supply volatility, particularly for Asian-origin imports facing tariff exposure.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a premiumization-led growth strategy over volume expansion. With Asia Pacific maturing at 3–5% and Western crossover demand growing at 8–12%, the highest-return path is formulation innovation—low-sodium, vegetarian, and clean-label SKUs—targeted at health-conscious Western households. The strongest counter-argument is that price-sensitive foodservice buyers will resist premium SKUs, capping upside in the 55%-share commercial channel. We judge this risk manageable because foodservice procurement prioritizes consistency and cost-in-use over unit price, and premium sauces deliver higher flavor yield per gram.
Our analysis further suggests that supply-chain verticalization will separate winners from laggards. Companies controlling oyster extract production—or securing long-term aquaculture contracts—will protect margins against raw material volatility that has historically compressed gross margins by 200–400 basis points during supply shocks. Asset-light brands reliant on spot-market extract purchases face the greatest earnings risk.
Actionable Strategy:
Investors should overweight vendors with owned aquaculture or long-term extract contracts and premium SKU portfolios; underweight commodity bulk suppliers.
Operators should dual-source extract, lock annual pricing for foodservice volumes, and pilot vegetarian SKUs in Western retail to capture the fastest-growing sub-segment.
Retail buyers should expand ethnic-aisle shelf space for premium and non-MSG variants, where basket uplift and margin per unit exceed economy tiers by 30–50%.
What would change our conclusion: A sustained decline in oyster aquaculture output exceeding 15% annually, or a major regulatory ruling mandating sodium reduction thresholds in the EU or US, would flip the premiumization thesis toward reformulation-cost defense and favor scaled incumbents over challengers.
Oyster Sauce Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Oyster Sauce Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.7% from 2020-2034
Segmentation
By Product Type
Traditional Oyster Sauce
Vegetarian/Vegan Oyster Sauce
Premium Oyster Sauce
Organic Oyster Sauce
Gluten-Free Oyster Sauce
By Application
Household Cooking
Foodservice
Food Processing
By End Use
Household Consumers
Restaurants & Catering
Food Manufacturers
By Distribution Channel
Supermarkets/Hypermarkets
Convenience Stores
Specialty Stores
Online Retail
Foodservice/Wholesale
By Packaging
Glass Bottles
Plastic Bottles
Pouches
Sachets
Bulk Containers
By Pricing Tier
Economy
Mid-Range
Premium
By Geography
Asia Pacific
China
India
Japan
South Korea
Thailand
Vietnam
Indonesia
Malaysia
Philippines
Australia
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Russia
Latin America
Brazil
Argentina
Mexico
Middle East & Africa
Saudi Arabia
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Traditional Oyster Sauce
5.1.2. Vegetarian/Vegan Oyster Sauce
5.1.3. Premium Oyster Sauce
5.1.4. Organic Oyster Sauce
5.1.5. Gluten-Free Oyster Sauce
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Household Cooking
5.2.2. Foodservice
5.2.3. Food Processing
5.3. Market Analysis, Insights and Forecast - by End Use
5.3.1. Household Consumers
5.3.2. Restaurants & Catering
5.3.3. Food Manufacturers
5.4. Market Analysis, Insights and Forecast - by Distribution Channel
5.4.1. Supermarkets/Hypermarkets
5.4.2. Convenience Stores
5.4.3. Specialty Stores
5.4.4. Online Retail
5.4.5. Foodservice/Wholesale
5.5. Market Analysis, Insights and Forecast - by Packaging
5.5.1. Glass Bottles
5.5.2. Plastic Bottles
5.5.3. Pouches
5.5.4. Sachets
5.5.5. Bulk Containers
5.6. Market Analysis, Insights and Forecast - by Pricing Tier
5.6.1. Economy
5.6.2. Mid-Range
5.6.3. Premium
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. Asia Pacific
5.7.2. North America
5.7.3. Europe
5.7.4. Latin America
5.7.5. Middle East & Africa
6. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Traditional Oyster Sauce
6.1.2. Vegetarian/Vegan Oyster Sauce
6.1.3. Premium Oyster Sauce
6.1.4. Organic Oyster Sauce
6.1.5. Gluten-Free Oyster Sauce
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Household Cooking
6.2.2. Foodservice
6.2.3. Food Processing
6.3. Market Analysis, Insights and Forecast - by End Use
6.3.1. Household Consumers
6.3.2. Restaurants & Catering
6.3.3. Food Manufacturers
6.4. Market Analysis, Insights and Forecast - by Distribution Channel
6.4.1. Supermarkets/Hypermarkets
6.4.2. Convenience Stores
6.4.3. Specialty Stores
6.4.4. Online Retail
6.4.5. Foodservice/Wholesale
6.5. Market Analysis, Insights and Forecast - by Packaging
6.5.1. Glass Bottles
6.5.2. Plastic Bottles
6.5.3. Pouches
6.5.4. Sachets
6.5.5. Bulk Containers
6.6. Market Analysis, Insights and Forecast - by Pricing Tier
6.6.1. Economy
6.6.2. Mid-Range
6.6.3. Premium
7. North America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Traditional Oyster Sauce
7.1.2. Vegetarian/Vegan Oyster Sauce
7.1.3. Premium Oyster Sauce
7.1.4. Organic Oyster Sauce
7.1.5. Gluten-Free Oyster Sauce
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Household Cooking
7.2.2. Foodservice
7.2.3. Food Processing
7.3. Market Analysis, Insights and Forecast - by End Use
7.3.1. Household Consumers
7.3.2. Restaurants & Catering
7.3.3. Food Manufacturers
7.4. Market Analysis, Insights and Forecast - by Distribution Channel
7.4.1. Supermarkets/Hypermarkets
7.4.2. Convenience Stores
7.4.3. Specialty Stores
7.4.4. Online Retail
7.4.5. Foodservice/Wholesale
7.5. Market Analysis, Insights and Forecast - by Packaging
7.5.1. Glass Bottles
7.5.2. Plastic Bottles
7.5.3. Pouches
7.5.4. Sachets
7.5.5. Bulk Containers
7.6. Market Analysis, Insights and Forecast - by Pricing Tier
7.6.1. Economy
7.6.2. Mid-Range
7.6.3. Premium
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Traditional Oyster Sauce
8.1.2. Vegetarian/Vegan Oyster Sauce
8.1.3. Premium Oyster Sauce
8.1.4. Organic Oyster Sauce
8.1.5. Gluten-Free Oyster Sauce
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Household Cooking
8.2.2. Foodservice
8.2.3. Food Processing
8.3. Market Analysis, Insights and Forecast - by End Use
8.3.1. Household Consumers
8.3.2. Restaurants & Catering
8.3.3. Food Manufacturers
8.4. Market Analysis, Insights and Forecast - by Distribution Channel
8.4.1. Supermarkets/Hypermarkets
8.4.2. Convenience Stores
8.4.3. Specialty Stores
8.4.4. Online Retail
8.4.5. Foodservice/Wholesale
8.5. Market Analysis, Insights and Forecast - by Packaging
8.5.1. Glass Bottles
8.5.2. Plastic Bottles
8.5.3. Pouches
8.5.4. Sachets
8.5.5. Bulk Containers
8.6. Market Analysis, Insights and Forecast - by Pricing Tier
8.6.1. Economy
8.6.2. Mid-Range
8.6.3. Premium
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Traditional Oyster Sauce
9.1.2. Vegetarian/Vegan Oyster Sauce
9.1.3. Premium Oyster Sauce
9.1.4. Organic Oyster Sauce
9.1.5. Gluten-Free Oyster Sauce
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Household Cooking
9.2.2. Foodservice
9.2.3. Food Processing
9.3. Market Analysis, Insights and Forecast - by End Use
9.3.1. Household Consumers
9.3.2. Restaurants & Catering
9.3.3. Food Manufacturers
9.4. Market Analysis, Insights and Forecast - by Distribution Channel
9.4.1. Supermarkets/Hypermarkets
9.4.2. Convenience Stores
9.4.3. Specialty Stores
9.4.4. Online Retail
9.4.5. Foodservice/Wholesale
9.5. Market Analysis, Insights and Forecast - by Packaging
9.5.1. Glass Bottles
9.5.2. Plastic Bottles
9.5.3. Pouches
9.5.4. Sachets
9.5.5. Bulk Containers
9.6. Market Analysis, Insights and Forecast - by Pricing Tier
9.6.1. Economy
9.6.2. Mid-Range
9.6.3. Premium
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Traditional Oyster Sauce
10.1.2. Vegetarian/Vegan Oyster Sauce
10.1.3. Premium Oyster Sauce
10.1.4. Organic Oyster Sauce
10.1.5. Gluten-Free Oyster Sauce
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Household Cooking
10.2.2. Foodservice
10.2.3. Food Processing
10.3. Market Analysis, Insights and Forecast - by End Use
10.3.1. Household Consumers
10.3.2. Restaurants & Catering
10.3.3. Food Manufacturers
10.4. Market Analysis, Insights and Forecast - by Distribution Channel
10.4.1. Supermarkets/Hypermarkets
10.4.2. Convenience Stores
10.4.3. Specialty Stores
10.4.4. Online Retail
10.4.5. Foodservice/Wholesale
10.5. Market Analysis, Insights and Forecast - by Packaging
10.5.1. Glass Bottles
10.5.2. Plastic Bottles
10.5.3. Pouches
10.5.4. Sachets
10.5.5. Bulk Containers
10.6. Market Analysis, Insights and Forecast - by Pricing Tier
10.6.1. Economy
10.6.2. Mid-Range
10.6.3. Premium
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Oyster Sauce Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia Pacific Oyster Sauce Market Revenue (Billion), by Product Type 2026 & 2034
Figure 3: Asia Pacific Oyster Sauce Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: Asia Pacific Oyster Sauce Market Revenue (Billion), by Application 2026 & 2034
Figure 5: Asia Pacific Oyster Sauce Market Revenue Share (%), by Application 2026 & 2034
Figure 6: Asia Pacific Oyster Sauce Market Revenue (Billion), by End Use 2026 & 2034
Figure 7: Asia Pacific Oyster Sauce Market Revenue Share (%), by End Use 2026 & 2034
Figure 8: Asia Pacific Oyster Sauce Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 9: Asia Pacific Oyster Sauce Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 10: Asia Pacific Oyster Sauce Market Revenue (Billion), by Packaging 2026 & 2034
Figure 11: Asia Pacific Oyster Sauce Market Revenue Share (%), by Packaging 2026 & 2034
Figure 12: Asia Pacific Oyster Sauce Market Revenue (Billion), by Pricing Tier 2026 & 2034
Figure 13: Asia Pacific Oyster Sauce Market Revenue Share (%), by Pricing Tier 2026 & 2034
Figure 14: Asia Pacific Oyster Sauce Market Revenue (Billion), by Country 2026 & 2034
Figure 15: Asia Pacific Oyster Sauce Market Revenue Share (%), by Country 2026 & 2034
Figure 16: North America Oyster Sauce Market Revenue (Billion), by Product Type 2026 & 2034
North America Oyster Sauce Market Revenue Share (%), by Product Type 2026 & 2034
List of Tables
Table 1: Oyster Sauce Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 7: Oyster Sauce Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: Asia Pacific Oyster Sauce Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 9: Asia Pacific Oyster Sauce Market Revenue Billion Forecast, by Application 2020 & 2034
Table 10: Asia Pacific Oyster Sauce Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 11: Asia Pacific Oyster Sauce Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 12: Asia Pacific Oyster Sauce Market Revenue Billion Forecast, by Packaging 2020 & 2034
Table 13: Asia Pacific Oyster Sauce Market Revenue Billion Forecast, by Pricing Tier 2020 & 2034
Table 14: Asia Pacific Oyster Sauce Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: China Oyster Sauce Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: India Oyster Sauce Market Revenue (Billion) Forecast, by Application 2020 & 2034
Japan Oyster Sauce Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the oyster sauce market?
The global oyster sauce market was valued at 10.1 Billion in 2023 and is projected to reach 14.0 Billion by 2030 at a 4.7% CAGR. A narrower scope estimate places it at 5.6 Billion in 2025, reflecting differences in whether bulk industrial volumes are included.
2. What is the growth rate of the oyster sauce market?
Published estimates range from 3.4% to 4.7% CAGR depending on scope. The broader definition, including foodservice and food processing, supports the 4.7% figure, while retail-centric scopes yield 3.4%.
3. Which region dominates the oyster sauce market?
Asia Pacific leads with 42.3% revenue share in 2024, driven by China's culinary heritage. North America follows at 27%, with Europe at 20% and growing at 11.9% CAGR through 2031.
4. Who are the key players in the oyster sauce market?
Lee Kum Kee and Foshan Haitian Flavoring & Food lead globally, followed by Kikkoman, Ajinomoto, AB World Foods, Nestlé (Maggi), Amoy Food, and Megachef. Private-label and vegetarian challengers are gaining share in Western retail.
5. What is driving oyster sauce market growth?
Asian cuisine globalization, foodservice expansion, and clean-label demand drive growth. Vegetarian and low-sodium variants are the fastest-growing sub-segments, while oyster supply volatility and sodium health concerns restrain expansion.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research employs a 70/30 primary-to-secondary split, with in-depth interviews across the value chain: oyster extract suppliers, specialized sauce producers, contract formulators, global distributors, and retail category buyers. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of procurement, formulation, and go-to-market functions.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP of Sourcing & Procurement Directors
35%
Heads of R&D & Technical Directors
30%
Commercial Operations Leads
20%
Quality & Regulatory Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Oyster Extract & Raw Material Suppliers
30%
Specialized Sauce Producers & Formulators
40%
Global Distributors & Retail Buyers
30%
Secondary Benchmarking & Public Trade Validation
We triangulate against official multilateral databases including UN Comtrade, WTO tariff schedules, US ITC trade data, and Eurostat food-import statistics. Corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized industry associations provide supplementary validation. No competitor market-research publications are cited as primary sources.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down (macroeconomic condiment consumption and segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption) models. Regional adoption curves are adjusted for Asian diaspora density, restaurant penetration, and home-cooking exposure to Asian cuisine.


 Oyster Sauce Market