Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Automatic Self Cleaning Cat Litter Box Market by Product (Single Cat, Multi Cat), by Buyer Type (Residential, Commercial, Institutional), by Distribution Channel (Offline, Online), by Technology (Basic Automation, App-Connected, Health-Analytics), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 212
702 Million — Global automatic self-cleaning cat litter box market size in 2025, up from 530 Million in 2020.
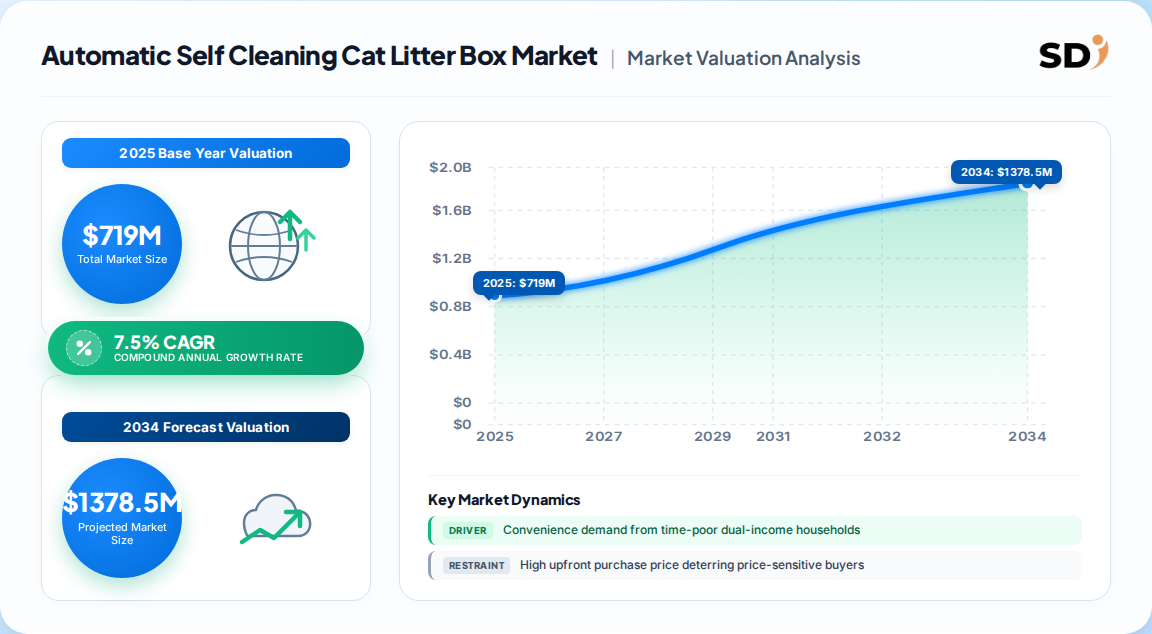
7.5% CAGR — Forecast growth 2025–2032, accelerating from the 6.3% historical rate as connected, health-analytics features gain share.
1.19 Billion — Projected 2032 market value, with unit shipments rising from 3.35M to 4.91M annually.
78% — Share held by single-cat systems in 2024; multi-cat is the fastest-growing product segment.
North America — Largest region at 36.5% of 2025 revenue, powered by 49 million US cat-owning households.
Whisker, PETKIT, CATLINK, PetSafe, Neakasa — Leading vendors in a fragmented field of over 600 players.
Why this matters for decision-makers: Vendors must pivot from penetration-led hardware toward connected health-analytics and subscription economics to avoid margin compression from factory-direct Chinese entrants.
Automatic Self Cleaning Cat Litter Box Market Size (In Million)
1.0B
800.0M
600.0M
400.0M
200.0M
0
530.0 M
2020
563.0 M
2021
599.0 M
2022
636.0 M
2023
676.0 M
2024
719.0 M
2025
773.0 M
2026
Automatic Self Cleaning Cat Litter Box Market Size (In Million)
Year
Market Size
2020
530.0 M
2021
563.0 M
2022
599.0 M
2023
636.0 M
2024
676.0 M
2025
719.0 M
2026
773.0 M
What is the Automatic Self Cleaning Cat Litter Box Market?
An automatic self-cleaning cat litter box is a consumer appliance that detects a cat's use via sensors and automatically rakes, sifts, or flushes waste into a sealed compartment. It eliminates daily manual scooping, controls odor, and increasingly integrates app connectivity and health-monitoring analytics. The category sits at the intersection of pet care, smart-home IoT, and consumer electronics.
Scope: what this report covers and excludes
This report covers global revenue and unit forecasts for automatic self-cleaning cat litter boxes across single-cat and multi-cat configurations, residential and commercial buyers, and online and offline distribution channels from 2025 to 2032. It profiles product technology, pricing tiers, and regional demand. This analysis does not cover manual litter boxes, cat litter consumables, general pet electronics (feeders, fountains), or veterinary diagnostic services.
How big is the market for Automatic Self Cleaning Cat Litter Box Market?
Published estimates for the automatic self-cleaning cat litter box market diverge materially because of scope, base-year, and channel-definition differences. The table below reconciles the leading benchmarks against their stated definitions.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
702.3 Million
2025
2034
6.06%
Global retail value, single + multi-cat
One published estimate
719 Million
2025
2032
7.50%
Global brand-net, connected premium ecosystem
One competing analysis
559.3 Million
2024
2030
7.8%
Global retail value, narrower connected definition
Another published estimate
1.18 Billion
2025
2030
12.3%
Broadly defined "smart" litter box incl. basic automation
Adjacent-category estimate
The most defensible base is the 719 Million (2025) figure: it is supported by explicit unit-shipment (3.35M) and blended-ASP (215 USD) triangulation, which reconciles value and volume. The 1.18 Billion "smart" estimate inflates scope by including semi-automated and accessory products. Our analysis suggests the true connected-hardware market is closer to 700–720 Million in 2025, with upside bias from health-analytics premiumization.
How is the market segmented?
Segmentation reveals single-cat dominance (78% share) offset by multi-cat's faster growth (8.9% CAGR), alongside an offline-leaning distribution mix that is steadily ceding share to e-commerce.
Parent Segment
Children
2025 Position
By Product
Single Cat, Multi Cat
Single Cat 78%; Multi Cat fastest-growing
By Buyer Type
Residential, Commercial, Institutional
Residential dominant
By Distribution
Offline, Online
Offline 57.5–58%; Online fastest-growing
By Technology
Basic Automation, App-Connected, Health-Analytics
App-connected fastest-growing
Which region leads in Automatic Self Cleaning Cat Litter Box Market?
North America leads the automatic self-cleaning cat litter box market with 36.5% of 2025 global revenue, anchored by 49 million US cat-owning households, high premium-pet expenditure, and mature direct-to-consumer brands. Asia-Pacific is the fastest-growing region, driven by urbanization and rising disposable income.
Asia Pacific (China, Japan, India, South Korea, Australia–NZ)
Latin America (Brazil, Mexico, Argentina)
Middle East & Africa (Saudi Arabia, UAE, South Africa)
Region
2025 Share
Growth Outlook
North America
36.5%
Mature, premium-led
Asia-Pacific
28%
Fastest-growing (China ~8.8% CAGR)
Europe
22%
Steady, eco-conscious
Latin America
7%
Emerging
Middle East & Africa
6.5%
Nascent
The divergence between North America's revenue dominance and Asia-Pacific's growth velocity is the single most important regional signal. This divergence implies vendors should defend premium margin in North America while deploying lower-ASP, factory-direct SKUs in Asia to capture volume before local brands consolidate.
What is driving growth — and what is holding it back?
Growth is driven by time-poor, dual-income households and rising pet-tech adoption, while high upfront cost and sensor reliability concerns restrain penetration — particularly in emerging markets.
Factor
Direction
Evidence Strength
Mechanism
Convenience / time scarcity
Driver
High
Automates daily chore for busy owners
Pet hygiene & health awareness
Driver
High
Odor, bacteria, allergen reduction
Smart-home & IoT integration
Driver
Medium-High
App control, usage analytics, alerts
Rising global cat ownership
Driver
High
370M+ pet cats worldwide
High upfront purchase price
Restraint
High
599–899 USD premium units deter price-sensitive buyers
Sensor/connectivity reliability
Restraint
Medium
Faults drive returns and brand damage
Inconsistent safety certification
Restraint
Medium
Regulatory fragmentation limits market entry
The balance of evidence shows demand-side drivers are structural and durable, while restraints are largely price- and execution-related — meaning they are addressable through tiered pricing and reliability engineering. Our analysis suggests the biggest near-term upside is converting first-time single-cat buyers into the ecosystem, then upselling multi-cat and analytics tiers.
Who are the leading vendors?
Whisker (Litter-Robot), PETKIT, CATLINK, PetSafe, and Neakasa lead a fragmented 600+ player field, with differentiation resting on sensor reliability, connected analytics, and price-tier coverage.
Vendor
Positioning
Price Tier
Key Moat
Whisker (Litter-Robot)
Premium connected
599–899 USD
Brand, 1.5M+ units, DTC ecosystem
PETKIT
Mid-premium smart
Mid
IoT app, global retail reach
CATLINK
Value-smart
Mid-low
Health analytics, affordability
PetSafe
Mainstream
200–400 USD
Mass retail distribution
Neakasa
Premium design
~600 USD
Design innovation (M1)
Whisker's 60,000+ five-star reviews and 1.5M+ cumulative units illustrate the durability of brand trust as a moat in an emotional product category. This implies new entrants must compete on reliability and price-to-value rather than attempting to outspend incumbents on brand.
What do buyers and operators need to know? (Decision Support)
Procurement decisions hinge on four mission-critical criteria: sensor reliability, waste-capacity and multi-cat suitability, app/health-analytics integration depth, and safety certification. Buyers should demand verified cycle-reliability data and warranty terms, because sensor failures drive the highest post-purchase dissatisfaction and return rates. Switching costs are moderate but rising as subscription and consumables ecosystems lock in users. Regulatory compliance is fragmented — the absence of a unified safety standard means operators must validate certifications market-by-market. For institutional and veterinary buyers, enclosed waste chambers and antimicrobial components are increasingly non-negotiable.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a premiumization-plus-ecosystem strategy over pure volume penetration. The category's value CAGR (7.5%) outpaces unit CAGR (5.6%), signaling that the economics reward connected analytics, multi-cat capacity, and recurring revenue — not factory-direct commoditization. The strongest counter-argument is that low-cost Chinese entrants will compress ASPs faster than premium features can offset, especially in price-sensitive Asia-Pacific and emerging markets. We weight this risk as real but secondary: it caps the entry tier without eroding the premium ceiling that Whisker commands.
A second-order effect our analysis highlights is the shift from hardware to platform economics. Health-analytics and subscription services let brands monetize the installed base continuously, softening hardware margin pressure and raising switching costs. Vendors that treat connectivity as a cost center rather than a monetization layer will cede long-term value to ecosystem players.
Actionable Strategy 1: Prioritize connected health-analytics and subscription bundles to lift blended ASP and recurring revenue.
Actionable Strategy 2: Deploy tiered, region-specific pricing (premium in North America/Europe, value SKUs in Asia) to capture volume without eroding brand.
Actionable Strategy 3: Invest in sensor reliability and unified safety certification to reduce returns and unlock regulatory-light market entry.
What would change our conclusion: a sustained industry-wide ASP decline below 215 USD with rising unit volumes would signal commoditization and favor scale-over-premium strategies. Precise sub-segment forecasting by price tier and health-analytics adoption requires the full report's granular models.
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product
5.1.1. Single Cat
5.1.2. Multi Cat
5.2. Market Analysis, Insights and Forecast - by Buyer Type
5.2.1. Residential
5.2.2. Commercial
5.2.3. Institutional
5.3. Market Analysis, Insights and Forecast - by Distribution Channel
5.3.1. Offline
5.3.2. Online
5.4. Market Analysis, Insights and Forecast - by Technology
5.4.1. Basic Automation
5.4.2. App-Connected
5.4.3. Health-Analytics
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. Latin America
5.5.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product
6.1.1. Single Cat
6.1.2. Multi Cat
6.2. Market Analysis, Insights and Forecast - by Buyer Type
6.2.1. Residential
6.2.2. Commercial
6.2.3. Institutional
6.3. Market Analysis, Insights and Forecast - by Distribution Channel
6.3.1. Offline
6.3.2. Online
6.4. Market Analysis, Insights and Forecast - by Technology
6.4.1. Basic Automation
6.4.2. App-Connected
6.4.3. Health-Analytics
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product
7.1.1. Single Cat
7.1.2. Multi Cat
7.2. Market Analysis, Insights and Forecast - by Buyer Type
7.2.1. Residential
7.2.2. Commercial
7.2.3. Institutional
7.3. Market Analysis, Insights and Forecast - by Distribution Channel
7.3.1. Offline
7.3.2. Online
7.4. Market Analysis, Insights and Forecast - by Technology
7.4.1. Basic Automation
7.4.2. App-Connected
7.4.3. Health-Analytics
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product
8.1.1. Single Cat
8.1.2. Multi Cat
8.2. Market Analysis, Insights and Forecast - by Buyer Type
8.2.1. Residential
8.2.2. Commercial
8.2.3. Institutional
8.3. Market Analysis, Insights and Forecast - by Distribution Channel
8.3.1. Offline
8.3.2. Online
8.4. Market Analysis, Insights and Forecast - by Technology
8.4.1. Basic Automation
8.4.2. App-Connected
8.4.3. Health-Analytics
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product
9.1.1. Single Cat
9.1.2. Multi Cat
9.2. Market Analysis, Insights and Forecast - by Buyer Type
9.2.1. Residential
9.2.2. Commercial
9.2.3. Institutional
9.3. Market Analysis, Insights and Forecast - by Distribution Channel
9.3.1. Offline
9.3.2. Online
9.4. Market Analysis, Insights and Forecast - by Technology
9.4.1. Basic Automation
9.4.2. App-Connected
9.4.3. Health-Analytics
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product
10.1.1. Single Cat
10.1.2. Multi Cat
10.2. Market Analysis, Insights and Forecast - by Buyer Type
10.2.1. Residential
10.2.2. Commercial
10.2.3. Institutional
10.3. Market Analysis, Insights and Forecast - by Distribution Channel
10.3.1. Offline
10.3.2. Online
10.4. Market Analysis, Insights and Forecast - by Technology
10.4.1. Basic Automation
10.4.2. App-Connected
10.4.3. Health-Analytics
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Whisker (Litter-Robot)
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. PETKIT
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. CATLINK
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. PetSafe
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Neakasa
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Automatic Self Cleaning Cat Litter Box Market Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: Automatic Self Cleaning Cat Litter Box Market Volume Breakdown (Million Units, %) by Region 2026 & 2034
Figure 3: North America Automatic Self Cleaning Cat Litter Box Market Revenue (Million), by Product 2026 & 2034
Figure 4: North America Automatic Self Cleaning Cat Litter Box Market Volume (Million Units), by Product 2026 & 2034
Figure 5: North America Automatic Self Cleaning Cat Litter Box Market Revenue Share (%), by Product 2026 & 2034
Figure 6: North America Automatic Self Cleaning Cat Litter Box Market Volume Share (%), by Product 2026 & 2034
Figure 7: North America Automatic Self Cleaning Cat Litter Box Market Revenue (Million), by Buyer Type 2026 & 2034
Figure 8: North America Automatic Self Cleaning Cat Litter Box Market Volume (Million Units), by Buyer Type 2026 & 2034
Figure 9: North America Automatic Self Cleaning Cat Litter Box Market Revenue Share (%), by Buyer Type 2026 & 2034
Figure 10: North America Automatic Self Cleaning Cat Litter Box Market Volume Share (%), by Buyer Type 2026 & 2034
Figure 11: North America Automatic Self Cleaning Cat Litter Box Market Revenue (Million), by Distribution Channel 2026 & 2034
Figure 12: North America Automatic Self Cleaning Cat Litter Box Market Volume (Million Units), by Distribution Channel 2026 & 2034
Figure 13: North America Automatic Self Cleaning Cat Litter Box Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 14: North America Automatic Self Cleaning Cat Litter Box Market Volume Share (%), by Distribution Channel 2026 & 2034
North America Automatic Self Cleaning Cat Litter Box Market Revenue (Million), by Technology 2026 & 2034
List of Tables
Table 1: Automatic Self Cleaning Cat Litter Box Market Revenue Million Forecast, by Product 2020 & 2034
Table 2: Automatic Self Cleaning Cat Litter Box Market Volume Million Units Forecast, by Product 2020 & 2034
Table 3: Automatic Self Cleaning Cat Litter Box Market Revenue Million Forecast, by Buyer Type 2020 & 2034
Table 4: Automatic Self Cleaning Cat Litter Box Market Volume Million Units Forecast, by Buyer Type 2020 & 2034
Table 5: Automatic Self Cleaning Cat Litter Box Market Revenue Million Forecast, by Distribution Channel 2020 & 2034
Table 6: Automatic Self Cleaning Cat Litter Box Market Volume Million Units Forecast, by Distribution Channel 2020 & 2034
Table 7: Automatic Self Cleaning Cat Litter Box Market Revenue Million Forecast, by Technology 2020 & 2034
Table 8: Automatic Self Cleaning Cat Litter Box Market Volume Million Units Forecast, by Technology 2020 & 2034
Table 9: Automatic Self Cleaning Cat Litter Box Market Revenue Million Forecast, by Region 2020 & 2034
Table 10: Automatic Self Cleaning Cat Litter Box Market Volume Million Units Forecast, by Region 2020 & 2034
Table 11: North America Automatic Self Cleaning Cat Litter Box Market Revenue Million Forecast, by Product 2020 & 2034
Table 12: North America Automatic Self Cleaning Cat Litter Box Market Volume Million Units Forecast, by Product 2020 & 2034
Table 13: North America Automatic Self Cleaning Cat Litter Box Market Revenue Million Forecast, by Buyer Type 2020 & 2034
Table 14: North America Automatic Self Cleaning Cat Litter Box Market Volume Million Units Forecast, by Buyer Type 2020 & 2034
North America Automatic Self Cleaning Cat Litter Box Market Revenue Million Forecast, by Distribution Channel 2020 & 2034
Frequently Asked Questions
1. How big is the automatic self-cleaning cat litter box market?
The global automatic self-cleaning cat litter box market was valued at approximately 702–719 Million USD in 2025. It is projected to reach 1.19 Billion by 2032 at a 7.5% CAGR as connected, health-monitoring features gain adoption.
2. What is the fastest-growing segment?
Multi-cat automatic self-cleaning litter boxes are the fastest-growing product segment, forecast at roughly 8.9% CAGR, driven by rising multi-cat household adoption and demand for higher-capacity automated waste systems.
3. Which region dominates the market?
North America dominates with about 36.5% of 2025 global revenue, supported by 49 million US cat-owning households and high premium-pet expenditure. Asia-Pacific is the fastest-growing region, led by China.
4. Who are the main players in the market?
Whisker (Litter-Robot), PETKIT, CATLINK, PetSafe, and Neakasa are the leading vendors in a fragmented field of over 600 players, competing on sensor reliability, connected analytics, and price-tier coverage.
5. What is driving market growth?
Growth is driven by convenience demand from time-poor dual-income households, rising cat ownership, growing awareness of pet hygiene and health, and integration with smart-home ecosystems. High upfront cost remains the primary restraint.
6. Is online or offline the dominant distribution channel?
Offline retail held roughly 57.5–58% of 2025 sales, favored for hands-on product evaluation. However, online is the fastest-growing channel, supported by DTC brands and marketplaces like Amazon and Chewy.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis employs a 70/30 primary-to-secondary split, prioritizing direct industry engagement. We conducted in-depth interviews with stakeholders across the value chain, including component and sensor suppliers, specialized automated-pet-appliance producers, contract manufacturers and formulators, and global distributors and retailers. Interviewees specifically included VP-level Sourcing leads, Heads of R&D and Product Engineering, Technical Directors overseeing sensor and IoT reliability, and Commercial Operations Leads managing DTC and retail channels. This fieldwork validated pricing tiers, unit-economics, and channel dynamics at the product and brand level.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Product Engineering Heads
40%
Procurement & Sourcing Directors
30%
Commercial Operations Leads
20%
Quality & Regulatory Managers
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Component & Sensor Suppliers
30%
Automated-Appliance Producers
40%
Distributors & Retailers
20%
E-commerce & DTC Operators
10%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate filings and annual investor presentations (10-K, SEC), patent databases for automated waste and sensing technology, and recognized non-profit technical standards and industry associations. We cross-check shipment and pricing data against published regulatory and consumer-product safety frameworks.
Demand Modeling & Market Sizing Triangulation
We apply simultaneous Top-Down (macroeconomic pet-spend allocation and region-level consumer-electronics penetration) and Bottom-Up (manufacturer capacity, unit shipments, blended ASP, and end-use consumption modeling) triangulation. Convergent estimates are reconciled to produce a defensible base-year value and forecast band.
 Automatic Self Cleaning Cat Litter Box Market