Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Nitrobenzene Market Size, Share & Forecast to 2032
Nitrobenzene Market Size, Share & Forecast to 2032
Nitrobenzene Market
Nitrobenzene Market Size, Share & Forecast to 2032
Nitrobenzene Market by Application (Aniline Production, Pesticide Additive, Synthetic Rubber Manufacturing, Paint Solvent, Pharmaceutical Intermediates, Dyes & Pigments), by End Use (Construction, Automotive, Agriculture, Pharmaceuticals, Cosmetics, Others), by Process (Liquid-Phase Nitration, Vapor-Phase Nitration), by Grade (Prime Grade, Crude Grade), by Asia Pacific (China, India, Japan, South Korea, Singapore, Malaysia, Thailand, Indonesia, Australia), by North America (USA, Canada, Mexico), by Europe (Germany, France, UK, Netherlands, Belgium, Russia, Italy, Spain, Turkey), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Egypt, Israel), by South America (Brazil, Argentina) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 214
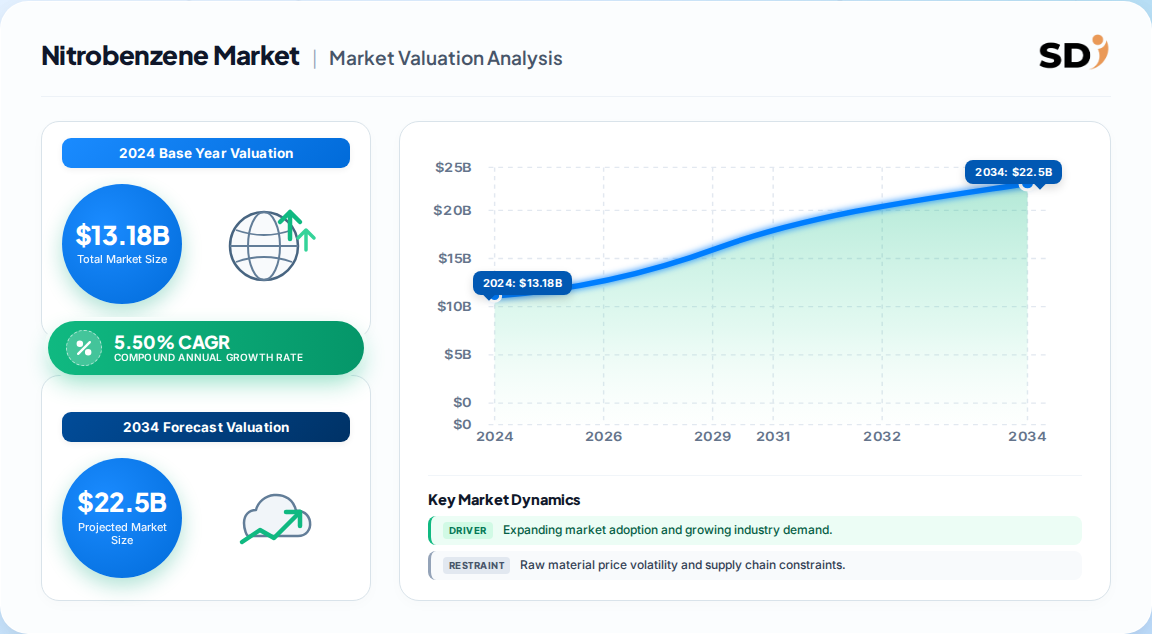
Market size: The global nitrobenzene market was valued at 13.18 Billion USD in 2024, with an estimated 13.9 Billion USD in 2025, depending on base-year convention.
Forecast: Projected to reach 20.23 Billion USD by 2032, implying roughly 6.18 Billion USD of incremental value creation across the aniline–MDI–polyurethane chain.
CAGR: Mid-single-digit growth of 5.50% (2025–2032) is the consensus baseline; conservative estimates sit near 2.9%, aggressive price-led cases near 5.0%.
Leading segment: Aniline production dominates with 78.5%–90% of consumption, as the sole industrial-scale route to MDI and polyurethane foams.
Leading region:Asia-Pacific holds ~44.7% of global revenue, anchored by China's nitrobenzene and MDI capacity and India's aniline expansion.
Key players: BASF, Covestro, Wanhua Chemical, Huntsman, Sinopec, Sumitomo Chemical, GNFC, and Atul lead an integrated, moderately concentrated field.
Why this matters for decision-makers: Nitrobenzene demand is contractually tethered to MDI capacity decisions, so buyers who procure without visibility into upstream benzene integration and downstream foam specifications face structural price and availability risk.
Nitrobenzene Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
13.18 B
2024
13.90 B
2025
14.67 B
2026
15.48 B
2027
16.33 B
2028
17.23 B
2029
18.18 B
2030
Nitrobenzene Market Size (In Billion)
Year
Market Size
2024
13.18 B
2025
13.90 B
2026
14.67 B
2027
15.48 B
2028
16.33 B
2029
17.23 B
2030
18.18 B
What is the Nitrobenzene Market?
The nitrobenzene market covers the global production and trade of C6H5NO2, a yellow oily aromatic compound made by benzene nitration. Over 85% converts to aniline, which feeds MDI and polyurethane foams for insulation, automotive parts, and furniture. Dyes, pesticides, and pharmaceutical intermediates absorb the remainder.
Scope: what this report covers and excludes
This analysis covers global nitrobenzene production volume and value, application segments (aniline/MDI, dyes and pigments, pesticides, pharmaceutical intermediates, solvents), end-use verticals (construction, automotive, agriculture, pharmaceuticals, cosmetics), process routes (liquid-phase and vapor-phase nitration), and regional consumption across five continents.
This analysis does not cover downstream aniline, MDI, or finished polyurethane foam markets as standalone sizing exercises, nor does it size benzene or nitric acid feedstock markets independently. Nitrobenzene derivatives beyond aniline are referenced only where they materially shift precursor demand.
How big is the market for Nitrobenzene Market?
Nitrobenzene is a mid-single-digit-growth petrochemical intermediate worth roughly 13–14 Billion USD today, with forecasts clustering between 3% and 5.6% CAGR depending on base year, currency treatment, and whether value or volume is the primary anchor. Volume estimates run near 12.65 million tons in 2025.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
9.3 → 14.3 Billion USD
2019
2027
5.6%
Value, all applications
One published estimate
13.18 → 20.23 Billion USD
2024
2032
5.50%
Value, application + end user
A competing analysis
10.50 → 13.97 Billion USD
2026
2036
2.9%
Value, aniline/MDI-centric
A conservative forecast
10.5 → 15.7 Billion USD
2025
2035
3.9%
Value, product grade mix
An alternative outlook
12.65 → 15.58 Million tons
2025
2030
4.26%
Volume, all applications
A volume-based forecast
13.2 → 20.8 Billion USD
2025
2034
5.02%
Value, price-linked index
A pricing-focused source
The most defensible figure for 2024 is 13.18 Billion USD, because it is the most recent explicit base-year valuation and reconciles with the 5.5% CAGR midpoint. The lower 2.9% case reflects captive-chain pricing where value is largely a benzene pass-through; the higher 5.6% case leans on aniline capacity additions in Asia. Our analysis suggests buyers should anchor planning on 5.0%–5.5% with volume growth of roughly 4%, treating headline value CAGR as an upper bound inflated by feedstock price recovery.
How is the market segmented?
Segmentation keyed to application reveals that nitrobenzene is effectively an aniline market with a specialty fringe: more than three-quarters of consumption flows into MDI-bound aniline, while dyes, agrochemicals, and pharma intermediates split the residual. Process route is almost entirely liquid-phase nitration.
Implication: the specialty sub-segments (dyes, pharma) are small but higher-margin and less cyclically tethered to construction, making them the natural beachhead for merchant producers without captive MDI offtake.
Which region leads in the Nitrobenzene Market?
Asia-Pacific leads, holding roughly 44.7% of global revenue in 2024 and accounting for the majority of both capacity and consumption. China alone anchors production, while India is adding aniline upstream capacity at scale; the region is also the fastest-growing, per every published outlook.
Nitrobenzene Market Regional Market Share
Loading chart...
Nitrobenzene Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.47%
North America
0.19%
Europe
0.18%
Middle East & Africa
0.08%
South America
0.08%
Parent
Children
Asia-Pacific
China, India, Japan, South Korea, Singapore, Malaysia, Thailand, Indonesia, Australia
North America
USA, Canada, Mexico
Europe
Germany, France, UK, Netherlands, Belgium, Russia, Italy, Spain, Turkey
Middle East & Africa
Saudi Arabia, UAE, South Africa, Egypt, Israel
South America
Brazil, Argentina
The country-level growth hierarchy is instructive: USA leads at 3.4% CAGR on insulation-code upgrades, Mexico at 3.1% on industrial construction, Germany at 2.8% on energy renovation mandates. This profile implies mature-market value growth is retrofit-driven, not new-build-driven, which materially changes demand timing and specification risk.
What is driving growth — and what is holding it back?
Growth is structurally tied to aniline-to-MDI-to-polyurethane foam demand, amplified by building energy-efficiency mandates that favor rigid polyurethane insulation, plus pharmaceutical demand for paracetamol intermediates. Restraints are regulatory and substitutionary: EPA and EU REACH pressure, bio-based alternatives, and benzene feedstock volatility.
Factor
Direction
Evidence Strength
Mechanism
Aniline/MDI capacity additions in Asia
Positive
High
Captive volume pull-through
Building energy-code insulation mandates
Positive
High
Rigid foam specification advantage
Automotive lightweighting programmes
Positive
Medium
Flexible foam seating, structural parts
Paracetamol and pharma intermediate demand
Positive
Medium
Aniline route to acetaminophen
EPA/REACH and carcinogenicity classification
Negative
High
Compliance capex, relocation pressure
Bio-based and green chemistry substitution
Negative
Low–Medium
Emerging, publicly funded R&D
Benzene and nitric acid price volatility
Negative
High
Margin pass-through compression
US–China trade friction on feedstocks
Negative
Medium
Supply chain re-routing costs
The balance favors growth: construction-linked demand is policy-insulated rather than consumer-discretionary, meaning nitrobenzene should outgrow the underlying construction cycle modestly. The critical caveat, per our analysis, is that supply discipline matters more than demand — excess capacity in China has repeatedly flipped local prices bearish even while global value grew, as the Northeast Asia price path from 1.17 USD/KG (Dec 2025) to 1.18 USD/KG (Mar 2026) to 1.76 USD/KG (Sep 2026) demonstrates. Value growth and spot-price growth diverge; procurement strategy must model both.
Who are the leading vendors?
The field is moderately concentrated and vertically integrated: the largest names are also the largest MDI and polyurethane producers, meaning nitrobenzene is a strategic internal intermediate rather than a merchant commodity. Merchant supply is a thin residual outside China and India.
Company
HQ
Position / Moat
BASF
Germany
Integrated benzene-to-MDI; global scale, process IP
Merchant and domestic supply, Indian aniline chain
Atul
India
Specialty chemicals diversification
Differentiation rests on feedstock integration, nitration plant scale, and captive aniline conversion efficiency — not on product differentiation. This implies that price competition is structural and that non-integrated buyers hold limited bargaining power.
What do buyers and operators need to know?
Procurement of nitrobenzene is not a conventional commodity purchase. Because over three-quarters of output is captively converted inside integrated MDI chains, merchant availability is narrow and concentrated among a handful of Asian and Indian sellers. Buyers should verify supplier benzene integration rather than accept spot quotations at face value.
Regulatory compliance is mission-critical: nitrobenzene is classified as toxic and potentially carcinogenic, with EPA and REACH obligations governing handling, transport, and emissions that flow through to buyer audit liability. Switching costs are high — requalification of a nitrobenzene source typically requires revalidation of downstream aniline purity and, in pharma routes, regulatory filings for paracetamol intermediates.
Operationally, logistics matter: bulk chemical carriers, port handling charges, and customs clearance materially affect landed cost, and these variables moved independently of underlying demand in recent quarters. Buyers should contract on CIF terms with explicit indexation to benzene feedstock and monitor Chinese capacity utilization as the single most predictive supply-side indicator.
Strategic Recommendations & Analyst Perspective
The weight of evidence favors Asia-Pacific-led, mid-single-digit value growth of roughly 5.5% CAGR through 2032, with volume growth of about 4%. The strongest counter-argument is the conservative 2.9% case: if nitrobenzene remains structurally captive and pricing stays a pure benzene pass-through, then headline dollar growth overstates real demand expansion, and merchant-market participants face a structurally flat pool of volume. We take the middle path — value growth near 5%, volume growth near 4% — but flag that the divergence between the two is itself the key signal.
Our judgment is that the market's center of gravity is shifting from production economics to specification economics. Building energy codes in the EU, North America, and East Asia are the binding constraint on rigid polyurethane insulation demand, and therefore on MDI, and therefore on nitrobenzene. This means capacity decisions made without visibility into local code implementation timelines are effectively speculative. A second-order effect: India's aniline and paracetamol expansion, including paracetamol para-aminophenol approvals from nitrobenzene feedstock, could create the first meaningful non-Chinese merchant supply pool in a decade.
Actionable Strategy
Integrated producers: Time nitrobenzene capacity additions to MDI insulation demand tied to code implementation schedules, not to GDP growth; avoid adding merchant capacity without offtake.
Specialty buyers: Secure multi-year contracts with Indian merchant producers to hedge Chinese supply concentration and protect against regulatory relocation shocks.
Investors: Underwrite on volume growth (~4%), not value CAGR; feedstock price recovery, not demand, explains most of the gap between 4% and 5.5%.
What would change our conclusion: a decisive EU or US regulatory reclassification of nitrobenzene tightening handling standards, or a rapid commercial scale-up of bio-based aniline, either of which would compress merchant demand faster than capacity adjusts.
While this overview covers the strategic arc, precise sub-segment forecasting — by grade, process route, and country-level end-use — requires the full report's granular modeling and price-index series.
Nitrobenzene Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Nitrobenzene Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.50% from 2020-2034
Segmentation
By Application
Aniline Production
Pesticide Additive
Synthetic Rubber Manufacturing
Paint Solvent
Pharmaceutical Intermediates
Dyes & Pigments
By End Use
Construction
Automotive
Agriculture
Pharmaceuticals
Cosmetics
Others
By Process
Liquid-Phase Nitration
Vapor-Phase Nitration
By Grade
Prime Grade
Crude Grade
By Geography
Asia Pacific
China
India
Japan
South Korea
Singapore
Malaysia
Thailand
Indonesia
Australia
North America
USA
Canada
Mexico
Europe
Germany
France
UK
Netherlands
Belgium
Russia
Italy
Spain
Turkey
Middle East & Africa
Saudi Arabia
UAE
South Africa
Egypt
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Application
5.1.1. Aniline Production
5.1.2. Pesticide Additive
5.1.3. Synthetic Rubber Manufacturing
5.1.4. Paint Solvent
5.1.5. Pharmaceutical Intermediates
5.1.6. Dyes & Pigments
5.2. Market Analysis, Insights and Forecast - by End Use
5.2.1. Construction
5.2.2. Automotive
5.2.3. Agriculture
5.2.4. Pharmaceuticals
5.2.5. Cosmetics
5.2.6. Others
5.3. Market Analysis, Insights and Forecast - by Process
5.3.1. Liquid-Phase Nitration
5.3.2. Vapor-Phase Nitration
5.4. Market Analysis, Insights and Forecast - by Grade
5.4.1. Prime Grade
5.4.2. Crude Grade
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. Asia Pacific
5.5.2. North America
5.5.3. Europe
5.5.4. Middle East & Africa
5.5.5. South America
6. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Application
6.1.1. Aniline Production
6.1.2. Pesticide Additive
6.1.3. Synthetic Rubber Manufacturing
6.1.4. Paint Solvent
6.1.5. Pharmaceutical Intermediates
6.1.6. Dyes & Pigments
6.2. Market Analysis, Insights and Forecast - by End Use
6.2.1. Construction
6.2.2. Automotive
6.2.3. Agriculture
6.2.4. Pharmaceuticals
6.2.5. Cosmetics
6.2.6. Others
6.3. Market Analysis, Insights and Forecast - by Process
6.3.1. Liquid-Phase Nitration
6.3.2. Vapor-Phase Nitration
6.4. Market Analysis, Insights and Forecast - by Grade
6.4.1. Prime Grade
6.4.2. Crude Grade
7. North America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Application
7.1.1. Aniline Production
7.1.2. Pesticide Additive
7.1.3. Synthetic Rubber Manufacturing
7.1.4. Paint Solvent
7.1.5. Pharmaceutical Intermediates
7.1.6. Dyes & Pigments
7.2. Market Analysis, Insights and Forecast - by End Use
7.2.1. Construction
7.2.2. Automotive
7.2.3. Agriculture
7.2.4. Pharmaceuticals
7.2.5. Cosmetics
7.2.6. Others
7.3. Market Analysis, Insights and Forecast - by Process
7.3.1. Liquid-Phase Nitration
7.3.2. Vapor-Phase Nitration
7.4. Market Analysis, Insights and Forecast - by Grade
7.4.1. Prime Grade
7.4.2. Crude Grade
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Application
8.1.1. Aniline Production
8.1.2. Pesticide Additive
8.1.3. Synthetic Rubber Manufacturing
8.1.4. Paint Solvent
8.1.5. Pharmaceutical Intermediates
8.1.6. Dyes & Pigments
8.2. Market Analysis, Insights and Forecast - by End Use
8.2.1. Construction
8.2.2. Automotive
8.2.3. Agriculture
8.2.4. Pharmaceuticals
8.2.5. Cosmetics
8.2.6. Others
8.3. Market Analysis, Insights and Forecast - by Process
8.3.1. Liquid-Phase Nitration
8.3.2. Vapor-Phase Nitration
8.4. Market Analysis, Insights and Forecast - by Grade
8.4.1. Prime Grade
8.4.2. Crude Grade
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Application
9.1.1. Aniline Production
9.1.2. Pesticide Additive
9.1.3. Synthetic Rubber Manufacturing
9.1.4. Paint Solvent
9.1.5. Pharmaceutical Intermediates
9.1.6. Dyes & Pigments
9.2. Market Analysis, Insights and Forecast - by End Use
9.2.1. Construction
9.2.2. Automotive
9.2.3. Agriculture
9.2.4. Pharmaceuticals
9.2.5. Cosmetics
9.2.6. Others
9.3. Market Analysis, Insights and Forecast - by Process
9.3.1. Liquid-Phase Nitration
9.3.2. Vapor-Phase Nitration
9.4. Market Analysis, Insights and Forecast - by Grade
9.4.1. Prime Grade
9.4.2. Crude Grade
10. South America Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Application
10.1.1. Aniline Production
10.1.2. Pesticide Additive
10.1.3. Synthetic Rubber Manufacturing
10.1.4. Paint Solvent
10.1.5. Pharmaceutical Intermediates
10.1.6. Dyes & Pigments
10.2. Market Analysis, Insights and Forecast - by End Use
10.2.1. Construction
10.2.2. Automotive
10.2.3. Agriculture
10.2.4. Pharmaceuticals
10.2.5. Cosmetics
10.2.6. Others
10.3. Market Analysis, Insights and Forecast - by Process
10.3.1. Liquid-Phase Nitration
10.3.2. Vapor-Phase Nitration
10.4. Market Analysis, Insights and Forecast - by Grade
10.4.1. Prime Grade
10.4.2. Crude Grade
11. Competitive Analysis
11.1. Company Profiles
11.1.1. BASF
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Covestro
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Wanhua Chemical
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Huntsman International
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Sinopec
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Sumitomo Chemical
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. GNFC
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Atul
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
12. Research Methodology
List of Figures
Figure 1: Nitrobenzene Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Nitrobenzene Market Volume Breakdown (Million Tons, %) by Region 2026 & 2034
Figure 3: Asia Pacific Nitrobenzene Market Revenue (Billion), by Application 2026 & 2034
Figure 4: Asia Pacific Nitrobenzene Market Volume (Million Tons), by Application 2026 & 2034
Figure 5: Asia Pacific Nitrobenzene Market Revenue Share (%), by Application 2026 & 2034
Figure 6: Asia Pacific Nitrobenzene Market Volume Share (%), by Application 2026 & 2034
Figure 7: Asia Pacific Nitrobenzene Market Revenue (Billion), by End Use 2026 & 2034
Figure 8: Asia Pacific Nitrobenzene Market Volume (Million Tons), by End Use 2026 & 2034
Figure 9: Asia Pacific Nitrobenzene Market Revenue Share (%), by End Use 2026 & 2034
Figure 10: Asia Pacific Nitrobenzene Market Volume Share (%), by End Use 2026 & 2034
Figure 11: Asia Pacific Nitrobenzene Market Revenue (Billion), by Process 2026 & 2034
Figure 12: Asia Pacific Nitrobenzene Market Volume (Million Tons), by Process 2026 & 2034
Figure 13: Asia Pacific Nitrobenzene Market Revenue Share (%), by Process 2026 & 2034
Figure 14: Asia Pacific Nitrobenzene Market Volume Share (%), by Process 2026 & 2034
Figure 15: Asia Pacific Nitrobenzene Market Revenue (Billion), by Grade 2026 & 2034
Figure 16: Asia Pacific Nitrobenzene Market Volume (Million Tons), by Grade 2026 & 2034
Asia Pacific Nitrobenzene Market Revenue Share (%), by Grade 2026 & 2034
Table 8: Nitrobenzene Market Volume Million Tons Forecast, by Grade 2020 & 2034
Table 9: Nitrobenzene Market Revenue Billion Forecast, by Region 2020 & 2034
Table 10: Nitrobenzene Market Volume Million Tons Forecast, by Region 2020 & 2034
Table 11: Asia Pacific Nitrobenzene Market Revenue Billion Forecast, by Application 2020 & 2034
Table 12: Asia Pacific Nitrobenzene Market Volume Million Tons Forecast, by Application 2020 & 2034
Table 13: Asia Pacific Nitrobenzene Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 14: Asia Pacific Nitrobenzene Market Volume Million Tons Forecast, by End Use 2020 & 2034
Table 15: Asia Pacific Nitrobenzene Market Revenue Billion Forecast, by Process 2020 & 2034
Table 16: Asia Pacific Nitrobenzene Market Volume Million Tons Forecast, by Process 2020 & 2034
Asia Pacific Nitrobenzene Market Revenue Billion Forecast, by Grade 2020 & 2034
Frequently Asked Questions
1. What is the nitrobenzene market size in 2024?
The global nitrobenzene market was valued at approximately 13.18 Billion USD in 2024, with an estimated 13.9 Billion USD in 2025. This represents the most recent explicit base-year valuation and underpins the 5.50% consensus CAGR forecast through 2032.
2. What is the nitrobenzene market growth rate?
Consensus forecasts cluster around a 5.5% CAGR for 2025–2032, reaching roughly 20.23 Billion USD by 2032. Conservative outlooks sit near 2.9%, reflecting captive pricing structures where value largely passes through benzene feedstock costs rather than reflecting independent demand expansion.
3. Which application dominates nitrobenzene consumption?
Aniline production dominates, accounting for roughly 78.5% to 90% of global nitrobenzene consumption. Aniline is the sole industrial-scale precursor to MDI, which feeds polyurethane foams for construction insulation, automotive seating, and furniture applications worldwide.
4. Which region leads the nitrobenzene market?
Asia-Pacific leads with approximately 44.7% of global revenue, driven by China's production and MDI capacity and India's expanding aniline sector. It is also the fastest-growing region, with all published forecasts pointing to continued Asia-Pacific dominance through 2032.
5. Who are the leading nitrobenzene producers?
Key producers include BASF, Covestro, Wanhua Chemical, Huntsman International, Sinopec, Sumitomo Chemical, GNFC, and Atul. Competition centers on benzene feedstock integration, nitration plant scale, and captive aniline conversion efficiency rather than product differentiation.
6. What are the main challenges facing the nitrobenzene market?
Principal challenges include stringent EPA and REACH regulations citing nitrobenzene toxicity and carcinogenicity, volatile benzene and nitric acid feedstock costs, growing bio-based chemical substitution, and US–China trade friction that disrupts feedstock supply chains.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split, with fieldwork prioritized to capture the opaque, captive nature of nitrobenzene trade. In-depth interviews were conducted across the value chain with raw material suppliers (benzene and nitric acid), specialized nitrobenzene and aniline producers, contract formulators serving dye and agrochemical buyers, and global chemical distributors. Decision-maker designations interviewed included VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads across Asia-Pacific, Europe, and North America.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing Directors
38%
R&D & Technical Directors
30%
Commercial Operations Leads
20%
Regulatory & Compliance Managers
12%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Nitrobenzene & Aniline Producers
42%
Raw Material & Feedstock Suppliers
28%
Formulators & End-Use Converters
18%
Distributors & Traders
12%
Secondary Benchmarking & Public Trade Validation
Secondary data was triangulated against official multilateral trade databases (UN Comtrade, WTO tariff schedules, US ITC, Eurostat chemical trade flows), corporate annual filings and 10-K submissions, investor presentations from integrated MDI producers, patent databases tracking nitration process innovations, and recognized technical standards and industry associations governing chemical handling and transport.
Demand Modeling & Market Sizing Triangulation
Market sizing applies simultaneous Top-Down allocation (macroeconomic construction and automotive output, segment-level chemical consumption intensity) and Bottom-Up modeling (plant capacity mapping, grade-level pricing, and end-use consumption reconstruction). The two paths are reconciled to within a narrow tolerance band before any figure is published.
 Nitrobenzene Market