Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Personal Computers Market Size, Share & Forecast to 2031
Personal Computers Market
Personal Computers Market Size, Share & Forecast to 2031
Personal Computers Market by Form Factor (Laptops/Notebooks, Desktop Towers & SFF, Tablets, Hybrid/2-in-1 Devices), by End-User (Consumers, Small & Medium Enterprise, Large Enterprise, Government & Education), by Price Band (Entry-Level (<USD 600), Mid-Range (USD 600–1, 200), Premium (>USD 1, 200)), by Processor Architecture (x86 (Intel-AMD), ARM-Based, RISC-V & Other), by Distribution Channel (Online, Offline), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Netherlands), by Asia-Pacific (China, Japan, India, South Korea, Taiwan, Australia), by Latin America (Brazil, Argentina, Colombia, Chile), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Egypt, Nigeria) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 180
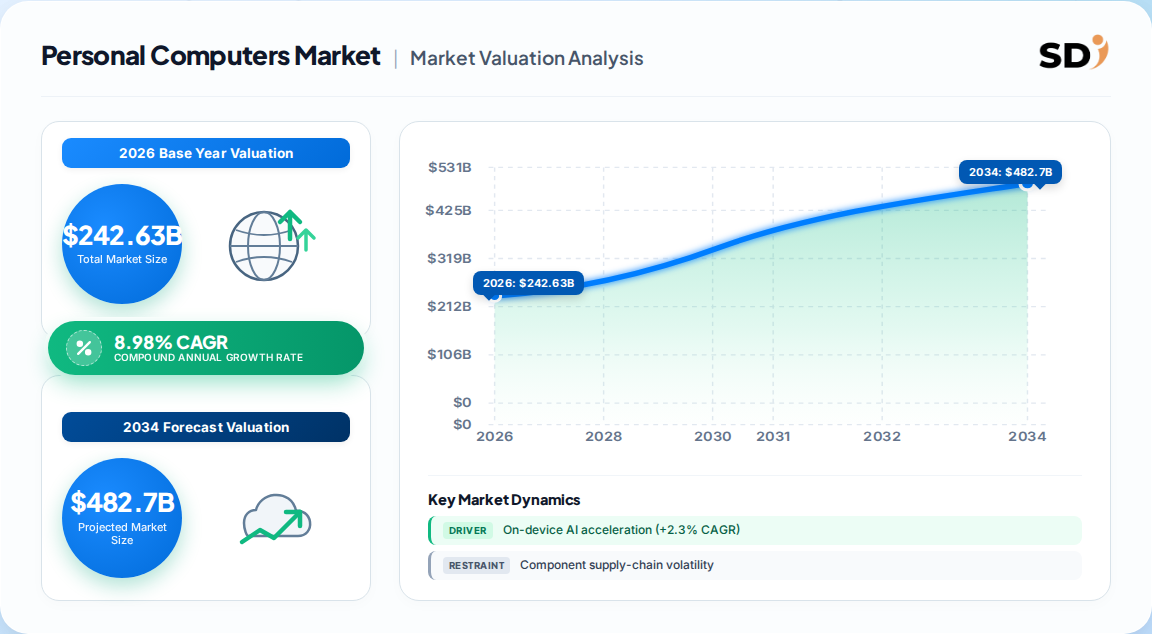
USD 242.63 billion in 2026, the global Personal Computers Market is forecast to reach USD 372.68 billion by 2031, expanding at 8.98% CAGR.
Notebooks dominate with 77.44% of 2025 shipments; AI-optimized laptops are the fastest-growing form factor at 11.66% CAGR.
Asia-Pacific leads with 36.71% revenue share (2025); Africa is the fastest-growing region at 10.58% CAGR through 2031.
Lenovo leads vendors at 25.5% unit share (2024), followed by HP (21.6%) and Dell (16.1%).
Commercial end-users hold the majority of demand, but consumer gaming and esports devices are growing faster at 10.74% CAGR.
On-device AI acceleration is the single largest growth driver, adding an estimated +2.3% to CAGR through the forecast period.
Why this matters for decision-makers: The market is shifting from volume recovery to value capture—vendors that fail to embed NPUs and premium thermal designs into mid-range models risk margin compression as AI-enabled replacements command price premiums.
Personal Computers Market Size (In Billion)
400.0B
300.0B
200.0B
100.0B
0
204.2 B
2024
222.6 B
2025
242.6 B
2026
264.4 B
2027
288.2 B
2028
314.0 B
2029
342.2 B
2030
Personal Computers Market Size (In Billion)
Year
Market Size
2024
204.2 B
2025
222.6 B
2026
242.6 B
2027
264.4 B
2028
288.2 B
2029
314.0 B
2030
342.2 B
What is the Personal Computers Market?
The personal computers market encompasses the global sale of general-purpose computing devices—desktops, notebooks, workstations, tablets, and 2-in-1 hybrids—designed for direct individual use by consumers, businesses, and institutions. It excludes smartphones, servers, and dedicated gaming consoles, though 2-in-1 detachables meeting PC form-factor definitions are included.
Scope: what this report covers and excludes
This analysis covers global PC hardware revenue across laptops/notebooks, desktops, workstations, tablets, and hybrid devices, segmented by end-use (consumer, commercial, industrial), distribution channel (online, offline), processor architecture, and price band. This analysis does not cover smartphones, standalone monitors, peripherals, enterprise servers, or software and cloud services attached to PC ecosystems.
How big is the market for Personal Computers Market?
Estimates for the personal computers market diverge meaningfully because of differing base years, category definitions, and whether tablets and workstations are included. The table below compares the three most-cited benchmarks.
Our analysis suggests the USD 242.63 billion (2026) figure is most defensible for strategic planning because it (a) anchors to the most recent demand cycle, (b) excludes tablets that increasingly overlap with smartphones, and (c) reflects the post-2024 refresh cycle now underway. The lower legacy estimates understate current market value because they were struck during the 2023 trough.
How is the market segmented?
Segmentation in the personal computers market is unusually rich because form factor, processor architecture, and price band each map to distinct buyer economics. The non-geographic segmentation below reflects the current consensus structure.
Consumers, Small & Medium Enterprise, Large Enterprise, Government & Education
By Price Band
Entry-Level (USD 1,200)
By Processor Architecture
x86 (Intel-AMD), ARM-Based, RISC-V & Other
By Distribution Channel
Online, Offline
Which region leads in Personal Computers Market?
Asia-Pacific leads the personal computers market with 36.71% revenue share in 2025, driven by both manufacturing concentration and rising domestic demand. North America follows as the largest mature market, while Africa posts the fastest growth at 10.58% CAGR through 2031.
Personal Computers Market Regional Market Share
Loading chart...
Personal Computers Market Regional Market Share
Region
Market Share (%)
North America
0.26%
Europe
0.23%
Asia-Pacific
0.38%
South America
0.05%
Middle East & Africa
0.08%
Region
2025 Revenue Share
Asia-Pacific
36.71%
North America
26.0%
Europe
23.0%
Middle East & Africa
8.0%
South America
5.0%
Geography coverage (nested):
North America (USA, Canada, Mexico)
Europe (Germany, UK, France, Italy, Spain, Netherlands)
Asia-Pacific (China, Japan, India, South Korea, Taiwan, Australia)
Latin America (Brazil, Argentina, Colombia, Chile)
Middle East & Africa (Saudi Arabia, UAE, South Africa, Egypt, Nigeria)
The Asia-Pacific concentration is a double-edged sword: it anchors supply-chain resilience but exposes global pricing to regional logistics shocks.
What is driving growth — and what is holding it back?
Growth in the personal computers market is being driven by a rare convergence of three upgrade triggers—AI-capable hardware, Windows 10 end-of-life, and hybrid-work refresh—while supply-chain volatility and smartphone substitution cap upside.
Factor
Direction
Evidence Strength
Mechanism
On-device AI acceleration
Driver (+2.3% CAGR)
High
NPUs >50 TOPS enable local inference, premium replacement cycle
Hybrid-work notebook refresh
Driver (+2.1% CAGR)
High
Performance-optimized notebooks for video-intensive collaboration
Windows 10 EOL (2025)
Driver (+1.9% CAGR)
High
Mandated enterprise refresh across installed base
Gaming & esports performance race
Driver (+1.8% CAGR)
Medium-High
High-margin upgrade cycle; APAC and North America lead
Government digital-education rollouts
Driver (+1.4% CAGR)
Medium
Public-sector bulk purchasing; short-term impact
Component supply-chain volatility
Restraint (-1.6% CAGR)
High
Asia-Pacific manufacturing concentration
Smartphone substitution
Restraint (-1.2% CAGR)
Medium
Casual tasks migrate to mobile in emerging markets
Balance of forces: Our analysis suggests net growth remains robust because the three strongest drivers (AI, hybrid work, Windows EOL) are enterprise-mandated and time-bound, whereas restraints are structural but slow-moving. The critical second-order effect: AI-capable PCs may cannibalize premium gaming rigs at the high end while lifting average selling prices across the mid-range.
Who are the leading vendors?
The personal computers market is moderately concentrated, with the top five vendors controlling roughly 84% of global unit shipments in 2024, up from 78% in 2020—a steady consolidation that raises barriers to entry.
Vendor
HQ
2024 Unit Share
Strategic Positioning
Lenovo
China
25.5%
Volume leader; broad portfolio; strong APAC and enterprise channel
HP
USA
21.6%
Commercial and education strength; premium design (Spectre, EliteBook)
Dell
USA
16.1%
Enterprise and workstation depth; direct-sales model
Gaming (ROG) and creator focus; component integration
Acer
Taiwan
6.9%
Value segment; education and emerging-market reach
Competitive moats: Lenovo, HP, and Dell leverage scale-driven procurement and enterprise channel lock-in. Apple's moat is silicon vertical integration and ecosystem switching costs. Asus and Acer compete on specialization and price agility. Our analysis suggests the AI PC transition will widen the gap between scale leaders and specialists unless the latter secure NPU supply early.
What do buyers and operators need to know?
Procurement decisions in the personal computers market now hinge on four mission-critical criteria: NPU performance (TOPS), battery endurance under real workloads, thermal stability in thin chassis, and total cost of ownership over a 4–5 year refresh cycle. Buyers who anchor on upfront price risk locking into devices that will be obsolete for AI-era workloads within 24 months.
Switching costs are rising. Enterprise fleets standardized on Windows/Intune or Apple Business Manager face multi-year migration friction, making the Windows 10 EOL window a once-in-a-decade opportunity to re-evaluate vendor relationships. Regulatory compliance—particularly EU energy-efficiency and repairability rules—is becoming a procurement gate, favoring vendors with greener supply chains.
Operators should also watch component lead times: Asia-Pacific concentration means a single geopolitical or logistics disruption can add 6–10 weeks to enterprise rollouts. Dual-sourcing and pre-ordering NPU-equipped SKUs is now a risk-management imperative, not a procurement nicety.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a value-capture thesis over a volume-recovery thesis for the personal computers market through 2031. Unit growth is modest—global shipments hovered around 245–270 million annually in 2024–2025—but revenue growth of ~9% CAGR implies average selling prices are rising, driven by AI PCs, premium gaming rigs, and hybrid-work notebooks. The strongest counter-argument is that smartphone substitution and elongated refresh cycles could compress the premium window faster than expected, particularly in emerging markets where entry-level devices dominate. We judge this risk real but secondary: enterprise-mandated upgrades are less elastic than consumer demand.
Our analysis suggests the divergence between 8.0% and 8.98% CAGR forecasts is less about demand and more about definitional treatment of tablets and workstations. Buyers should standardize on a scope that excludes tablets and includes workstations—the configuration most consistent with commercial procurement reality.
Actionable strategy:
Vendors: Prioritize NPU-enabled mid-range notebooks (USD 600–1,200) to capture the premium replacement wave before competitors saturate the segment; this is where 44.32% of 2025 revenue concentrated.
Enterprise buyers: Lock in Windows 10 EOL refresh contracts in 2025–2026 to avoid supply bottlenecks; negotiate multi-year TCO clauses rather than unit-price discounts.
Investors: Favor component suppliers with NPU exposure and thermal-management specialists over pure assembly players, where margins are structurally thinner.
What would change our conclusion: A sustained decline in enterprise IT budgets, or a faster-than-expected ARM-based PC inflection, would shift the balance toward price-led competition and erode the premium thesis. We would also revisit if tablet-PC convergence accelerates beyond 2-in-1 form factors.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a value-capture thesis for the personal computers market through 2031: revenue is growing faster than units because AI PCs, premium gaming, and hybrid-work notebooks are lifting average selling prices. The strongest counter-argument—that smartphone substitution and longer refresh cycles could compress the premium window—is real but secondary, since enterprise-mandated upgrades are less elastic than consumer demand.
Actionable strategy for operators and investors:
Vendors: Prioritize NPU-enabled mid-range notebooks (USD 600–1,200) to capture the premium replacement wave before competitors saturate the segment.
Enterprise buyers: Lock in Windows 10 EOL refresh contracts in 2025–2026 to avoid supply bottlenecks and negotiate TCO clauses rather than unit-price discounts.
Investors: Favor component suppliers with NPU exposure and thermal-management specialists over pure assembly players, where margins are structurally thinner.
What would change our conclusion: A sustained decline in enterprise IT budgets, or a faster-than-expected ARM-based PC inflection, would shift the balance toward price-led competition and erode the premium thesis. We would also revisit if tablet-PC convergence accelerates beyond 2-in-1 form factors.
Personal Computers Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Personal Computers Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 8.98% from 2020-2034
Segmentation
By Form Factor
Laptops/Notebooks
Desktop Towers & SFF
Tablets
Hybrid/2-in-1 Devices
By End-User
Consumers
Small & Medium Enterprise
Large Enterprise
Government & Education
By Price Band
Entry-Level (<USD 600)
Mid-Range (USD 600–1,200)
Premium (>USD 1,200)
By Processor Architecture
x86 (Intel-AMD)
ARM-Based
RISC-V & Other
By Distribution Channel
Online
Offline
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Netherlands
Asia-Pacific
China
Japan
India
South Korea
Taiwan
Australia
Latin America
Brazil
Argentina
Colombia
Chile
Middle East & Africa
Saudi Arabia
UAE
South Africa
Egypt
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Form Factor
5.1.1. Laptops/Notebooks
5.1.2. Desktop Towers & SFF
5.1.3. Tablets
5.1.4. Hybrid/2-in-1 Devices
5.2. Market Analysis, Insights and Forecast - by End-User
5.2.1. Consumers
5.2.2. Small & Medium Enterprise
5.2.3. Large Enterprise
5.2.4. Government & Education
5.3. Market Analysis, Insights and Forecast - by Price Band
5.3.1. Entry-Level (<USD 600)
5.3.2. Mid-Range (USD 600–1,200)
5.3.3. Premium (>USD 1,200)
5.4. Market Analysis, Insights and Forecast - by Processor Architecture
5.4.1. x86 (Intel-AMD)
5.4.2. ARM-Based
5.4.3. RISC-V & Other
5.5. Market Analysis, Insights and Forecast - by Distribution Channel
5.5.1. Online
5.5.2. Offline
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia-Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Form Factor
6.1.1. Laptops/Notebooks
6.1.2. Desktop Towers & SFF
6.1.3. Tablets
6.1.4. Hybrid/2-in-1 Devices
6.2. Market Analysis, Insights and Forecast - by End-User
6.2.1. Consumers
6.2.2. Small & Medium Enterprise
6.2.3. Large Enterprise
6.2.4. Government & Education
6.3. Market Analysis, Insights and Forecast - by Price Band
6.3.1. Entry-Level (<USD 600)
6.3.2. Mid-Range (USD 600–1,200)
6.3.3. Premium (>USD 1,200)
6.4. Market Analysis, Insights and Forecast - by Processor Architecture
6.4.1. x86 (Intel-AMD)
6.4.2. ARM-Based
6.4.3. RISC-V & Other
6.5. Market Analysis, Insights and Forecast - by Distribution Channel
6.5.1. Online
6.5.2. Offline
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Form Factor
7.1.1. Laptops/Notebooks
7.1.2. Desktop Towers & SFF
7.1.3. Tablets
7.1.4. Hybrid/2-in-1 Devices
7.2. Market Analysis, Insights and Forecast - by End-User
7.2.1. Consumers
7.2.2. Small & Medium Enterprise
7.2.3. Large Enterprise
7.2.4. Government & Education
7.3. Market Analysis, Insights and Forecast - by Price Band
7.3.1. Entry-Level (<USD 600)
7.3.2. Mid-Range (USD 600–1,200)
7.3.3. Premium (>USD 1,200)
7.4. Market Analysis, Insights and Forecast - by Processor Architecture
7.4.1. x86 (Intel-AMD)
7.4.2. ARM-Based
7.4.3. RISC-V & Other
7.5. Market Analysis, Insights and Forecast - by Distribution Channel
7.5.1. Online
7.5.2. Offline
8. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Form Factor
8.1.1. Laptops/Notebooks
8.1.2. Desktop Towers & SFF
8.1.3. Tablets
8.1.4. Hybrid/2-in-1 Devices
8.2. Market Analysis, Insights and Forecast - by End-User
8.2.1. Consumers
8.2.2. Small & Medium Enterprise
8.2.3. Large Enterprise
8.2.4. Government & Education
8.3. Market Analysis, Insights and Forecast - by Price Band
8.3.1. Entry-Level (<USD 600)
8.3.2. Mid-Range (USD 600–1,200)
8.3.3. Premium (>USD 1,200)
8.4. Market Analysis, Insights and Forecast - by Processor Architecture
8.4.1. x86 (Intel-AMD)
8.4.2. ARM-Based
8.4.3. RISC-V & Other
8.5. Market Analysis, Insights and Forecast - by Distribution Channel
8.5.1. Online
8.5.2. Offline
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Form Factor
9.1.1. Laptops/Notebooks
9.1.2. Desktop Towers & SFF
9.1.3. Tablets
9.1.4. Hybrid/2-in-1 Devices
9.2. Market Analysis, Insights and Forecast - by End-User
9.2.1. Consumers
9.2.2. Small & Medium Enterprise
9.2.3. Large Enterprise
9.2.4. Government & Education
9.3. Market Analysis, Insights and Forecast - by Price Band
9.3.1. Entry-Level (<USD 600)
9.3.2. Mid-Range (USD 600–1,200)
9.3.3. Premium (>USD 1,200)
9.4. Market Analysis, Insights and Forecast - by Processor Architecture
9.4.1. x86 (Intel-AMD)
9.4.2. ARM-Based
9.4.3. RISC-V & Other
9.5. Market Analysis, Insights and Forecast - by Distribution Channel
9.5.1. Online
9.5.2. Offline
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Form Factor
10.1.1. Laptops/Notebooks
10.1.2. Desktop Towers & SFF
10.1.3. Tablets
10.1.4. Hybrid/2-in-1 Devices
10.2. Market Analysis, Insights and Forecast - by End-User
10.2.1. Consumers
10.2.2. Small & Medium Enterprise
10.2.3. Large Enterprise
10.2.4. Government & Education
10.3. Market Analysis, Insights and Forecast - by Price Band
10.3.1. Entry-Level (<USD 600)
10.3.2. Mid-Range (USD 600–1,200)
10.3.3. Premium (>USD 1,200)
10.4. Market Analysis, Insights and Forecast - by Processor Architecture
10.4.1. x86 (Intel-AMD)
10.4.2. ARM-Based
10.4.3. RISC-V & Other
10.5. Market Analysis, Insights and Forecast - by Distribution Channel
10.5.1. Online
10.5.2. Offline
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Lenovo
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. HP
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Dell
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Apple
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Asus
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Acer
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Personal Computers Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Personal Computers Market Volume Breakdown (Million Units, %) by Region 2026 & 2034
Figure 3: North America Personal Computers Market Revenue (Billion), by Form Factor 2026 & 2034
Figure 4: North America Personal Computers Market Volume (Million Units), by Form Factor 2026 & 2034
Figure 5: North America Personal Computers Market Revenue Share (%), by Form Factor 2026 & 2034
Figure 6: North America Personal Computers Market Volume Share (%), by Form Factor 2026 & 2034
Figure 7: North America Personal Computers Market Revenue (Billion), by End-User 2026 & 2034
Figure 8: North America Personal Computers Market Volume (Million Units), by End-User 2026 & 2034
Figure 9: North America Personal Computers Market Revenue Share (%), by End-User 2026 & 2034
Figure 10: North America Personal Computers Market Volume Share (%), by End-User 2026 & 2034
Figure 11: North America Personal Computers Market Revenue (Billion), by Price Band 2026 & 2034
Figure 12: North America Personal Computers Market Volume (Million Units), by Price Band 2026 & 2034
Figure 13: North America Personal Computers Market Revenue Share (%), by Price Band 2026 & 2034
Figure 14: North America Personal Computers Market Volume Share (%), by Price Band 2026 & 2034
Figure 15: North America Personal Computers Market Revenue (Billion), by Processor Architecture 2026 & 2034
Figure 16: North America Personal Computers Market Volume (Million Units), by Processor Architecture 2026 & 2034
List of Tables
Table 1: Personal Computers Market Revenue Billion Forecast, by Form Factor 2020 & 2034
Table 2: Personal Computers Market Volume Million Units Forecast, by Form Factor 2020 & 2034
Table 3: Personal Computers Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 4: Personal Computers Market Volume Million Units Forecast, by End-User 2020 & 2034
Table 5: Personal Computers Market Revenue Billion Forecast, by Price Band 2020 & 2034
Table 6: Personal Computers Market Volume Million Units Forecast, by Price Band 2020 & 2034
Table 7: Personal Computers Market Revenue Billion Forecast, by Processor Architecture 2020 & 2034
Table 8: Personal Computers Market Volume Million Units Forecast, by Processor Architecture 2020 & 2034
Table 9: Personal Computers Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 10: Personal Computers Market Volume Million Units Forecast, by Distribution Channel 2020 & 2034
Table 11: Personal Computers Market Revenue Billion Forecast, by Region 2020 & 2034
Table 12: Personal Computers Market Volume Million Units Forecast, by Region 2020 & 2034
Table 13: North America Personal Computers Market Revenue Billion Forecast, by Form Factor 2020 & 2034
Table 14: North America Personal Computers Market Volume Million Units Forecast, by Form Factor 2020 & 2034
Table 15: North America Personal Computers Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 16: North America Personal Computers Market Volume Million Units Forecast, by End-User 2020 & 2034
Frequently Asked Questions
1. How big is the personal computers market in 2026?
The global personal computers market is valued at approximately USD 242.63 billion in 2026 and is forecast to reach USD 372.68 billion by 2031, expanding at a compound annual growth rate of 8.98%.
2. Which region leads the personal computers market?
Asia-Pacific leads with 36.71% revenue share in 2025, driven by manufacturing concentration and rising domestic demand. Africa is the fastest-growing region at 10.58% CAGR through 2031.
3. Who are the top personal computer vendors?
Lenovo leads global unit shipments at 25.5% (2024), followed by HP at 21.6%, Dell at 16.1%, Apple at 9.2%, Asus at 7.1%, and Acer at 6.9%, according to vendor shipment data.
4. What is driving growth in the personal computers market?
On-device AI acceleration (+2.3% CAGR impact), hybrid-work notebook refresh (+2.1%), and the Windows 10 end-of-life deadline (+1.9%) are the three strongest growth drivers through 2031.
5. What is the fastest-growing PC form factor?
AI-optimized laptops are growing fastest at 11.66% CAGR through 2031, followed by hybrid/2-in-1 devices at 9.0%, as buyers prioritize portability and on-device AI capability.
6. What risks could slow the personal computers market?
Component supply-chain volatility (-1.6% CAGR impact) and smartphone substitution for casual tasks (-1.2%) are the primary restraints, alongside geopolitical disruptions concentrated in Asia-Pacific manufacturing.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis rests on a 70/30 split between primary and secondary research. We conducted structured interviews with stakeholders across the PC value chain: semiconductor and component suppliers, OEM/ODM assembly partners, specialist peripheral formulators, global distributors, and enterprise IT procurement teams. Decision-makers interviewed included VP-level Sourcing Leads, Heads of Hardware R&D, Technical Directors for thermal and power design, and Commercial Operations Leads at tier-1 vendors. Interview programs were fielded across North America, Europe, and Asia-Pacific to capture regional demand asymmetries.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP Sourcing & Procurement Leads
35%
Heads of Hardware R&D
30%
Technical Directors (Thermal/Power)
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Semiconductor & Component Suppliers
35%
OEM/ODM Assembly Partners
30%
Global Distributors & Retailers
20%
Enterprise IT Procurement Teams
15%
Secondary Benchmarking & Public Trade Validation
We triangulated primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate filings including 10-K reports and investor presentations from listed OEMs, patent databases tracking NPU and thermal-management innovation, and recognized industry standards bodies including IEEE and ISO/IEC technical committees for computing form factors and energy efficiency.
Demand Modeling & Market Sizing Triangulation
Market sizing combines a top-down allocation from macroeconomic IT-spending forecasts with a bottom-up model built on manufacturer capacity, product pricing by tier, and end-use consumption data. Both tracks are reconciled at the regional and form-factor level to produce a single validated base-year value and forecast path.
 Personal Computers Market