 Architectural Membranes Market
: Size, Share & 2033 Forecast
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 214

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Architectural Membranes Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 2.700 B |
| 2025 | 2.900 B |
| 2026 | 3.000 B |
| 2027 | 3.200 B |
| 2028 | 3.400 B |
| 2029 | 3.600 B |
| 2030 | 3.800 B |

Architectural membranes are high-performance coated fabrics and films — including PTFE-coated fiberglass, PVC-coated polyester, and ETFE foil — engineered for tensioned roofing, façade, and shading systems. They enable long-span, lightweight structures with translucency, weather resistance, and design flexibility, serving stadiums, airports, transit hubs, and commercial complexes.
This analysis covers global demand for architectural membranes across material types (PTFE, PVC, ETFE, silicone-coated fabrics, and others) and end uses (sports & recreation, transportation infrastructure, commercial & retail, and others) from 2024 to 2033. This analysis does not cover conventional roofing membranes (TPO, EPDM, bituminous), greenhouse films, or geotextiles.
Estimates diverge sharply by scope definition, from roughly USD 2.5 Billion to over USD 22 Billion for the base year, reflecting fundamental differences in what is counted as an "architectural membrane."
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 2.46 Billion | 2024 | 2035 | 6.68% | Coated fabrics, ETFE film, silicone fabrics | One published industry estimate |
| USD 2.9 Billion | 2025 | 2033 | 6.2% | Architectural tensioned & coated fabric systems | A competing analysis |
| USD 22.16 Billion | 2024 | 2034 | 6.5% | Broad envelope incl. conventional roofing membranes | Another published estimate |
Our analysis favors the USD 2.9–3.0 Billion band as the most defensible figure, because it isolates engineered tensile and coated structural systems rather than blending in commodity roofing. The USD 22 Billion figure conflates a commodity waterproofing category and should be treated as an upper-bound adjacency, not a comparable peer. For buyers, the narrower definition is the one aligned with premium, design-led specification cycles.
Segmentation follows two axes — material technology and end-use application — with material choice largely dictated by span, translucency, and lifecycle cost requirements.
| Parent Segment | Children |
|---|---|
| By Material Type | PTFE Coated Fabric, PVC Coated Fabric, ETFE Film, Silicone Coated Fabric, Others |
| By End Use | Sports & Recreation, Transportation Infrastructure, Commercial & Retail, Others (Cultural, Residential, Temporary) |
| By Coating Technology | Coated Fabrics, Uncoated Films, Laminated Composites |
PTFE commands the largest single share (~35%) on durability and self-cleaning performance, while ETFE is the growth outlier. PVC retains cost-sensitive volume but faces increasing scrutiny on lifecycle sustainability, which our analysis suggests will accelerate its displacement in high-profile projects over the forecast window.
Asia Pacific leads with roughly a third of global revenue, anchored by China's infrastructure pipeline, followed by North America and Europe on premium renovation and landmark projects.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.33% |
| North America | 0.25% |
| Europe | 0.22% |
| Middle East & Africa | 0.11% |
| Latin America | 0.1% |
China alone accounted for the largest single-country contribution within Asia Pacific, per published regional data. Our analysis suggests the region's advantage is structural, not cyclical: lower fabricated-steel costs, concentrated membrane production capacity, and state-backed mega-event and transit spending all reinforce share. The counterweight is that Western markets monetize higher per-square-meter value through premium ETFE and solar-integrated systems.
Lightweight, sustainable construction and landmark infrastructure demand are the dominant growth engines; cost and engineering complexity are the binding constraints on faster adoption.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Lightweight & sustainable construction | Driver | Strong | Lower structural load, faster install, reduced HVAC load |
| Iconic architecture & mega-infrastructure | Driver | Strong | Airports, stadiums, transit hubs specify tensile systems |
| Green building certification (LEED, BREEAM) | Driver | Moderate | Recyclability, daylighting, energy performance |
| High initial cost & design complexity | Restraint | Strong | Custom engineering and skilled labor inflate capex |
| Raw material price volatility | Restraint | Moderate | Polymer and coated-fabric cost swings hit project economics |
| Durability/fire-code concerns in extreme climates | Restraint | Moderate | Compliance friction in cost-sensitive regions |
Our analysis suggests the driver set is more durable than the restraint set: costs are amortized over 25–30 year lifespans, while material innovation (self-cleaning coatings, solar-integrated ETFE) steadily erodes the complexity barrier. The critical second-order effect is that as installation expertise broadens, price competition will migrate from materials toward engineering services.
Competition is moderately concentrated, with specialists in coated fabrics and tensile engineering competing alongside diversified chemical and construction-materials groups.
| Vendor | Primary Focus | Differentiation | Moat |
|---|---|---|---|
| Taiyo Kogyo | Tensile structures, engineering | Full-system design & build | Engineering integration |
| Serge Ferrari | PVC/coated fabrics | Brand, architectural reach | Premium specification |
| Mehler Texnologies | Coated fabrics | Broad technical textile range | Industrial scale |
| Sioen Industries | Coated technical textiles | Vertical integration | Cost & capacity |
| Verseidag | PTFE/coated fabrics | High-performance specialties | Technical specialization |
| Saint-Gobain | Sheerfill PTFE/ETFE | Global distribution | Brand & channel |
Differentiation rests on three levers: material performance under extreme climate, engineering support for complex geometries, and certification credentials. Our analysis suggests that vendors with integrated engineering services convert specifications at materially higher rates than fabric-only suppliers, making service depth the primary competitive moat.
Buyers should treat membrane selection as a lifecycle decision, not a first-cost decision. The dominant selection criteria are span capability, UV and fire performance, self-cleaning behavior, and the availability of certified installation partners in-region. Procurement risk is concentrated in two areas: bespoke fabrication lead times and the thin bench of qualified tension-structure installers, both of which can destabilize project schedules. Switching costs are high once structural engineering is locked, so specification-stage diligence matters more than post-award negotiation. Regulatory compliance — fire classification, structural codes, and green certification — should be validated before shortlisting, because retrofitting compliance post-design is costly.
The balance of evidence favors the 6.2–6.7% CAGR consensus and the ~USD 3 Billion base, with Asia Pacific's structural cost advantage sustaining its lead through 2033. The strongest counter-argument is that broader envelope-membrane definitions imply a far larger addressable market; we reject this as a competing frame rather than a competing forecast. What matters is that premium material tiers are growing faster than commodity tiers.
We see a divergence between volume growth (Asia Pacific, cost-led PVC) and value growth (North America and Europe, ETFE and solar-integrated systems). This implies vendors should pursue a barbell strategy rather than a single global positioning. Service integration is the most under-appreciated battleground: material-only suppliers will compress on price as fabrication capacity expands.
Evidence that would change this conclusion: sustained raw-material deflation combined with rapid installer-capacity expansion, which would accelerate commodity PVC adoption beyond our base case.
Our methodology triangulates primary fieldwork with secondary benchmarks across the architectural membrane value chain. Full detail follows.
We apply a 70/30 primary-to-secondary research split. In-depth interviews span raw material and polymer suppliers, specialized membrane producers, contract fabricators, tensile engineering firms, and global distributors. Interviewed decision-makers include VP Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads.
We validate against UN Comtrade and WTO trade statistics, US ITC and Eurostat data, corporate 10-K and SEC filings, patent databases, and recognized technical standards bodies.
We run simultaneous top-down (macroeconomic and segment allocation) and bottom-up (manufacturer capacity, product pricing, end-use consumption) models to reconcile estimates.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.2% from 2020-2034 |
| Segmentation |
|
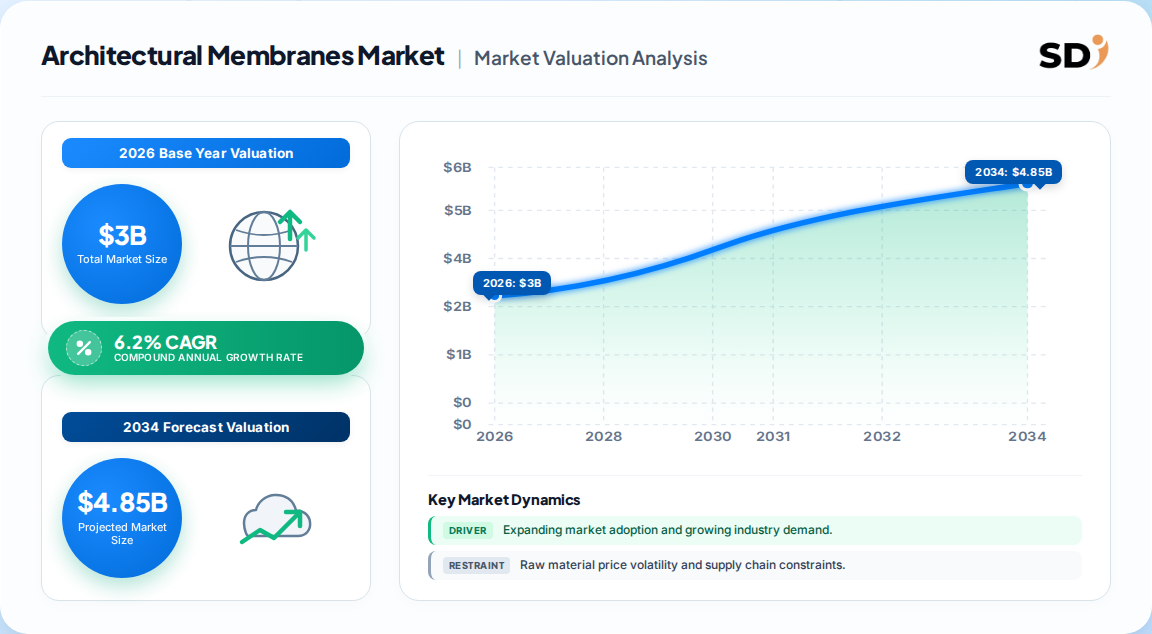
The global architectural membranes market is estimated at USD 3.0 Billion in 2026, on track to reach USD 4.6 Billion by 2033 at a 6.2% CAGR, per the consensus of published estimates.
PTFE coated fabric is the leading material, holding roughly 35% of revenue, favored for its durability, self-cleaning surface, and high tensile strength in large-span structures.
Asia Pacific leads with about 33% of global revenue, driven by China's infrastructure pipeline, followed by North America and Europe on premium landmark projects.
ETFE film is the fastest-growing material segment, supported by its high light transmission, lightweight construction, and solar-integration potential in modern energy-efficient buildings.
High initial costs, complex structural engineering, and a limited pool of skilled installers constrain adoption, particularly in cost-sensitive projects and developing regions with limited technical expertise.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our methodology triangulates primary fieldwork with secondary benchmarks across the architectural membrane value chain. Full detail follows.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial Operations Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Membrane Producers & Fabricators | 40% |
| Raw Material & Polymer Suppliers | 30% |
| Tensile Engineering Firms | 20% |
| Distributors & Traders | 10% |
We apply a 70/30 primary-to-secondary research split. In-depth interviews span raw material and polymer suppliers, specialized membrane producers, contract fabricators, tensile engineering firms, and global distributors. Interviewed decision-makers include VP Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads.
We validate against UN Comtrade and WTO trade statistics, US ITC and Eurostat data, corporate 10-K and SEC filings, patent databases, and recognized technical standards bodies.
We run simultaneous top-down (macroeconomic and segment allocation) and bottom-up (manufacturer capacity, product pricing, end-use consumption) models to reconcile estimates.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |