 Egypt Ride Hailing Service Market
 2025
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 270

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Egypt Ride Hailing Service Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 1.840 B |
| 2025 | 2.050 B |
| 2026 | 2.280 B |
| 2027 | 2.540 B |
| 2028 | 2.830 B |
| 2029 | 3.160 B |
| 2030 | 3.610 B |

You've requested a page on a website (rd.datainsightsmarket.com) that is on the Cloudflare network. An unknown error occurred while rendering the page.
If you are the owner of this website:
refer to Workers - Errors and Exceptions and check Workers Logs for rd.datainsightsmarket.com.
| Region | Market Share (%) |
|---|---|
| Greater Cairo | 0.46% |
| Alexandria | 0.14% |
| Delta & Canal Cities | 0.18% |
| Upper Egypt | 0.12% |
| Red Sea & Sinai Tourism Hubs | 0.1% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 11.4% from 2020-2034 |
| Segmentation |
|
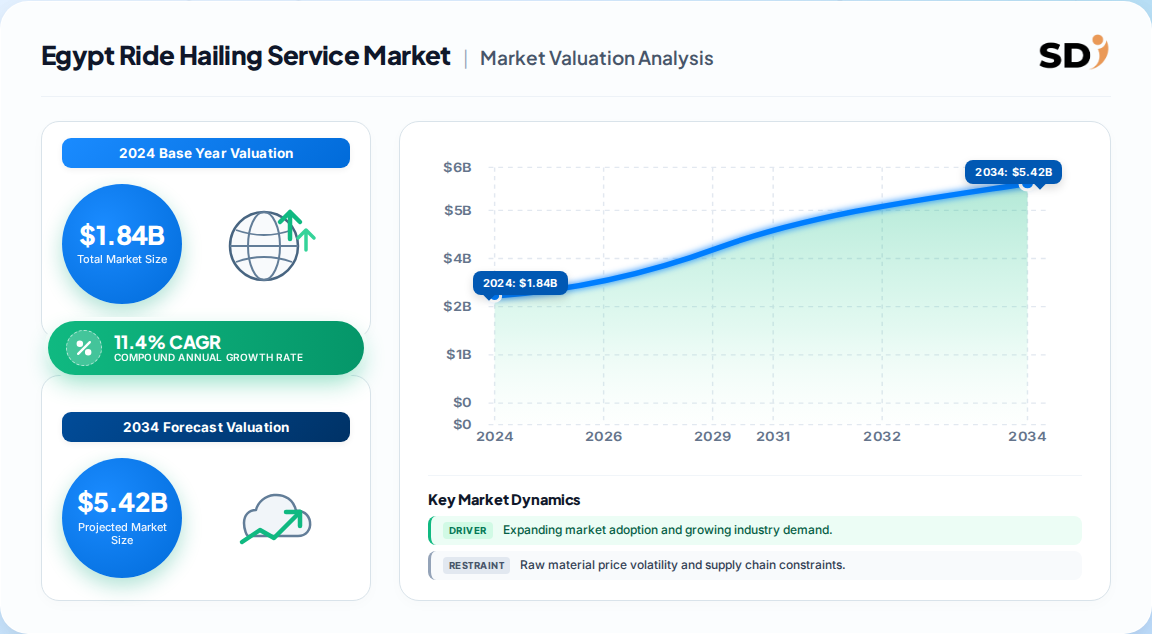
The Egypt ride hailing service market was estimated at USD 1.84 billion in 2024 and is projected to reach USD 3.61 billion by 2030, growing at an 11.4% CAGR from 2025 to 2030.
E-hailing grows fastest at a 14.1% CAGR through 2030, driven by smartphone penetration, real-time tracking and rider preference for app-dispatched trips over street-hailed taxis.
Uber, Careem, inDrive, DiDi, Bolt and Halan lead, with Swvl, FriendyCar, M Car Egypt, Fyonka, Avis and Sixt active in adjacent rental and car-sharing models.
Traffic congestion, urbanisation, low vehicle ownership, rising smartphone penetration and record tourism of 15.7 million visitors in 2024 are the principal demand drivers.
Fuel price and currency pressure compress driver earnings, cash-dominant payments constrain monetisation, and city-by-city licensing and data-protection rules slow expansion.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study follows a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the mobility value chain with platform operators, fleet and vehicle-leasing suppliers, payment service providers, driver-network aggregators and corporate mobility buyers. Interviews targeted decision-makers including Heads of Market Expansion, Commercial Operations Leads, Fleet Partnership Directors and Regulatory Affairs Managers, each contributing city-level supply, pricing and compliance evidence.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Heads of Market Expansion | 35% |
| Commercial Operations Leads | 30% |
| Fleet Partnership Directors | 20% |
| Regulatory Affairs Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Ride-Hailing & Dispatch Platforms | 40% |
| Fleet, Rental & Car-Sharing Operators | 25% |
| Payment & Fintech Providers | 20% |
| Driver Networks & Corporate Mobility Buyers | 15% |
Findings were benchmarked against official statistical sources: national vehicle licensing and registration data, tourism authority arrivals statistics, central bank exchange-rate series, World Bank urbanisation indicators, and platform annual filings and investor disclosures. Technical and standards references include transport licensing frameworks, payment-card industry data security standards and municipal permitting rules applicable to app-dispatched transport.
Sizing was triangulated bottom-up — driver counts per zone, trips per driver-hour, average fare and commission — against a top-down allocation from national consumer mobility spend and smartphone-enabled addressable population. FX-adjusted reconciliation ensures local-currency fare growth is not mistaken for dollar-denominated market expansion.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up trip and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Governorate and metro share | Population density, licensing and trip-flow analysis | High |
| Competitive Landscape | Leading market players | Annual reports, city launches and capacity mapping | High |