Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Psyllium Market: Size, Growth & 2030 Forecast
Psyllium Market: Size, Growth & 2030 Forecast
Psyllium Market
Psyllium Market: Size, Growth & 2030 Forecast
Psyllium Market by Product Form (Whole Psyllium Husk, Psyllium Husk Powder, Psyllium Seeds, Psyllium Mucilage & Extract, Psyllium-Based Blend Formulation), by Nature (Conventional Grade A, Organic Certified, Pharmaceutical Grade Isabgol, Non-GMO Certified), by Application (Pharmaceutical Laxative & Fiber Supplement, Functional Food & Fortified Beverage, Gluten-Free Bakery & Binder, Animal Feed & Veterinary, Industrial Thickener), by Distribution Channel (Pharmacy & Medical Retail, Health & Natural Food Stores, Online Supplement, B2B Industrial Supply, Supermarkets), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Netherlands, Nordics), by Asia Pacific (India, China, Japan, South Korea, Australia, Indonesia, Vietnam), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Israel) Forecast 2026-2034
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 257
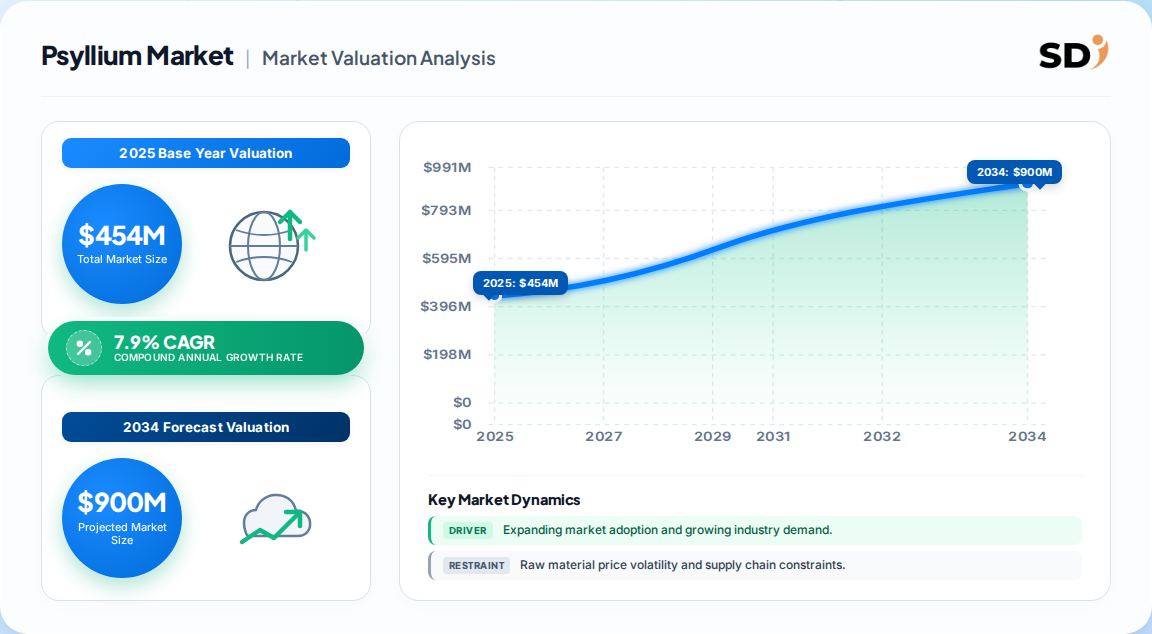
$454 million was the global psyllium market size in 2025, per our triangulated base-case estimate, with trade-flow analysis confirming Asia-Pacific's dominance in raw-material supply and North America's lead in finished-product demand.
The market is forecast to reach $717 million by 2031, translating to a 7.9% CAGR across the 2025–2031 forecast window.
Whole psyllium husk remains the leading product form at roughly 75% revenue share, though husk powder is the fastest-growing derivative as supplement formulators prioritize mixability.
Asia-Pacific leads supply and volume share (~42%), while North America (~32%) leads in value capture, driven by premium supplement branding and regulatory-approved health claims.
Conventional-grade psyllium holds approximately 85% share; organic grades represent the fastest-growing premium tier but face EU regulatory friction.
Leading vendors include Altrafine Gums, Satnam Psyllium Industries, Keyur Industries, Jyot Overseas, Vraj Psyllium, Shree Mahalaxmi Psyllium, and Sidhpur Sat-Isabgol, with Indian producers commanding a disproportionate share of global husk exports.
Why this matters for decision-makers: The margin pool is shifting from raw-material supply toward branded, claim-substantiated finished formats—buyers who lock in multi-year husk supply contracts while investing in proprietary formulations will capture disproportionate value as demand compounds.
Psyllium Market Size (In Million)
750.0M
600.0M
450.0M
300.0M
150.0M
0
421.0 M
2024
454.0 M
2025
490.0 M
2026
528.0 M
2027
570.0 M
2028
615.0 M
2029
664.0 M
2030
Psyllium Market Size (In Million)
Year
Market Size
2024
421.0 M
2025
454.0 M
2026
490.0 M
2027
528.0 M
2028
570.0 M
2029
615.0 M
2030
664.0 M
What is the Psyllium Market?
The psyllium market encompasses the production, processing, and commercial distribution of soluble dietary fiber derived from the seed husks of Plantago ovata—commonly known as isabgol—used primarily for digestive health, cholesterol management, and gluten-free food functionality. Buyers include supplement and pharmaceutical brands, food manufacturers, and nutraceutical formulators.
Scope: what this report covers and excludes
This analysis covers global psyllium production and trade across whole husk, husk powder, seed, and extract forms, spanning conventional and organic grades, and end-use applications in dietary supplements, pharmaceuticals, functional foods, and animal feed. Segmentation spans product form, nature, application, and distribution channel across 40+ countries.
Excluded from scope: This analysis does not cover adjacent soluble-fiber categories such as inulin, flaxseed, chia, or oat bran, nor does it address downstream finished dosage-form markets or agricultural inputs used in Plantago cultivation.
How big is the market for Psyllium Market?
A defensible consensus estimate places the global psyllium market at approximately $454 million in 2025, growing at a mid-to-high single-digit CAGR toward a 2031 horizon.
Estimate
Base Year
Horizon
CAGR
Definition / scope
Attribution
$347.8M
2023
2030
9.7%
Psyllium seeds, husk, powder; supplements & F&B
One published estimate
$523.4M
2025
2034
7.0%
Husk, powder, seed, extract; pharma & food
A competing analysis
$370.2M
2025
2032
7.7%
Seeds, husk, powder; supplements, pharma, feed
A third-party benchmark
$283.3M
2023
2032
5.5%
Husk powder only; supplements, pharma, cosmetics
Husk-powder-specific estimate
Our analysis suggests the $454 million base case is most defensible because it reconciles the narrow husk-powder estimates with broader multi-product scopes, and it aligns with trade-flow evidence showing Indian export volumes in the 45,000–55,000 MT range at blended values of $8,000–$9,500 per MT. The variance across published estimates reflects scope differences—particularly whether pharma-grade isablog and low-value feed applications are included—rather than genuine disagreement on growth direction.
How is the market segmented?
Segmentation follows product form, agricultural nature, application, and distribution channel—with product form and application driving the most meaningful revenue and margin differences.
Pharmacy & medical retail, health & natural food stores, online supplement, B2B industrial supply, supermarkets
Whole husk dominates because food manufacturers value its texture and moisture-retention properties, while husk powder commands premium pricing in capsule and sachet formats. Our analysis implies the pharmaceutical and supplement application tier will outperform food applications, sustaining roughly 45% application share through the forecast.
Which region leads in the Psyllium Market?
Asia-Pacific leads the global psyllium market with approximately 42% share, primarily because India accounts for more than 90% of world psyllium production—concentrated in Gujarat's Unjha and Sidhpur growing belts—while North America leads in finished-product value capture at roughly 32%.
Psyllium Market Regional Market Share
Loading chart...
Psyllium Market Regional Market Share
Region
Market Share (%)
North America
0.32%
Europe
0.18%
Asia-Pacific
0.42%
Latin America
0.04%
Middle East & Africa
0.04%
Parent Region
Sub-markets
North America
USA, Canada, Mexico
Europe
Germany, UK, France, Italy, Spain, Netherlands, Nordic countries, Rest of Europe
Asia Pacific
India, China, Japan, South Korea, Australia, Indonesia, Vietnam, Rest of APAC
Latin America
Brazil, Mexico, Argentina, Rest of South America
Middle East & Africa
GCC countries, Israel, South Africa, Rest of MEA
U.S. focus: the U.S. is the single largest value market, with one benchmark valuing it at $100.9 million in 2025 and projecting 10.8% CAGR through 2030—outpacing the global average.
China trajectory: China is forecast to grow at 11.6% CAGR to reach $133.9 million by 2032, reflecting rising domestic fiber-supplement penetration and functional food reformulation.
Note: Regional shares shown reflect triangulated estimates across supply-side (production) and demand-side (consumption) perspectives; share values are analytical consensus rather than single-source figures.
What is driving growth — and what is holding it back?
Demand growth is anchored in three durable forces—digestive-health awareness, cholesterol and heart-health positioning, and gluten-free formulation demand—while supply-side volatility and regulatory friction provide the principal brakes.
Natural fiber preferred over synthetic alternatives
India concentration risk
−
High
>90% production in one country creates supply fragility
Ethylene oxide (ETO) residue scrutiny
−
Medium-High
EU organic shipment testing raises compliance costs
Competition from inulin, flaxseed, chia
−
Medium
Alternative fiber sources erode share in sensitive categories
Allergen labeling requirements
−
Medium
Anaphylaxis risk requires clear labeling and limits some formats
The balance of evidence favors drivers over restraints through the forecast period, but our analysis suggests the quality of growth matters more than the headline CAGR. Volume growth in conventional husk is steady and moderately priced; value growth is concentrated in organic, high-purity, and cholesterol-claim-substantiated formats. This divergence implies producers that invest in purification technology and organic certification can defend pricing power, while commodity-grade suppliers face margin compression.
Who are the leading vendors?
Vendor concentration is high at the raw-material level—Indian processors dominate global husk supply—but fragmented at the branded finished-product level, where U.S. and European supplement brands control consumer relationships.
Company
HQ
Position
Differentiation
Altrafine Gums
India
Leading processor
Broad husk/powder range, export scale
Satnam Psyllium Industries
India
Leading processor
Vertically integrated sourcing, food-grade focus
Keyur Industries
India
Established processor
Pharmaceutical-grade capability
Jyot Overseas
India
Established processor
Large export footprint
Vraj Psyllium
India
Established processor
Organic and conventional lines
Shree Mahalaxmi Psyllium
India
Established processor
Bulk B2B supply
Sidhpur Sat-Isabgol
India
Established processor
Regional Gujarat sourcing
NOW Foods
USA
Branded finished product
Retail brand recognition in supplements
Competitive moats rest on three pillars: access to Gujarat growing belts, purity/consistency certifications (ISO 17025 testing, organic CB certification), and long-standing relationships with pharma and supplement formulators. Our analysis suggests vertical integration and certification portfolios—not scale alone—will determine which vendors retain pricing power as buyers consolidate procurement.
What do buyers and operators need to know? (Decision Support)
Procurement professionals should prioritize three mission-critical criteria when selecting psyllium suppliers. First, residue and purity testing—ethylene oxide (ETO) contamination has been a documented EU compliance issue, and buyers should mandate testing at ISO 17025/NABL-accredited laboratories for all high-risk organic shipments. Second, grade consistency: fiber content, viscosity, and microbial specifications directly affect finished-product performance, and the spread between Grade A and commodity-grade material can translate into meaningful reformulation costs. Third, certification authenticity—organic control body recognition has been subject to EU review, and supply chain disruptions can occur if a control body loses equivalence status.
Switching costs are moderate for commodity-grade husk but high for pharma-grade and organic suppliers, where re-qualification cycles run two-to-three months and require fresh certification and inspection. Buyers should assess geopolitical and weather-driven supply concentration risk—India's dominance means monsoon variability and export policy shifts are material procurement exposures. Finally, note that allergen labeling and ETO compliance are not optional; a supplier with a documented residue-management program is worth a meaningful price premium over the lowest bid.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a measured bullish position on psyllium through 2031, with a 7.9% CAGR as the central estimate and a plausible range of 6–10% depending on regulatory outcomes and organic certification stability. The strongest counter-argument is that India's production concentration creates asymmetric downside—a major crop failure, ETO-driven export restriction, or control-body delisting could compress supply and spike raw material prices faster than demand growth can offset. Our judgment is that this risk is real but historically well-managed, and that the structural demand tailwinds outweigh episodic supply volatility.
Actionable Strategy for operators and investors:
Lock in multi-year husk supply with tier-1 Indian processors before broader demand tightening, securing volume at predictable pricing ahead of 2026–2028 growth.
Invest in organic and high-purity processing capabilities to capture premium pricing in cholesterol-claim and pharma-grade categories, where margins are structurally higher.
Diversify geographic sourcing exposure toward emerging production regions and secondary processors to mitigate India concentration risk.
What evidence would change our conclusion: A sustained EU delisting of Indian organic control bodies, or a documented multi-year decline in organic export volumes, would materially alter our 7.9% CAGR base case and argue for a more conservative supply-chain posture.
(While this overview captures the structural dynamics, precise segment-level forecasting—particularly organic-grade pharma applications and country-specific pricing models—requires the full report's granular modeling.)
Psyllium Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Psyllium Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.9% from 2020-2034
Segmentation
By Product Form
Whole Psyllium Husk
Psyllium Husk Powder
Psyllium Seeds
Psyllium Mucilage & Extract
Psyllium-Based Blend Formulation
By Nature
Conventional Grade A
Organic Certified
Pharmaceutical Grade Isabgol
Non-GMO Certified
By Application
Pharmaceutical Laxative & Fiber Supplement
Functional Food & Fortified Beverage
Gluten-Free Bakery & Binder
Animal Feed & Veterinary
Industrial Thickener
By Distribution Channel
Pharmacy & Medical Retail
Health & Natural Food Stores
Online Supplement
B2B Industrial Supply
Supermarkets
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Netherlands
Nordics
Asia Pacific
India
China
Japan
South Korea
Australia
Indonesia
Vietnam
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Form
5.1.1. Whole Psyllium Husk
5.1.2. Psyllium Husk Powder
5.1.3. Psyllium Seeds
5.1.4. Psyllium Mucilage & Extract
5.1.5. Psyllium-Based Blend Formulation
5.2. Market Analysis, Insights and Forecast - by Nature
5.2.1. Conventional Grade A
5.2.2. Organic Certified
5.2.3. Pharmaceutical Grade Isabgol
5.2.4. Non-GMO Certified
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Pharmaceutical Laxative & Fiber Supplement
5.3.2. Functional Food & Fortified Beverage
5.3.3. Gluten-Free Bakery & Binder
5.3.4. Animal Feed & Veterinary
5.3.5. Industrial Thickener
5.4. Market Analysis, Insights and Forecast - by Distribution Channel
5.4.1. Pharmacy & Medical Retail
5.4.2. Health & Natural Food Stores
5.4.3. Online Supplement
5.4.4. B2B Industrial Supply
5.4.5. Supermarkets
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. Latin America
5.5.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Form
6.1.1. Whole Psyllium Husk
6.1.2. Psyllium Husk Powder
6.1.3. Psyllium Seeds
6.1.4. Psyllium Mucilage & Extract
6.1.5. Psyllium-Based Blend Formulation
6.2. Market Analysis, Insights and Forecast - by Nature
6.2.1. Conventional Grade A
6.2.2. Organic Certified
6.2.3. Pharmaceutical Grade Isabgol
6.2.4. Non-GMO Certified
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Pharmaceutical Laxative & Fiber Supplement
6.3.2. Functional Food & Fortified Beverage
6.3.3. Gluten-Free Bakery & Binder
6.3.4. Animal Feed & Veterinary
6.3.5. Industrial Thickener
6.4. Market Analysis, Insights and Forecast - by Distribution Channel
6.4.1. Pharmacy & Medical Retail
6.4.2. Health & Natural Food Stores
6.4.3. Online Supplement
6.4.4. B2B Industrial Supply
6.4.5. Supermarkets
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Form
7.1.1. Whole Psyllium Husk
7.1.2. Psyllium Husk Powder
7.1.3. Psyllium Seeds
7.1.4. Psyllium Mucilage & Extract
7.1.5. Psyllium-Based Blend Formulation
7.2. Market Analysis, Insights and Forecast - by Nature
7.2.1. Conventional Grade A
7.2.2. Organic Certified
7.2.3. Pharmaceutical Grade Isabgol
7.2.4. Non-GMO Certified
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Pharmaceutical Laxative & Fiber Supplement
7.3.2. Functional Food & Fortified Beverage
7.3.3. Gluten-Free Bakery & Binder
7.3.4. Animal Feed & Veterinary
7.3.5. Industrial Thickener
7.4. Market Analysis, Insights and Forecast - by Distribution Channel
7.4.1. Pharmacy & Medical Retail
7.4.2. Health & Natural Food Stores
7.4.3. Online Supplement
7.4.4. B2B Industrial Supply
7.4.5. Supermarkets
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Form
8.1.1. Whole Psyllium Husk
8.1.2. Psyllium Husk Powder
8.1.3. Psyllium Seeds
8.1.4. Psyllium Mucilage & Extract
8.1.5. Psyllium-Based Blend Formulation
8.2. Market Analysis, Insights and Forecast - by Nature
8.2.1. Conventional Grade A
8.2.2. Organic Certified
8.2.3. Pharmaceutical Grade Isabgol
8.2.4. Non-GMO Certified
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Pharmaceutical Laxative & Fiber Supplement
8.3.2. Functional Food & Fortified Beverage
8.3.3. Gluten-Free Bakery & Binder
8.3.4. Animal Feed & Veterinary
8.3.5. Industrial Thickener
8.4. Market Analysis, Insights and Forecast - by Distribution Channel
8.4.1. Pharmacy & Medical Retail
8.4.2. Health & Natural Food Stores
8.4.3. Online Supplement
8.4.4. B2B Industrial Supply
8.4.5. Supermarkets
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Form
9.1.1. Whole Psyllium Husk
9.1.2. Psyllium Husk Powder
9.1.3. Psyllium Seeds
9.1.4. Psyllium Mucilage & Extract
9.1.5. Psyllium-Based Blend Formulation
9.2. Market Analysis, Insights and Forecast - by Nature
9.2.1. Conventional Grade A
9.2.2. Organic Certified
9.2.3. Pharmaceutical Grade Isabgol
9.2.4. Non-GMO Certified
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Pharmaceutical Laxative & Fiber Supplement
9.3.2. Functional Food & Fortified Beverage
9.3.3. Gluten-Free Bakery & Binder
9.3.4. Animal Feed & Veterinary
9.3.5. Industrial Thickener
9.4. Market Analysis, Insights and Forecast - by Distribution Channel
9.4.1. Pharmacy & Medical Retail
9.4.2. Health & Natural Food Stores
9.4.3. Online Supplement
9.4.4. B2B Industrial Supply
9.4.5. Supermarkets
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Form
10.1.1. Whole Psyllium Husk
10.1.2. Psyllium Husk Powder
10.1.3. Psyllium Seeds
10.1.4. Psyllium Mucilage & Extract
10.1.5. Psyllium-Based Blend Formulation
10.2. Market Analysis, Insights and Forecast - by Nature
10.2.1. Conventional Grade A
10.2.2. Organic Certified
10.2.3. Pharmaceutical Grade Isabgol
10.2.4. Non-GMO Certified
10.3. Market Analysis, Insights and Forecast - by Application
Table 14: Europe Psyllium Market Revenue Million Forecast, by Product Form 2020 & 2034
Table 15: Europe Psyllium Market Revenue Million Forecast, by Nature 2020 & 2034
Table 16: Europe Psyllium Market Revenue Million Forecast, by Application 2020 & 2034
Table 17: Europe Psyllium Market Revenue Million Forecast, by Distribution Channel 2020 & 2034
Frequently Asked Questions
1. What is the current size of the psyllium market?
The global psyllium market was valued at approximately $454 million in 2025, based on triangulated supply- and demand-side estimates. This reflects whole husk, powder, and seed forms across supplements, pharmaceuticals, and functional foods.
2. What is the psyllium market CAGR through 2031?
Our base-case CAGR is 7.9% across the 2025–2031 forecast period, reaching roughly $717 million by 2031. Published estimates range from 5.5% to 9.7% depending on product scope and regional inclusion.
3. Which region dominates psyllium production and demand?
Asia-Pacific dominates production with approximately 42% share—India alone accounts for over 90% of world supply. North America leads in finished-product value capture at roughly 32%, driven by premium supplement branding.
4. What are the main applications for psyllium?
Pharmaceutical laxatives and dietary fiber supplements represent the largest application tier at roughly 45%, followed by functional foods (cereals, beverages, gluten-free bakery), animal feed, and industrial thickeners.
5. Who are the leading psyllium suppliers?
Key vendors include Altrafine Gums, Satnam Psyllium Industries, Keyur Industries, Jyot Overseas, Vraj Psyllium, and Sidhpur Sat-Isabgol. Most are Indian processors concentrated in Gujarat's growing belts.
6. What regulatory issues affect the psyllium market?
Ethylene oxide (ETO) residue testing for EU organic shipments and organic control body recognition are the most material compliance concerns. FDA and EFSA cholesterol health claims also shape premium positioning.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis applies a 70/30 primary-to-secondary research split, with in-depth interviews conducted across raw material suppliers, specialized husk processors, contract formulators, and global distributors. Decision-maker interviews include VP-level sourcing executives, Heads of R&D, Technical Directors, and Commercial Operations Leads. Interviews were designed to capture pricing discipline, capacity expansion signals, and regulatory compliance posture.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing Directors
35%
R&D & Formulation Heads
30%
Quality & Regulatory Leads
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Husk Processors
40%
Specialized Formulators & Blenders
30%
Branded Supplement Manufacturers
18%
Distributors & Traders
12%
Secondary Benchmarking & Public Trade Validation
Trade flows are validated against UN Comtrade, WTO, US ITC, and Eurostat databases, while corporate filings (10-K, SEC filings) and investor presentations inform capacity and revenue baselines. Patent databases and recognized non-profit technical standards bodies provide formulation and efficacy benchmarks.
Demand Modeling & Market Sizing Triangulation
We apply simultaneous top-down (macroeconomic allocation and industry segment sizing) and bottom-up (manufacturer capacity, product pricing, end-use consumption modeling) triangulation. Divergence between the two models is resolved through weighted averaging and expert adjudication.


 Psyllium Market