 Europe Cis Middle East North Africa Sorbitol Market
Europe CIS Middle East North Africa Sorbitol Market 2026
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 198

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Europe Cis Middle East North Africa Sorbitol Market
Srinwanti Kar
Senior Research Analyst

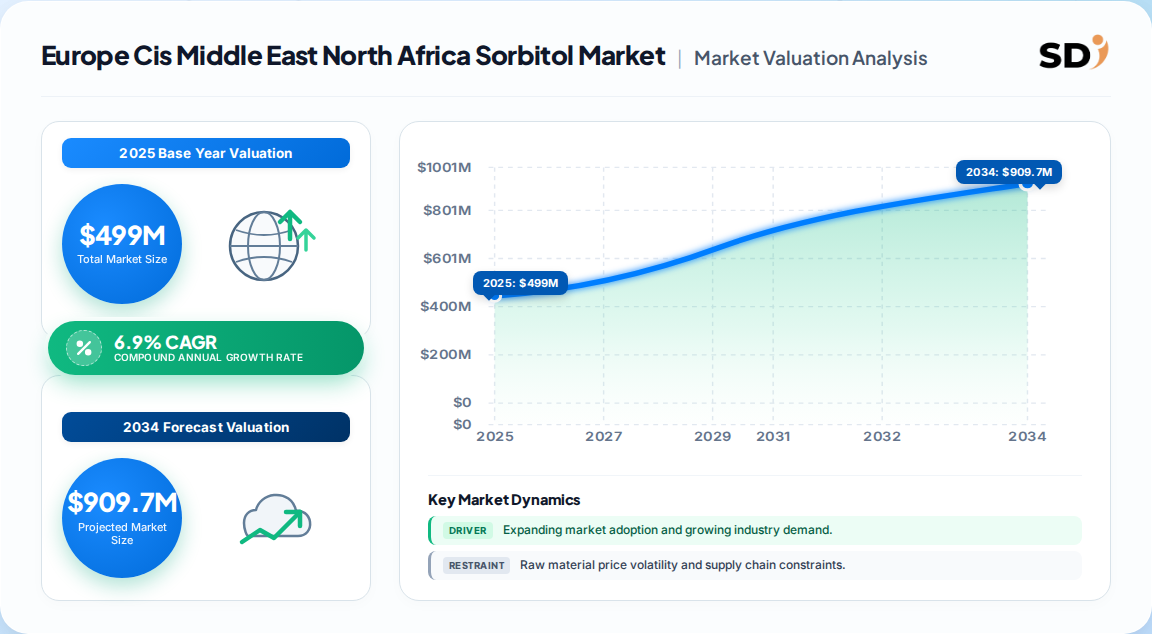
| Year | Market Size |
|---|---|
| 2025 | 499.0 M |
| 2026 | 533.0 M |
| 2027 | 570.0 M |
| 2028 | 609.0 M |
| 2029 | 651.0 M |
| 2030 | 697.0 M |

This is the market for sorbitol, a sugar alcohol derived from corn, wheat and rye starch, sold across Europe, the Commonwealth of Independent States and the Middle East and North Africa. It is used as a low-calorie sweetener, humectant, bulking agent and stabilizer in food, pharmaceuticals, oral care and cosmetics.
This analysis covers sorbitol in crystallized, liquid and powder form, spanning organic and inorganic categories, across food and beverage, animal feed, pharmaceuticals, oral care, cosmetics and industrial applications in Europe, CIS and MENA. Both synthetic (hydrogenated glucose) and starch-derived routes are in scope. This analysis does not cover xylitol, mannitol, erythritol, maltitol or stevia, nor does it cover downstream isosorbide and ethylene glycol derivatives as separate markets.
The 2025 baseline sits at 499 Million with a 6.9% CAGR to 2030, reaching 697 Million. However, published estimates diverge sharply, reflecting base-year and scope differences; buyers should reconcile definitions before contracting.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 434.9 Million | 2019 | 2027 | 3.4% | Europe, CIS and MENA, product and end-use segmentation | One published estimate |
| 94.33 Million | 2025 | 2033 | 4.80% | MENA only, category and form segmentation | A competing analysis |
| 499 Million | 2025 | 2030 | 6.9% | Europe, CIS and MENA, integrated scope | A competing analysis |
| 2.45 Billion | 2034 | 2034 | 4.72% | Global pharmaceutical-grade sorbitol only | A competing analysis |
The 499 Million figure is the most defensible for this geography because it harmonizes Europe's mature base with MENA's faster growth and uses a consistent post-2023 base year. The 3.4% legacy CAGR understates MENA acceleration and reflects pre-pandemic demand structure. Our analysis suggests that the 6.9% path is plausible only if European clean-label reformulation and MENA sugar-tax-driven reformulation both sustain momentum; a 5.5–6.0% outcome is the realistic downside.
Segmentation runs along category, form, source, function and application, with food and beverage applications carrying the largest revenue weight and pharmaceuticals showing the steepest value growth.
| Parent segment | Children |
|---|---|
| By Category | Organic, Inorganic |
| By Form | Crystallized, Liquid, Powder |
| By Source | Corn, Wheat, Rye, Others |
| By Function | Humectant, Sweetener, Bulking Agent, Stabilizer, Softener & Emulsifier, Others |
| By Application | Food & Beverages, Animal Feed, Pharmaceuticals, Oral Care, Cosmetics, Industrial, Others |
The inorganic segment held an estimated 72.4% share in 2025 on cost and availability, while liquid form dominates volume in beverages and oral care. Our analysis suggests organic and crystallized grades will outgrow the aggregate, driven by European clean-label claims and pharmaceutical excipient specifications.
Europe leads on absolute revenue, MENA leads on incremental growth, and the CIS operates as a swing supply and demand block whose trajectory is tied to import substitution and wheat-starch economics.
| Region | Market Share (%) |
|---|---|
| Europe | 0.58% |
| CIS | 0.09% |
| Middle East & North Africa | 0.33% |
Saudi Arabia dominated MENA at roughly 39.6% of regional revenue in 2025, supported by food, pharmaceutical, oral care and cosmetics demand. The UAE is projected to register the fastest country CAGR at approximately 8.5% through 2033, driven by sugar-free confectionery, cosmetics and pharma imports. This divergence implies that volume-led players should anchor in Europe, while value-led and premium-grade players should prioritize Gulf distribution.
Demand-side drivers are structural and regulation-assisted, while restraints are supply-side and substitution-related, producing a net positive but uneven growth path across the three sub-regions.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Diabetes and obesity prevalence | Driver | High | Pushes sugar-free and diabetic-friendly formulation |
| EU additive and humectant approval | Driver | High | Legitimizes sorbitol in food and pharma formulations |
| MENA sugar taxation and reformulation | Driver | Medium | Raises relative cost of sucrose alternatives |
| Clean-label and plant-derived demand | Driver | Medium | Favors starch-based, non-cariogenic grades |
| Substitution by xylitol, mannitol and stevia | Restraint | Medium | Caps share in oral care and nutrition |
| Raw material and seasonal supply volatility | Restraint | High | Drives corn and wheat starch cost swings |
| Regulatory fragmentation in MENA | Restraint | Medium | Slows registration and import clearance |
The balance favors growth, but the restraint set is underestimated. Our analysis suggests substitution risk is concentrated in oral care and nutraceuticals, where xylitol and erythritol have stronger marketing narratives, whereas sorbitol's humectancy and cost position remain defensible in bakery, confectionery and pharmaceutical excipients.
Supply is concentrated among global starch and sweetener majors, with regional players anchoring MENA and CIS price competition and Turkish and Indian producers influencing import parity.
| Company | HQ | Strategic position | Notable capability |
|---|---|---|---|
| Cargill | United States | Broad portfolio, global scale | Cost leadership across liquid and powder grades |
| Roquette Frères | France | Plant-based and pharma-grade focus | Isosorbide integration and POLYSORB platform |
| Ingredion | United States | Sustainable sourcing emphasis | High-purity and tailored functional grades |
| ADM | United States | Integrated agricultural supply chain | Confectionery and pharma excipient supply |
| Tereos | France | Sustainable manufacturing focus | European starch and sweetener integration |
| Sunar Misir | Turkey | Regional cost competitor | MENA and CIS price positioning |
Differentiation rests on grade purity, regulatory documentation and sustainability credentials rather than on price alone. Roquette's forward integration into isosorbide and Cargill's high-purity pharma launch illustrate a shift toward specification-led moats. Our analysis suggests that regional Turkish and Indian producers will pressure commodity liquid grades, while global majors defend value through pharma and clean-label positioning.
Procurement strategy should prioritize specification certainty over headline price. Sorbitol grades differ materially in water content, reducing-sugar limits and microbial specification, and pharma-bound volumes require documented compliance with pharmacopoeial monographs. Buyers should verify supplier certification scope before qualifying a second source.
Switching costs are moderate but asymmetric. Reformulating a beverage or toothpaste away from sorbitol requires stability retesting, sensory revalidation and, in the EU, label reassessment, which can take two to three quarters. This creates leverage for incumbent suppliers but also exposes buyers to single-source risk during corn or wheat starch disruptions.
Regulatory compliance is the sharpest risk. European additive rules are stable, but MENA registration timelines and documentation requirements vary by country, and halal certification is a practical prerequisite in Gulf markets. Operators should build dual-qualified supply across Europe and MENA to absorb tariff and logistics shocks.
The balance of evidence favors a 6.0–6.9% growth path for the covered geography, weighted toward MENA and pharmaceutical-grade volumes, rather than the historical 3.4% trajectory. The strongest counter-argument is substitution: xylitol retains a stronger dental narrative in oral care, and stevia continues to win in beverages, which could cap sorbitol share in the highest-value applications. We nonetheless judge that sorbitol's humectancy, cost position and excipient role insulate it from outright displacement.
Our analysis suggests the market's real constraint is not demand but qualified capacity. Pharma-grade and organic-certified volumes are scarce relative to European and Gulf specification demand, which supports price premiums and favors suppliers with documented sustainability credentials. Buyers who delay qualification of alternate sources will face renewal risk at 2028–2030 contract cycles.
Actionable strategy:
What would change our conclusion: a sustained corn or wheat starch price shock above historical bands, or accelerated EU restriction on polyol labeling, would push growth below 5% and shift the strategic priority from expansion to cost defense.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.9% from 2020-2034 |
| Segmentation |
|
The market was valued at 499 Million in 2025 and is projected to reach 697 Million by 2030 at a 6.9% CAGR. Growth is led by MENA demand and pharmaceutical-grade volumes.
Saudi Arabia dominated MENA with roughly 39.6% of regional revenue in 2025, supported by food, pharmaceutical, oral care and cosmetics industries. The UAE is the fastest-growing country market at about 8.5% CAGR.
Food and beverage, including sugar-free confectionery and diabetic foods, is the largest application, followed by pharmaceuticals, oral care, cosmetics and animal feed. Industrial uses such as de-icing remain niche.
Cargill, Roquette Frères, Ingredion, ADM and Tereos lead globally, while Sunar Misir and Indian producers influence regional pricing. Differentiation rests on grade purity, regulatory documentation and sustainability credentials.
Competition from xylitol, mannitol, erythritol and stevia caps share in oral care and nutrition, while corn and wheat starch supply volatility and fragmented MENA regulation add cost and delay risk for buyers.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with raw material and starch suppliers, specialized sorbitol producers, contract formulators and blenders, and global distributors across Europe, CIS and MENA. Interviewees included VP-level sourcing leads, heads of R&D and formulation, technical directors, and commercial operations managers, ensuring that demand, specification and pricing perspectives were captured simultaneously.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 40% |
| Procurement & Sourcing Directors | 35% |
| Quality & Regulatory Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Starch & Raw Material Producers | 45% |
| Specialized Sorbitol Producers | 35% |
| Distributors & Traders | 20% |
Secondary validation draws on UN Comtrade and WTO trade flows, Eurostat and national customs data, US ITC filings, corporate 10-K and annual investor disclosures, patent databases, and recognized technical standards and industry associations relevant to polyols and food additives. Cross-border trade values were reconciled against reported import volumes to test for under- and over-invoicing.
Sizing combines a top-down allocation from macroeconomic and food, pharma and personal care segment data with a bottom-up model built from manufacturer capacity, grade-level pricing and end-use consumption. The two approaches are reconciled at sub-regional level, with residuals investigated through interview evidence before finalization.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production and revenue triangulation | High |
| Forecast Horizon | 2026–2030 compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Europe, CIS, MENA shares | Cross-border trade flow and consumption analysis | High |
| Competitive Landscape | Leading sorbitol suppliers | Annual reports, capacity mapping and filings | High |