 Stability Test Chambers Market
 2026: Size, CAGR & Outlook
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 249

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Stability Test Chambers Market
Srinwanti Kar
Senior Research Analyst

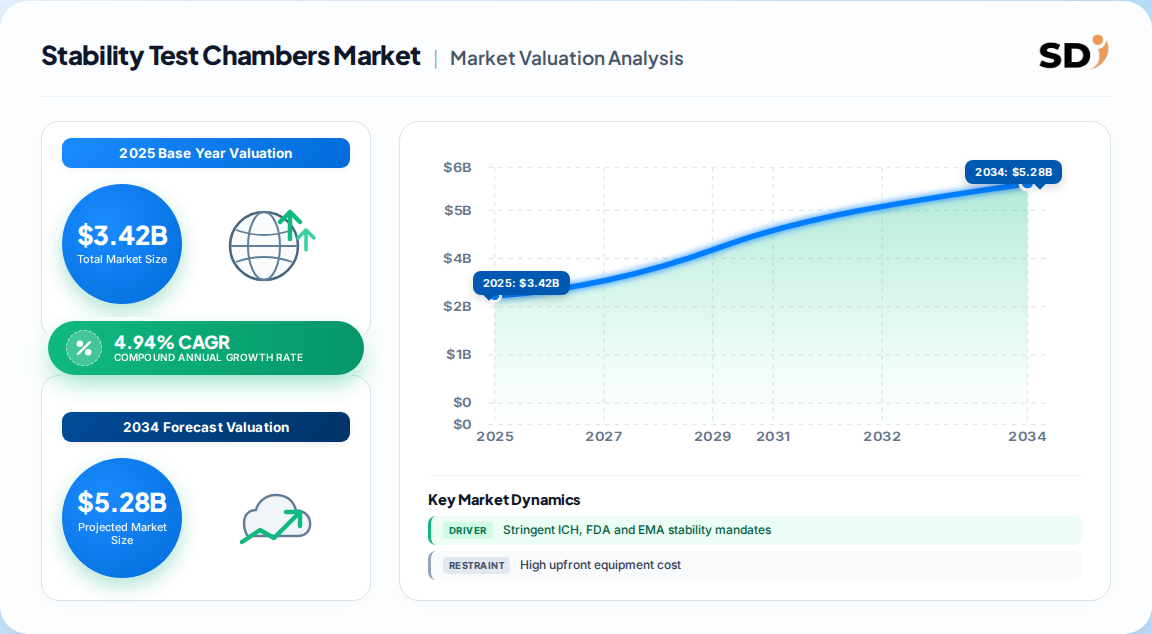
| Year | Market Size |
|---|---|
| 2025 | 3.420 B |
| 2026 | 3.590 B |
| 2027 | 3.770 B |
| 2028 | 3.950 B |
| 2029 | 4.150 B |
| 2030 | 4.350 B |
| 2031 | 4.570 B |

Stability test chambers are controlled environmental systems that replicate precise temperature, humidity and lighting conditions over extended periods to measure how pharmaceutical, food, electronic and cosmetic products degrade. They underpin shelf-life determination, regulatory stability studies and quality assurance, producing the validated data manufacturers need before products reach market.
This report covers global demand for stability and environmental test chambers across product type, chamber size, end-use application and region, spanning the 2020 historical base through a 2035 forecast horizon. It addresses hardware, control software and validation documentation. This analysis does not cover non-environmental materials-testing instruments, cleanroom infrastructure, pharmaceutical manufacturing process equipment, or industrial refrigeration systems, which are treated as adjacent markets.
Published estimates cluster between roughly 2.8 Billion and 3.4 Billion for the 2025 base year, converging on a mid-single-digit growth trajectory through the mid-2030s. The divergence is scope-driven, not demand-driven.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 3.42 Billion | 2025 | 2035 | 4.94% | Broad product and application scope, pharma-led | One published estimate |
| 3.2 Billion | 2025 | 2034 | 4.87% | Product-and-end-user segmentation, environmental chambers largest | A competing analysis |
| 2.81 Billion | 2025 | 2035 | 5.3% | Narrower product set, North America 33% share | A competing analysis |
| 1.1 Billion | 2024 | 2030 | 6.3% | Tight scope, excludes walk-in and altitude systems | A competing analysis |
Our analysis favors the 3.42 Billion base and the 4.94% CAGR as the most defensible midpoint. The lowest 1.1 Billion figure appears to exclude walk-in rooms and larger environmental systems, which our reading of end-user purchasing patterns suggests are a material revenue pool. The 6.3% figure reflects a compressed 2030 horizon where near-term biologics investment inflates the average. A 4.9%–5.3% band is the realistic operating range for planning purposes.
Segmentation follows product type, chamber size and end-use application. Temperature and humidity chambers dominate revenue, while thermal shock units post the fastest growth on electronics and EV battery demand.
| Parent segment | Children | Share / position |
|---|---|---|
| By Product Type | Temperature & Humidity Chambers, Photostability/Light Chambers, Thermal Shock Chambers, Environmental Chambers, Accelerated Stability Chambers, Altitude Chambers | Temperature & humidity ≈ 53% |
| By Chamber Size / Modularity | Benchtop / Reach-In, Walk-In, Portable | Walk-in growing on large-scale pharma |
| By Application / End Use | Pharmaceutical Stability Testing, Biotechnology Testing, Food & Beverage Testing, Cosmetics Testing, Electronics & Semiconductors, Automotive & Aerospace, Academic & CROs | Pharma & biotech ≈ 38% |
Implication: the two structural growth pockets are thermal shock systems pulled by semiconductor and EV supply chains, and walk-in rooms pulled by biologics scale-up. Both reward vendors with engineering customization capability rather than catalog products.
North America holds the largest regional share at roughly 30%, driven by FDA-regulated pharma and a dense CRO/CMO testing ecosystem, while Asia-Pacific is the fastest-growing region on generics, semiconductor and EV investment.
| Region | Market Share (%) |
|---|---|
| North America | 0.3% |
| Europe | 0.24% |
| Asia-Pacific | 0.33% |
| Latin America | 0.07% |
| Middle East & Africa | 0.06% |
| Region | Share |
|---|---|
| North America | 30% |
| Europe | 24% |
| Asia-Pacific | 33% |
| Latin America | 7% |
| Middle East & Africa | 6% |
Our analysis notes a tension in the evidence: one analysis assigns North America 33% of 2035 revenue, while another flags Asia-Pacific as fastest-growing. Both can be true simultaneously, and that combination is the operative insight — North America is a replacement market where connected units displace legacy analog chambers, whereas Asia-Pacific is a greenfield market where capacity is being built. Vendors need two distinct go-to-market motions: compliance-led in the West and capacity-led in the East.
Growth is anchored by regulatory mandates and biologics complexity, while high capital cost and technician scarcity constrain adoption in emerging markets. The driver-restraint balance currently favors expansion.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Stringent ICH/FDA/EMA stability mandates | Up | High | Compliance is non-discretionary; drives replacement and greenfield purchases |
| Biologics and personalized medicine pipelines | Up | High | Temperature-sensitive formulations demand precise, validated chambers |
| IoT, cloud monitoring and predictive maintenance | Up | Medium-High | Reduces downtime and audit risk; premium-mix uplift |
| Thermal shock demand from EVs and semiconductors | Up | Medium-High | Rapid-cycling testing for batteries and chips |
| Energy-efficiency and low-GWP refrigerant regulation | Up | Medium | Replacement cycle accelerator in Europe |
| High upfront capital and energy costs | Down | High | Delays adoption in budget-constrained labs |
| Shortage of trained calibration technicians | Down | Medium | Limits uptime in Tier 2/3 cities |
So what: the restraints are operational rather than demand-side. A vendor that solves calibration and service coverage in secondary cities removes the single largest purchasing objection in emerging pharma hubs, converting a demand constraint into a competitive moat.
ESPEC Corp., Weiss Technik, Binder GmbH, Memmert, Thermo Fisher Scientific, Thermotron, Cincinnati Sub-Zero, Thermal Product Solutions, Angelantoni and CM Envirosystems anchor a moderately consolidated field where Tier 1 players hold over 45% of revenue.
| Vendor | Home base | Core strength | Moat |
|---|---|---|---|
| ESPEC Corp. | Japan | Thermal shock, multi-stress, automotive/electronics | Combined-environment engineering depth |
| Weiss Technik | Germany | Custom and walk-in systems, pharma and aerospace | Full-system integration and service network |
| Binder GmbH | Germany | Energy-efficient precision temperature/humidity | European compliance and efficiency brand |
| Memmert | Germany | Modular, user-centric, academic and research | Scalability and UX |
| Thermo Fisher Scientific | USA | Broad lab portfolio, LIMS cross-sell | Bundling and global service footprint |
| Thermotron | USA | Vibration and environmental integration | Rugged reliability |
| Cincinnati Sub-Zero | USA | Medical device and electronics, connected systems | North American service depth |
Our analysis suggests hardware specification is no longer the decisive differentiator. The competitive edge has migrated to validation documentation (IQ/OQ/PQ), software integration flexibility and same-day global service. One global CRO reportedly selected a vendor on software integration capability alone when replacing 17 legacy chambers across five countries — a procurement signal worth weighting heavily.
Buyers should treat validation documentation as a primary selection criterion, not an afterthought. Chambers without audit-ready IQ/OQ/PQ packages and software aligned to FDA 21 CFR Part 11 or EU Annex 11 create compliance risk that dwarfs the purchase price differential.
Procurement risk concentrates in three areas: calibration and service coverage in secondary geographies, integration with existing LIMS and ERP environments, and energy operating cost over a ten-to-fifteen-year asset life. Switching costs are high because revalidation of a replacement unit can halt studies for weeks — which is precisely why incumbency is sticky and why buyers should negotiate service-level agreements at the point of purchase rather than renewal.
Operators should also model total cost of ownership, not sticker price. Efficiency improvements of the scale reported in European installations, where one food manufacturer cut annual energy costs by roughly 18% after switching to a high-efficiency photostability unit, can justify a premium that looks expensive on a capital line item.
The balance of evidence favors a market in mid-single-digit structural expansion with a premium-segment overlay. Headline growth of roughly 4.9% understates the opportunity, because the mix is shifting toward higher-value connected, validated and energy-efficient systems. Vendors anchored in analog catalog hardware face margin compression even while unit volumes grow.
The strongest counter-argument is that biologics-driven demand is front-loaded and could decelerate if pipeline funding tightens, compressing the 6.3% near-term projections toward the lower end of the range. That is a real risk, but it does not undermine the structural case: regulatory stability testing is non-discretionary spend, and replacement cycles in North America and Europe are independent of pipeline sentiment.
Actionable strategy:
What would change our conclusion: a sustained multi-year decline in global biologics R&D spending, or a regulatory shift that permits reduced long-term stability testing in favor of modeling-based approaches. Neither is visible in current evidence, but both warrant monitoring.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.94% from 2020-2034 |
| Segmentation |
|
Consensus estimates place CAGR between 4.9% and 5.3% for 2026–2035, with a defensible midpoint near 4.94%. Faster published figures typically reflect narrower product scopes or shorter forecast horizons rather than stronger underlying demand.
North America holds the largest installed base at roughly 30% share, led by FDA-regulated pharmaceutical and CRO activity. Asia-Pacific is the fastest-growing region, driven by generics manufacturing, semiconductor fabrication and EV battery testing investment.
EV battery and semiconductor testing require rapid thermal cycling and multi-stress conditions. This pulls higher-specification units and lifts average selling prices, particularly across Asian and North American electronics supply chains.
Buyers should require IQ/OQ/PQ packages aligned to FDA and EU standards, plus software compliant with 21 CFR Part 11 or Annex 11. Missing documentation creates audit risk that far exceeds any purchase price differential between vendors.
Beyond capital cost, buyers should model energy consumption, calibration, maintenance and service coverage over a ten-to-fifteen-year asset life. High-efficiency units can cut annual energy costs by roughly 18%, often justifying a capital premium.
Chambers increasingly ship with IoT sensors, cloud dashboards, predictive maintenance and LIMS/ERP integration. These features are becoming baseline requirements in regulated pharma environments, not optional upgrades.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. The primary program comprised in-depth interviews and structured survey work across the stability test chamber value chain, spanning four company categories: refrigeration and control component suppliers, specialist chamber OEMs, contract calibration and validation service providers, and regional distributors. Interviewees were selected at decision-maker level, including VP of Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads. Fieldwork deliberately over-sampled Asia-Pacific and emerging pharma markets to validate greenfield capacity assumptions.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 35% |
| Procurement & Sourcing Leads | 30% |
| Quality & Regulatory Managers | 25% |
| Commercial Operations Leads | 10% |
| Company Type | Representation (%) |
|---|---|
| Specialist Chamber OEMs | 40% |
| Component & Refrigeration Suppliers | 25% |
| Distributors & Regional Resellers | 20% |
| Calibration & Validation Service Providers | 15% |
Secondary validation draws on official multilateral trade statistics (UN Comtrade, WTO, Eurostat, US ITC), corporate annual filings and investor presentations (10-K and equivalent disclosures), patent activity databases, and recognized technical standards bodies. Regulatory standards referenced include ICH Q1A stability guidelines and FDA/EMA GMP frameworks. No competitor market-research publications are used as validation sources.
We run simultaneous top-down and bottom-up models. The top-down model allocates macroeconomic and industry-segment output to chamber demand. The bottom-up model builds revenue from manufacturer capacity, unit pricing and end-use consumption, then reconciles the two within a tolerance band to produce the reported base-year value and forecast series.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |