 Middle East Bioelectrochemical Systems Wastewater Treatment Market
Middle East BES Wastewater Treatment Market 2025
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 231

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Middle East Bioelectrochemical Systems Wastewater Treatment Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 32.00 M |
| 2025 | 34.00 M |
| 2026 | 36.00 M |
| 2027 | 38.00 M |
| 2028 | 40.00 M |
| 2029 | 42.00 M |
| 2030 | 44.00 M |

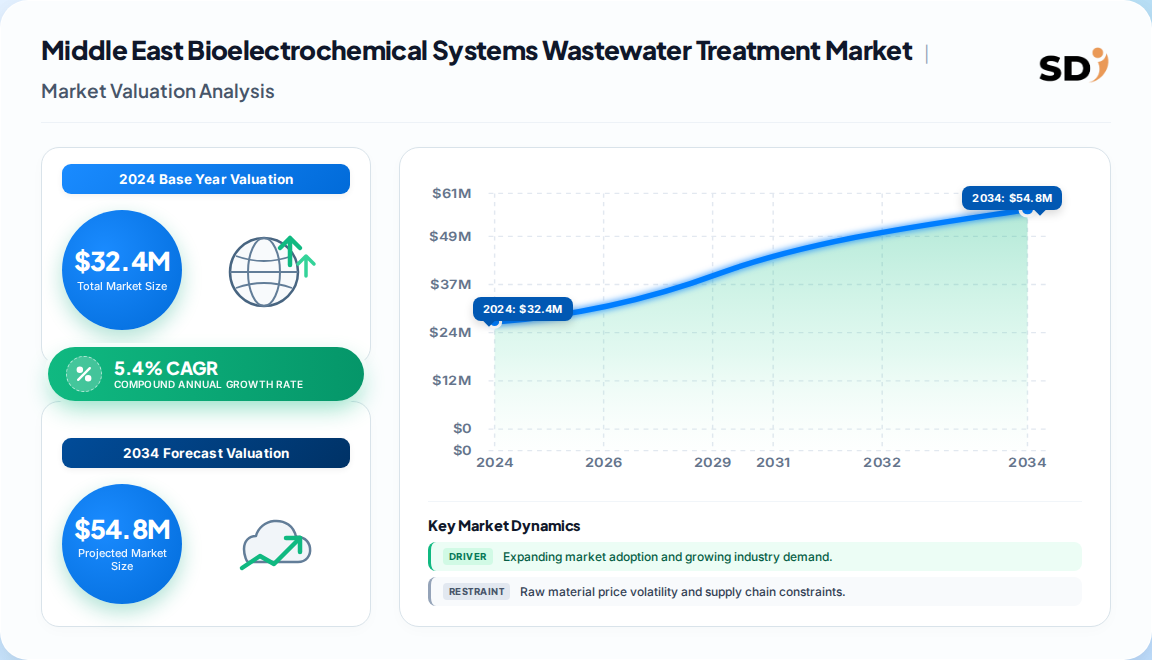
The Middle East BES wastewater treatment market comprises technologies—primarily microbial fuel cells (MFCs) and microbial electrolysis cells (MECs)—that use microorganisms to treat wastewater while generating electricity, hydrogen, or methane. Valued at USD 32.4 million in 2024, it serves municipal and industrial applications across water-scarce Gulf states.
This report covers BES technologies (MFCs, MECs, and hybrid systems) for municipal, industrial, and agricultural wastewater treatment across the Middle East, with country-level analysis for Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain, and Jordan. This analysis does not cover conventional activated sludge, membrane bioreactors, or other non-bioelectrochemical treatment technologies; nor does it address desalination or potable water treatment markets.
The market was estimated at USD 32.4 million in 2024, with forecasts reaching USD 50.5 million by 2033 at a 5.4% CAGR. A competing global analysis implies a much larger global BES market (USD 1.5 billion in 2025 growing at 11.9% CAGR), but that figure encompasses all regions and a broader technology definition.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 32.4 Mn | 2024 | 2033 | 5.4% | Middle East, BES only (MFC, MEC) | One published estimate |
| USD 1.5 Bn (global) | 2025 | 2035 | 11.9% | Global, all BES types | A competing analysis |
The Middle East-specific figure is more defensible for regional decision-making because it reflects the nascent commercialization stage, pilot-heavy landscape, and region-specific adoption barriers. The global CAGR of 11.9% is driven by mature markets (Asia Pacific, North America, Europe) and does not account for the Middle East's skills gap and limited track record.
The market is segmented by technology type and application. MFCs dominate revenue, while MECs offer faster growth potential tied to hydrogen recovery.
| Parent Segment | Children |
|---|---|
| By Type | Microbial Fuel Cells (MFCs), Microbial Electrolysis Cells (MECs), Others (MDCs, hybrid) |
| By Application | Municipal Wastewater, Industrial Wastewater, Agricultural Wastewater, Others |
Saudi Arabia leads with approximately 28% regional share, driven by Vision 2030 sustainability mandates and giga-project wastewater reuse requirements. The UAE follows at 24%, with the fastest growth at 6.1% CAGR, supported by advanced reuse targets and smart utility adoption.
| Country | Market Share (%) | Growth Outlook |
|---|---|---|
| Saudi Arabia | 28% | Largest absolute market; Vision 2030-driven |
| UAE | 24% | Fastest CAGR at 6.1%; smart utility pilots |
| Qatar | 11% | MEC pilots for biogas recovery |
| Kuwait | 9% | Academic and small-scale pilots |
| Oman | 8% | Emerging interest; limited commercialization |
| Bahrain | 6% | Nascent stage |
| Jordan | 5% | Water-stressed; donor-funded pilots |
| Rest of Middle East | 9% | Fragmented |
Water scarcity is the dominant driver: GCC states treat wastewater as a strategic resource, and BES offers dual value—pollutant removal plus energy recovery. However, limited commercialization, a skills gap, and scarce region-specific performance data restrain faster adoption.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Water scarcity | Driver | High | Mandates energy-efficient, resource-recovering treatment |
| Energy recovery value | Driver | High | MFCs offset 10–25% of plant parasitic energy |
| Government sustainability policies | Driver | High | Vision 2030, UAE Water Security Strategy 2036 |
| Green hydrogen ambitions | Driver | Medium | MECs produce hydrogen/methane, aligning with decarbonization |
| Limited commercialization | Restraint | High | Most installations at pilot scale (<100 m³/day) |
| Skills gap | Restraint | Medium | Shortage of trained bioelectrochemical engineers |
| Electrode degradation & fouling | Restraint | Medium | Maintenance complexity deters risk-averse utilities |
| Data deficit | Restraint | High | Scarce region-specific performance data for high-salinity, high-temperature wastewater |
No dominant regional corporation exists; the landscape is fragmented with academic institutions, municipal pilots, and niche technology providers. Global players like Cambrian Innovation, Paques BV, and METawater are active, while regional startups partner with research institutions.
| Company | Headquarters | Focus Area | Regional Presence |
|---|---|---|---|
| Cambrian Innovation | USA | MFC/MEC systems | Pilot partnerships in UAE |
| Paques BV | Netherlands | Anaerobic BES | Industrial wastewater projects |
| METawater Co., Ltd. | Japan | MFC integration | Smart utility pilots |
| Electrochaea GmbH | Germany | MEC for methane | Green hydrogen alignment |
| Genesis Water Technologies | USA | Decentralized BES | Distributor-led presence |
| Local research startups | Saudi Arabia, UAE | Niche MFC/MEC configurations | Pilot-scale deployments |
Differentiation hinges on proven performance in high-salinity, high-temperature conditions—a capability gap that global vendors have yet to fully address. Regional startups with validated pilot data hold a competitive moat, making them attractive acquisition targets for larger environmental firms.
Buyers must prioritize total cost of ownership over headline energy savings, as electrode replacement and membrane fouling can erode gains. Procurement should demand region-specific performance guarantees, including salinity tolerance and temperature resilience. Switching costs are high due to integration complexity, so pilot validation before full-scale deployment is essential. Regulatory compliance with water reuse standards and carbon reduction targets is non-negotiable; vendors lacking local case studies face longer sales cycles. Utilities should also assess vendor support depth, as the skills gap means operators will rely on supplier training and maintenance contracts.
The balance of evidence favors early, targeted investment in modular MFC pilots in Saudi Arabia and the UAE, where policy tailwinds and water scarcity create a captive demand signal. The strongest counter-argument is that BES remains unproven at scale, and conventional technologies may improve faster; however, the region's energy-neutral treatment targets and green hydrogen ambitions create a niche where BES's dual value is irreplaceable.
Our analysis suggests that the pilot-to-scale gap is the single biggest commercial opportunity: firms that bridge it with validated, region-specific performance data will capture disproportionate share as the market consolidates post-2026. Waiting for global incumbents to enter cedes first-mover advantage in a market where local proof points are the primary barrier.
Actionable Strategy:
Evidence that would change our conclusion: a major global player commercializing a modular BES unit with proven Middle East performance data, or a significant drop in electrode costs, would alter the competitive landscape and favor incumbents over startups.
| Region | Market Share (%) |
|---|---|
| Saudi Arabia | 0.28% |
| UAE | 0.24% |
| Qatar | 0.11% |
| Kuwait | 0.09% |
| Oman | 0.08% |
| Bahrain | 0.06% |
| Jordan | 0.05% |
| Rest of Middle East | 0.09% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.4% from 2020-2034 |
| Segmentation |
|
The market was estimated at USD 32.4 million in 2024 and is projected to reach USD 50.5 million by 2033, growing at a 5.4% CAGR from 2025 to 2033.
Saudi Arabia leads with approximately 28% regional share, driven by Vision 2030 sustainability mandates. The UAE is the fastest-growing country at 6.1% CAGR.
Microbial Fuel Cells (MFCs) dominate with 56.7% revenue share, while Microbial Electrolysis Cells (MECs) are growing faster due to hydrogen and methane recovery potential.
Water scarcity, energy recovery value, and government sustainability policies are key drivers. BES offers dual benefits: wastewater treatment and energy generation, critical for water-stressed GCC states.
The market is fragmented with no dominant regional player. Global players like Cambrian Innovation, Paques BV, and METawater are active, alongside local research startups.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split, with in-depth interviews conducted across the BES wastewater treatment value chain. We engaged with technology developers, municipal utility operators, industrial wastewater managers, and component suppliers. Decision-maker roles interviewed include VP of Engineering, Heads of Sustainability, Technical Directors, and Commercial Operations Leads. This fieldwork captures granular insights into adoption barriers, pilot performance, and procurement criteria.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Technical Directors & Engineers | 40% |
| Sustainability & Regulatory Leads | 30% |
| Procurement & Sourcing Managers | 20% |
| Commercial Operations Leads | 10% |
| Company Type | Representation (%) |
|---|---|
| Technology Developers & OEMs | 40% |
| Municipal Utility Operators | 30% |
| Industrial Wastewater Managers | 20% |
| Component & Material Suppliers | 10% |
We triangulate findings against official multilateral databases including UN Comtrade, WTO trade statistics, US ITC, and Eurostat for trade flows. Corporate annual filings (10-K, SEC filings, investor presentations), patent databases (WIPO, USPTO), and technical standards from ISO and regional water associations validate our market sizing and competitive intelligence. No competitor market research firms are cited.
We apply simultaneous Top-Down (macroeconomic indicators, water scarcity indices, regulatory mandates) and Bottom-Up (manufacturer capacity, pilot project counts, pricing, end-use consumption) modeling to derive market estimates. This dual approach ensures robustness against data gaps in nascent markets.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2024 | Bottom-up pilot project counts & revenue triangulation | High |
| Forecast Horizon | 2025–2033 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Country-level share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading vendors & startups | Annual reports, capacity mapping & commercial filings | High |