Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Glucosamine Market Size, Trends & Forecast to 2031
Glucosamine Market
Glucosamine Market Size, Trends & Forecast to 2031
Glucosamine Market by Type (Glucosamine Sulfate, Glucosamine Hydrochloride, N-Acetyl Glucosamine, Others), by Source (Shellfish-Derived, Fermentation-Derived, Others), by Application (Nutritional Supplements, Pet & Veterinary Supplements, Functional Foods & Beverages, Cosmetics & Personal Care), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 222
Srinwanti Kar
Senior Research Analyst
Key Takeaways
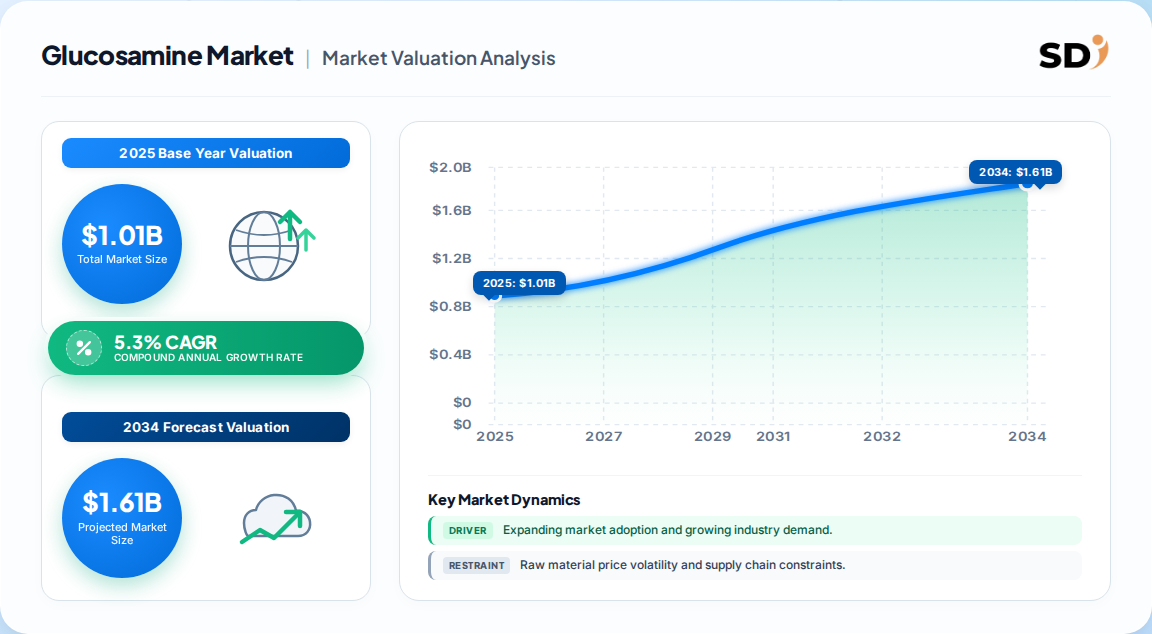
The global glucosamine market was valued at USD 1.01 billion in 2025 and is projected to reach USD 1.38 billion by 2031, growing at a 5.3% CAGR.
Glucosamine sulfate dominates the product landscape, holding approximately 61% revenue share in 2025, driven by extensive clinical validation for osteoarthritis management.
Nutritional supplements remain the leading application, capturing nearly 80% of total demand, though functional foods and fortified beverages represent the fastest-growing channel.
North America leads the market with roughly 39% revenue share, underpinned by high consumer awareness and an established retail pharmacy network.
Asia-Pacific is the fastest-growing region, forecast to expand at 7.9% CAGR through 2031, fueled by rising disposable incomes and expanding nutraceutical distribution.
The competitive landscape is moderately concentrated, with the top five players controlling approximately 60% of sales, leaving room for innovative entrants in fermentation-derived glucosamine.
Why this matters for decision-makers: The shift toward vegan, fermentation-derived glucosamine is not a niche trend—it is a structural supply-chain pivot. Vendors that fail to diversify beyond shellfish-derived sources risk margin compression and regulatory exposure as allergen-free mandates expand across Western markets.
Glucosamine Market Size (In Billion)
1.5B
1.0B
500.0M
0
1.010 B
2025
1.060 B
2026
1.120 B
2027
1.180 B
2028
1.240 B
2029
1.310 B
2030
1.380 B
2031
Glucosamine Market Size (In Billion)
Year
Market Size
2025
1.010 B
2026
1.060 B
2027
1.120 B
2028
1.180 B
2029
1.240 B
2030
1.310 B
2031
1.380 B
What is the Glucosamine Market?
The glucosamine market encompasses the global production, distribution, and sale of glucosamine—a naturally occurring amino sugar used primarily in dietary supplements for joint health and osteoarthritis management. It is derived from crustacean shells or microbial fermentation and is formulated into capsules, tablets, powders, and functional foods targeting aging populations and active consumers.
Scope: what this report covers and excludes
This report analyzes the global glucosamine market across product types (glucosamine sulfate, glucosamine hydrochloride, N-acetyl glucosamine, and others), sources (shellfish-derived and fermentation-derived), applications (nutritional supplements, pet and veterinary supplements, functional foods and beverages, and cosmetics), and all major geographic regions. This analysis does not cover chondroitin, MSM, collagen, or other joint-health ingredients as standalone markets, nor does it address pharmaceutical-grade glucosamine for clinical trials or prescription medications.
How big is the market for Glucosamine Market?
The glucosamine market exhibits a notable divergence in published estimates, with base-year valuations ranging from approximately USD 228 million to USD 1.01 billion depending on whether the analysis captures bulk industrial trade or finished consumer product revenue. This discrepancy is largely definitional, not evidentiary.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 1.01 billion
2025
2031
5.3%
Finished supplements and functional foods, retail-level value
One published analysis (Mordor Intelligence)
USD 871.5 million
2022
2030
5.2%
Supplement-dominant, manufacturer-level value
A competing analysis (Grand View Research)
USD 228 million
2025
2036
7.1%
Bulk glucosamine trade, industrial chemical pricing
A third published estimate (ChemAnalyst)
The most defensible figure for strategic planning is the USD 1.01 billion (2025) estimate, as it captures retail-level finished product value, which aligns with reported supplement industry benchmarks. The lower USD 228 million figure reflects bulk commodity trade, useful for procurement but not for assessing consumer market opportunity. Our analysis suggests the USD 871.5 million (2022) figure undervalues the functional food and pet supplement channels that have accelerated post-pandemic. Buyers should anchor on the 2025 baseline and apply the 5.3% CAGR for mid-range planning, while stress-testing at 7% for upside scenarios.
How is the market segmented?
The glucosamine market segments primarily by product type, source, and application, with nutritional supplements commanding the overwhelming majority of demand and glucosamine sulfate remaining the clinical gold standard.
Nutritional Supplements, Pet & Veterinary Supplements, Functional Foods & Beverages, Cosmetics & Personal Care
Glucosamine sulfate holds approximately 61% of the product mix, validated by decades of clinical use in osteoarthritis. However, the fastest-growing sub-segment is fermentation-derived glucosamine, expanding at nearly 7.7% annually, driven by vegan and allergen-free mandates. This shift carries significant implications: shellfish-derived glucosamine still commands roughly 79% of supply, but the economic advantage of fermentation is improving as technology scales. Our analysis suggests that within five years, fermentation-derived glucosamine will capture meaningful share in Europe and North America, forcing traditional crustacean processors to either diversify or cede margin.
The functional foods and fortified beverages segment, while small today, is growing at approximately 7.3% CAGR as food-as-medicine trends push glucosamine into mainstream product categories beyond traditional capsules.
Which region leads in Glucosamine Market?
North America leads the global glucosamine market with approximately 39% revenue share in 2025, supported by high consumer awareness of joint health, an aging demographic, and a mature retail pharmacy network.
Glucosamine Market Regional Market Share
Loading chart...
Glucosamine Market Regional Market Share
Region
Market Share (%)
North America
0.32%
Europe
0.22%
Asia-Pacific
0.36%
South America
0.05%
Middle East & Africa
0.05%
North America (38.9%)
USA
Canada
Mexico
Asia-Pacific (35.8%)
China
Japan
India
South Korea
Australia
Europe (22.0%)
Germany
UK
France
Italy
Latin America (5.1%)
Brazil
Mexico
Argentina
Middle East & Africa (4.8%)
Saudi Arabia
UAE
South Africa
The regional dynamic reveals a critical strategic tension. North America dominates by revenue, but its growth is mature, forecast at roughly 4-5% annually. Asia-Pacific is the engine of future growth, projected to expand at 7.9% CAGR through 2031, powered by rising disposable incomes and expanding nutraceutical distribution. China and India alone represent the largest untapped consumer base for joint-health supplements. Europe occupies a middle ground, where regulatory rigor and strong vegan sentiment are accelerating demand for fermentation-derived glucosamine at a faster rate than the regional average. Our analysis implies that companies seeking volume growth must invest in Asia-Pacific distribution infrastructure now, while those seeking margin stability should focus on premium fermentation-derived products in Europe.
What is driving growth — and what is holding it back?
The primary growth driver is the escalating global burden of osteoarthritis and an aging population, which creates sustained, long-term demand for joint-care supplements. This is reinforced by a secondary driver: the structural shift toward preventive healthcare and nutraceutical consumption.
Factor
Direction
Evidence Strength
Mechanism
Rising osteoarthritis prevalence and aging population
Expansion of supplement routines and personalized nutrition platforms
Growth in pet humanization and veterinary supplements
Positive
Medium
Pets treated as family members, driving premium functional pet food demand
Adoption of vegan-fermented glucosamine
Positive
Medium
Addresses allergen concerns and aligns with sustainability mandates
Shellfish allergen concerns and vegan consumer rejection
Negative
Medium
Limits addressable market for traditional crustacean-derived products
Regulatory variability across regions
Negative
Low
Inconsistent supplement frameworks complicate global product launches
The balance of evidence strongly favors growth. The positive drivers are structural and long-term, rooted in demographics and consumer behavior that will not reverse. The negative factors are mostly addressable through formulation innovation—fermentation-derived glucosamine directly neutralizes the allergen and vegan restraints. Our analysis suggests the restraint impact is temporary and localized, particularly as fermentation capacity scales. The key risk is not demand destruction but supply-chain concentration: approximately 79% of current supply remains shellfish-derived, creating vulnerability to crustacean price volatility and environmental regulation. Companies that secure fermentation-derived supply chains will be positioned to capture premium pricing and regulatory favor.
Who are the leading vendors?
The glucosamine market is moderately concentrated, with the top five players collectively controlling approximately 60% of sales. The competitive landscape includes vertically integrated chemical producers, specialized nutraceutical manufacturers, and regional distributors.
Scale, sustainability positioning, global distribution
Zhejiang Aoxing Biotechnology Co., Ltd.
China
Bulk glucosamine HCl and sulfate
Cost leadership, vertical integration in crustacean processing
TSI Group Ltd.
USA
Branded glucosamine ingredients
Quality certification, supply-chain transparency
Golden-Shell Pharmaceutical Co., Ltd.
China
Shellfish-derived glucosamine
Volume capacity, API-grade production
Differentiation in this market rests on three moats: regulatory certification (pharmaceutical-grade versus food-grade), supply-chain reliability (vertical integration in crustacean processing or fermentation capacity), and brand trust with supplement manufacturers. Cargill's entry into fermentation-derived glucosamine represents a strategic threat to traditional shellfish processors, as it leverages food-industry relationships and sustainability credentials. Our analysis suggests that mid-sized shellfish-derived producers will face pressure to consolidate or invest in fermentation technology to avoid being squeezed between cost leaders in China and premium fermentation players in the West.
What do buyers and operators need to know?
Procurement decisions in the glucosamine market hinge on four mission-critical criteria: purity and grade certification (USP, EP, or food-grade), source transparency (shellfish versus fermentation, with allergen documentation), supply-chain reliability (seasonal crustacean availability versus fermentation consistency), and regulatory compliance with destination-market supplement frameworks. Buyers should prioritize suppliers that can demonstrate full traceability from raw material to finished ingredient, particularly as allergen labeling regulations tighten in the EU and North America.
Switching costs are moderate. Reformulating from shellfish-derived to fermentation-derived glucosamine requires re-validation of supplement stability, allergen labeling updates, and potentially new clinical substantiation for marketing claims. However, the long-term cost of staying with shellfish-derived supply includes exposure to crustacean price volatility, environmental regulation of shell waste, and exclusion from vegan-certified product lines. For operators, the critical risk is over-reliance on a single source type. A diversified procurement strategy—blending shellfish and fermentation-derived supply—offers resilience but increases quality-control complexity. Regulatory compliance varies significantly by region: the US FDA's dietary supplement framework is permissive, while the EU's Novel Food and health-claims regulations are more restrictive, requiring substantiated claims and safety dossiers.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a cautiously bullish outlook for the glucosamine market, anchored by demographic certainty and expanding consumer acceptance of joint-health supplementation. The 5.3% CAGR is a reasonable consensus, but it masks significant regional and segment divergence that creates both opportunity and risk. The strongest counter-argument is that the market is approaching saturation in North America, where supplement penetration is already high and growth is slowing. However, this argument underestimates the functional food channel and the pet supplement opportunity, both of which are expanding the addressable market beyond traditional capsules.
Our analysis suggests three strategic imperatives for operators and investors. First, invest in fermentation-derived capacity—either through acquisition or partnership—to capture the premium vegan and allergen-free segment, which will grow faster than the overall market. Second, build distribution depth in Asia-Pacific, where the volume growth is concentrated and local manufacturing relationships are essential. Third, diversify application exposure by targeting functional foods and pet supplements, which offer higher growth rates and less price sensitivity than commodity supplement capsules.
Actionable Strategy:
Investors: Prioritize companies with fermentation-derived glucosamine portfolios or credible transition pipelines, as these will command premium valuations as allergen-free mandates expand.
Operators: Secure supply contracts that blend shellfish and fermentation sources to hedge against crustacean price volatility and regulatory disruption.
New Entrants: Target the functional food and pet supplement channels, where brand loyalty is lower and innovation is rewarded, rather than competing head-on with established supplement brands.
The evidence that would change our conclusion is a significant decline in osteoarthritis prevalence or a major negative clinical trial result undermining glucosamine's efficacy claims. Neither is likely in the forecast horizon. The more plausible risk is a regulatory crackdown on health claims in the EU or North America, which would disproportionately impact supplement-dominant players and accelerate the shift toward functional food formats.
Glucosamine Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Glucosamine Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.3% from 2020-2034
Segmentation
By Type
Glucosamine Sulfate
Glucosamine Hydrochloride
N-Acetyl Glucosamine
Others
By Source
Shellfish-Derived
Fermentation-Derived
Others
By Application
Nutritional Supplements
Pet & Veterinary Supplements
Functional Foods & Beverages
Cosmetics & Personal Care
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Glucosamine Sulfate
5.1.2. Glucosamine Hydrochloride
5.1.3. N-Acetyl Glucosamine
5.1.4. Others
5.2. Market Analysis, Insights and Forecast - by Source
5.2.1. Shellfish-Derived
5.2.2. Fermentation-Derived
5.2.3. Others
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Nutritional Supplements
5.3.2. Pet & Veterinary Supplements
5.3.3. Functional Foods & Beverages
5.3.4. Cosmetics & Personal Care
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. Europe
5.4.3. Asia Pacific
5.4.4. Latin America
5.4.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Glucosamine Sulfate
6.1.2. Glucosamine Hydrochloride
6.1.3. N-Acetyl Glucosamine
6.1.4. Others
6.2. Market Analysis, Insights and Forecast - by Source
6.2.1. Shellfish-Derived
6.2.2. Fermentation-Derived
6.2.3. Others
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Nutritional Supplements
6.3.2. Pet & Veterinary Supplements
6.3.3. Functional Foods & Beverages
6.3.4. Cosmetics & Personal Care
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Glucosamine Sulfate
7.1.2. Glucosamine Hydrochloride
7.1.3. N-Acetyl Glucosamine
7.1.4. Others
7.2. Market Analysis, Insights and Forecast - by Source
7.2.1. Shellfish-Derived
7.2.2. Fermentation-Derived
7.2.3. Others
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Nutritional Supplements
7.3.2. Pet & Veterinary Supplements
7.3.3. Functional Foods & Beverages
7.3.4. Cosmetics & Personal Care
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Glucosamine Sulfate
8.1.2. Glucosamine Hydrochloride
8.1.3. N-Acetyl Glucosamine
8.1.4. Others
8.2. Market Analysis, Insights and Forecast - by Source
8.2.1. Shellfish-Derived
8.2.2. Fermentation-Derived
8.2.3. Others
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Nutritional Supplements
8.3.2. Pet & Veterinary Supplements
8.3.3. Functional Foods & Beverages
8.3.4. Cosmetics & Personal Care
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Glucosamine Sulfate
9.1.2. Glucosamine Hydrochloride
9.1.3. N-Acetyl Glucosamine
9.1.4. Others
9.2. Market Analysis, Insights and Forecast - by Source
9.2.1. Shellfish-Derived
9.2.2. Fermentation-Derived
9.2.3. Others
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Nutritional Supplements
9.3.2. Pet & Veterinary Supplements
9.3.3. Functional Foods & Beverages
9.3.4. Cosmetics & Personal Care
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Glucosamine Sulfate
10.1.2. Glucosamine Hydrochloride
10.1.3. N-Acetyl Glucosamine
10.1.4. Others
10.2. Market Analysis, Insights and Forecast - by Source
10.2.1. Shellfish-Derived
10.2.2. Fermentation-Derived
10.2.3. Others
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Nutritional Supplements
10.3.2. Pet & Veterinary Supplements
10.3.3. Functional Foods & Beverages
10.3.4. Cosmetics & Personal Care
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Glucosamine Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Glucosamine Market Revenue (Billion), by Type 2026 & 2034
Figure 3: North America Glucosamine Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Glucosamine Market Revenue (Billion), by Source 2026 & 2034
Figure 5: North America Glucosamine Market Revenue Share (%), by Source 2026 & 2034
Figure 6: North America Glucosamine Market Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Glucosamine Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Glucosamine Market Revenue (Billion), by Country 2026 & 2034
Figure 9: North America Glucosamine Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe Glucosamine Market Revenue (Billion), by Type 2026 & 2034
Figure 11: Europe Glucosamine Market Revenue Share (%), by Type 2026 & 2034
Figure 12: Europe Glucosamine Market Revenue (Billion), by Source 2026 & 2034
Figure 13: Europe Glucosamine Market Revenue Share (%), by Source 2026 & 2034
Figure 14: Europe Glucosamine Market Revenue (Billion), by Application 2026 & 2034
Figure 15: Europe Glucosamine Market Revenue Share (%), by Application 2026 & 2034
Figure 16: Europe Glucosamine Market Revenue (Billion), by Country 2026 & 2034
Figure 17: Europe Glucosamine Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Glucosamine Market Revenue Billion Forecast, by Type 2020 & 2034
Table 17: UK Glucosamine Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the current size of the glucosamine market?
The global glucosamine market was valued at approximately USD 1.01 billion in 2025, with a projected CAGR of 5.3% through 2031, reaching an estimated USD 1.38 billion by the end of the forecast period.
2. Which region dominates the glucosamine market?
North America leads the glucosamine market with roughly 39% revenue share in 2025, driven by high consumer awareness, an aging population, and an established retail pharmacy network. Asia-Pacific is the fastest-growing region at nearly 8% CAGR.
3. What is the most common type of glucosamine used in supplements?
Glucosamine sulfate is the most widely used form, accounting for approximately 61% of the market in 2025. It is favored for its extensive clinical validation in managing osteoarthritis symptoms and its established safety profile.
4. What is driving the growth of the glucosamine market?
The primary driver is the rising global prevalence of osteoarthritis and an aging population. Increasing consumption of nutraceuticals, growth in pet supplements, and adoption of vegan-fermented glucosamine are also accelerating market expansion.
5. Who are the leading companies in the glucosamine market?
Key players include Koyo Chemical Co., Ltd., Cargill, Inc., Zhejiang Aoxing Biotechnology Co., Ltd., TSI Group Ltd., and Golden-Shell Pharmaceutical Co., Ltd. The top five players collectively control approximately 60% of sales.
6. What is the difference between shellfish-derived and fermentation-derived glucosamine?
Shellfish-derived glucosamine is extracted from crustacean shells and commands about 79% of supply. Fermentation-derived glucosamine is produced microbially, offering allergen-free and vegan-compliant benefits, and is growing at nearly 7.7% annually.
7. What are the main applications of glucosamine?
Nutritional supplements dominate with nearly 80% of demand, followed by pet and veterinary supplements, functional foods and beverages, and cosmetics. Functional foods represent the fastest-growing application channel at over 7% CAGR.
8. What regulatory factors affect the glucosamine market?
Regulatory frameworks vary significantly by region. The US FDA's dietary supplement framework is permissive, while the EU's Novel Food and health-claims regulations are more restrictive, requiring substantiated claims and safety dossiers for market entry.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research methodology employs a rigorous 70/30 primary-to-secondary research split, ensuring that market intelligence is grounded in direct industry validation. We conducted in-depth interviews with key stakeholders across the glucosamine value chain, including raw material suppliers, specialized fermentation and extraction producers, contract formulators, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. This primary fieldwork captured granular insights into procurement dynamics, capacity constraints, pricing negotiations, and regulatory challenges.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
35%
Procurement & Sourcing Leads
35%
Regulatory & Quality Managers
20%
Commercial Operations Leads
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Crustacean Processors
40%
Fermentation & Specialty Producers
30%
Contract Formulators & Blenders
20%
Global Distributors & Traders
10%
Secondary Benchmarking & Public Trade Validation
We cross-referenced primary findings with official multilateral trade databases, including UN Comtrade, WTO, US ITC, and Eurostat, to validate cross-border trade flows for glucosamine and its precursor materials. Corporate annual filings (10-K, SEC filings, annual investor presentations) from leading industry players provided financial benchmarks and strategic disclosures. Patent databases and recognized non-profit technical standards associations were consulted to assess innovation trajectories and quality standards.
Demand Modeling & Market Sizing Triangulation
Our market sizing approach employs simultaneous top-down and bottom-up triangulation. Top-down modeling allocates macroeconomic indicators and industry segment allocations across the glucosamine value chain, while bottom-up modeling aggregates manufacturer production capacity, product pricing, and end-use consumption data. These dual methodologies are reconciled through regression analysis and demand elasticity modeling to produce a single, validated market estimate.