 Pet Funeral Services Market
: 2025 Size, CAGR & Outlook
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 199

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Pet Funeral Services Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 2.110 B |
| 2026 | 2.320 B |
| 2027 | 2.560 B |
| 2028 | 2.820 B |
| 2029 | 3.100 B |
| 2030 | 3.420 B |

The Pet Funeral Services Market covers paid end-of-life care for companion animals: burial, cremation (communal, partitioned, private), memorial products and keepsakes, and digital or virtual memorials. Services are delivered through veterinary clinics, specialized providers, and direct-to-consumer channels, typically in offline settings or on online booking platforms.
This analysis covers global pet funeral services across service type, pet type, end user, and distribution channel, with regional breakdowns for North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. This analysis does not cover veterinary clinical treatment, pet insurance underwriting, live-animal retail, or human funeral services except where human funeral chains extend into the pet segment.
Estimates cluster around USD 2.0–2.1 billion for 2025, with 2030 forecasts spanning USD 3.06–3.42 billion. Divergence stems from scope: broader definitions include memorial products and digital platforms; narrower ones count core burial and cremation only.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 2.11B → USD 3.42B | 2025 | 2030 | 10.08% | Full service, pet type, end user, channel | One published estimate |
| USD 2.03B → USD 3.06B | 2026 | 2030 | 10.8% | Service type, pet type, indoor/outdoor | A competing analysis |
| USD 2.1B → USD 4.0B | 2026 | 2034 | 8.09% | Burial and cremation, pet type, region | A competing analysis |
| Europe: USD 588.7M (2025) → USD 1,204.0M | 2025 | 2033 | 9.4% | Burial and cremation, provider type | A competing analysis |
Our analysis suggests the USD 2.11B / 10.08% / 2030 figure is the most defensible anchor. Its scope is explicit across four non-geographic axes, and its growth rate sits between the slower 8.09% long-horizon view and the faster 10.8% short-horizon view, consistent with cremation adoption maturing in North America while accelerating in Asia-Pacific.
Segmentation follows four non-geographic axes: service type, pet type, end user, and distribution channel. Every axis favors a shift toward convenience and personalization.
| Parent segment | Children | 2024 share / growth signal |
|---|---|---|
| Service type | Burial, Cremation, Memorial products & keepsakes, Digital/virtual memorials | Cremation 61.24%; digital memorials 13.83% CAGR |
| Pet type | Dogs, Cats, Small mammals, Birds, Other pets | Dogs 46.82%; cats 12.88% CAGR |
| End user | Veterinary clinics & hospitals, Direct-to-consumer, Others | Clinics 39.58%; DTC 13.55% CAGR |
| Distribution channel | Offline, Online | Offline 69.37%; online 14.72% CAGR |
North America leads with 35.71% of 2024 revenue, underpinned by high pet-humanization, dense urban zoning constraints on burial, and cremation penetration above 59%. Asia-Pacific is the fastest-growing region at 12.57% CAGR, led by Japan, China, and Australia.
| Region | Market Share (%) |
|---|---|
| North America | 0.36% |
| Europe | 0.28% |
| Asia-Pacific | 0.24% |
| South America | 0.07% |
| Middle East & Africa | 0.05% |
| Region | 2024/2025 share | Growth signal |
|---|---|---|
| North America | 35.71% | Mature, consolidation-driven |
| Europe | 34.1% (2025) | 9.4% CAGR to 2033 |
| Asia-Pacific | ~24% | 12.57% CAGR, fastest |
| Latin America | ~4% | Emerging, price-sensitive |
| Middle East & Africa | ~2% | Early-stage, cultural variance |
Pet-humanization is the single largest growth driver, adding an estimated 2.8 percentage points to CAGR, followed by rising pet ownership (+2.1 pts) and the cremation-over-burial shift (+1.9 pts). Together these outweigh the heaviest restraint, fragmented regulation (−1.8 pts).
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising pet-humanization | Driver | High | 97% of owners treat pets as family; grief parity with human loss boosts full-service packages |
| Pet ownership & spending | Driver | High | 94M US households own a pet (2025); millennial/Gen Z premium uptake |
| Cremation preference | Driver | High | 59%+ of North American dispositions; urban space limits |
| Human funeral chain entry | Driver | Medium | SCI deployed USD 181M into 26 dual-capability funeral homes in 2024 |
| Fragmented regulation | Restraint | Medium | Inconsistent crematoria standards raise compliance cost |
| Price sensitivity in emerging markets | Restraint | Medium | Caps average basket size in Asia-Pacific, Latin America, MEA |
| Cultural/religious reluctance | Restraint | Low–Medium | Slows cremation adoption in traditional communities |
The balance favors growth, but the restraint profile is geographic, not structural. Regulation is the binding constraint in developed markets, where compliance cost rewards scaled, certified operators; price sensitivity binds in emerging markets, where partitioned cremation and mobile clinics are the entry format.
The market is low-concentration, with no single player above double-digit global share. Leadership is regional: North American integrated chains, European specialist crematoria, and Asia-Pacific funeral-service groups.
| Company | HQ / footprint | Model emphasis | Moat |
|---|---|---|---|
| Service Corporation International | USA | Dual human-pet funeral homes and cemeteries | Asset utilization, community presence |
| InvoCare (Pets in Peace) | Australia | Volume pet cremation and memorials | Scale, referral networks |
| Veternity | France/Europe | Veterinary-linked cremation network | Clinic integration |
| CVS Group PLC | UK | Veterinary practice groups with aftercare | Captive clinic channel |
| Anima Care | Europe | Specialized pet cremation | Certification, service quality |
| Pets in Peace | Australia | Direct-to-consumer memorials | Brand, digital booking |
Differentiation rests on three levers: verified chain-of-custody (individual cremation trust), clinic referral lock-in (captive end-user channels), and digital memorial subscription (recurring revenue beyond the one-off service). Our analysis suggests clinic-captive models earn the highest retention but the lowest margin, while direct-to-consumer digital bundles earn the highest margin per transaction.
Selection criteria center on individual versus communal cremation verification, chain-of-custody documentation, turnaround time, and grief-support add-ons. Buyers should demand written certification of individual processing, not verbal assurance; the reputational cost of mislabeled communal cremation is severe and increasingly litigated.
Procurement risk is concentrated in regulatory variance: cremator emission limits, burn-rate rules, and shipping protocols for remains differ materially by jurisdiction, so multi-site operators must budget for compliance localization rather than assume portability. Switching costs are moderate for veterinary clinics (referral contracts, pickup logistics) but low for direct consumers (price and convenience dominate). Regulatory compliance is non-negotiable: certified handling, emission monitoring, and clean transportation packaging are prerequisites, not differentiators.
The balance of evidence favors a cremation-led, digitally-augmented growth strategy over a burial-centric or premium-ceremony-led one. Cremation already commands 61% of revenue and is compounding fastest within service type, while digital memorials are the only segment growing above 13% CAGR. The strongest counter-argument is that Asia-Pacific premium human-style ceremonies in Japan and China could outpace cremation volume growth; that is credible, but ceremony revenue remains concentrated in a few cultural markets and does not travel.
Our second-order read is that consolidation is the quiet story. Human funeral chains converting idle cremators carry a structural cost advantage that independent operators cannot match without scale, which implies mid-tier independents will either be acquired or retreat to niche, high-touch memorialization. Regulation accelerates this: certified, monitored facilities become the entry ticket, squeezing subscale operators.
What would change our conclusion: a sustained regulatory crackdown on cremator emissions that raises fixed costs faster than volume growth, or evidence that direct-to-consumer online platforms capture more than 25% of bookings. Either would shift advantage decisively toward the largest, most compliant networks.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
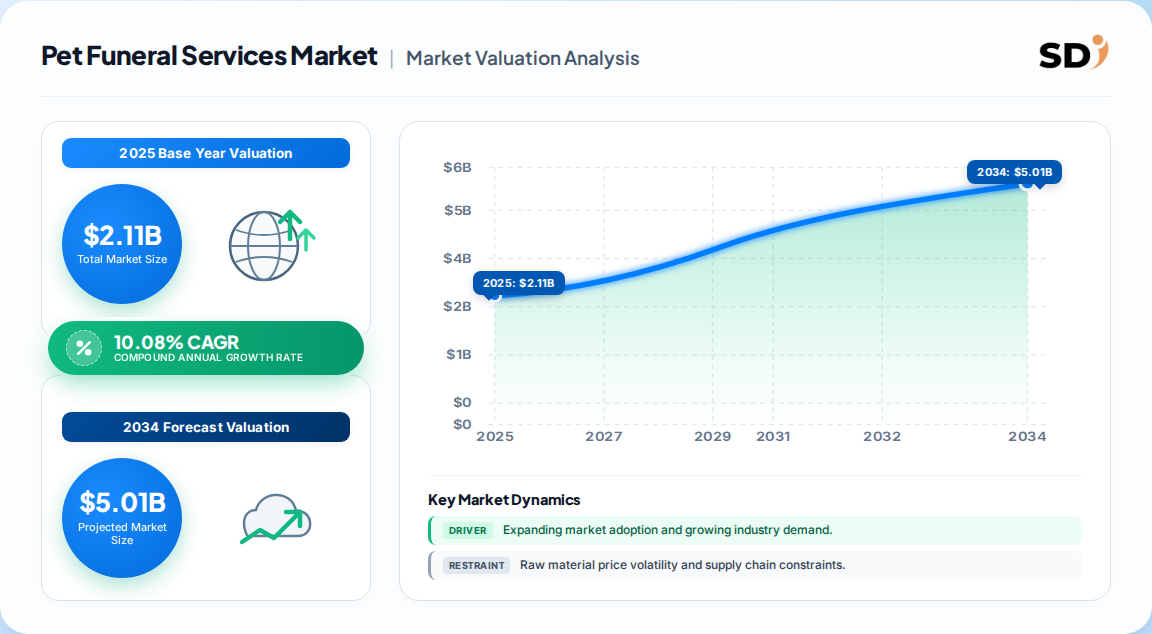
| Growth Rate | CAGR of 10.08% from 2020-2034 |
| Segmentation |
|
The global market stood at approximately USD 2.11 billion in 2025 and is forecast to reach USD 3.42 billion by 2030, growing at a 10.08% CAGR. Estimates vary slightly by scope, with narrower definitions placing 2025 near USD 1.8–1.9 billion.
Cremation dominates, holding 61.24% of 2024 revenue, and is also the fastest-growing major service. Digital and virtual memorials are the fastest-growing niche at 13.83% CAGR, though from a small base.
Asia-Pacific is the fastest-growing region at 12.57% CAGR through 2030, driven by urbanization, rising pet ownership, and limited burial space. North America remains the largest region at roughly 36% share.
Leading providers include Service Corporation International, InvoCare (Pets in Peace), Veternity, CVS Group, Anima Care, and Pets in Peace. The market is low-concentration, with leadership fragmented by region rather than consolidated globally.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split. In-depth interviews were conducted across the value chain, including crematoria equipment manufacturers, specialized pet aftercare providers, veterinary practice groups, memorial product suppliers, and regional distributors. Decision-maker designations included Vice Presidents of Operations, Heads of Clinical Partnerships, Technical Directors for crematoria compliance, and Commercial Operations Leads responsible for direct-to-consumer channels.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Operations & Commercial Leads | 40% |
| Clinical Partnership Heads | 30% |
| Technical & Compliance Directors | 30% |
| Company Type | Representation (%) |
|---|---|
| Specialized Pet Aftercare Providers | 40% |
| Veterinary Practice Groups | 30% |
| Crematoria Equipment & Memorial Suppliers | 20% |
| Regional Distributors & Online Platforms | 10% |
Secondary validation draws on UN Comtrade and Eurostat trade flows for cremation equipment and memorial products, national regulatory filings on cremator emissions and burn-rate limits, corporate annual reports and SEC filings from listed funeral and veterinary groups, patent databases covering cremation and aquamation technology, and recognized veterinary and funeral-service industry associations.
We triangulate Top-Down macro allocation (household pet ownership, mortality rates, spend per disposition) against Bottom-Up modeling (crematoria capacity, throughput per chamber, average service pricing, and end-use consumption by channel). Regional and segment forecasts are reconciled to a single consensus base.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up capacity & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border equipment flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |