 Us Mass Notification Systems Market
US Mass Notification Systems Market: 2026 Size, CAGR & Outlook
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 186

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Mass Notification Systems Market
Srinwanti Kar
Senior Research Analyst

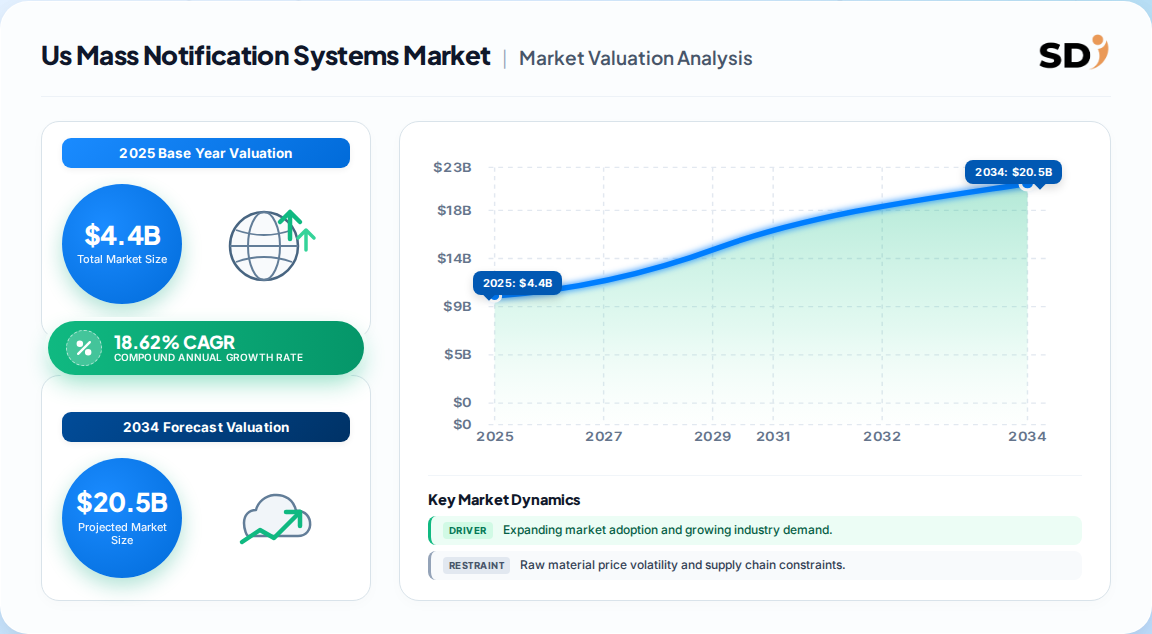
| Year | Market Size |
|---|---|
| 2025 | 4.400 B |
| 2026 | 5.220 B |
| 2027 | 6.190 B |
| 2028 | 7.350 B |
| 2029 | 8.710 B |
| 2030 | 10.34 B |
| 2031 | 12.27 B |

The US mass notification systems market covers the hardware, software and services used to disseminate time-critical alerts to defined populations — building occupants, distributed staff, students, residents or the public — across SMS, voice, sirens, digital signage, email and app channels. It spans in-building, wide-area outdoor and distributed-recipient architectures sold to government, education, healthcare and enterprise buyers.
This analysis covers US-only demand for mass notification platforms, components and services across seven end-user verticals and six communication channels, spanning 2021 historicals through 2031 forecasts. This analysis does not cover consumer messaging apps, general marketing automation, standalone 911 call-handling infrastructure, or non-US geographies except where cited as benchmarks.
Estimates cluster around a 4.3–4.4 Billion USD 2025 base, converging on roughly 18.6% CAGR to a 2031 value near 12 Billion USD — though one narrower-scope estimate lands materially lower. The divergence is definitional, not directional.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 3.45 Billion | 2024 | 2030 | 18.9% | Component, solution, application, vertical; hardware-weighted | One published estimate |
| 4.40 Billion | 2025 | 2031 | 18.62% | Component, deployment, channel, vertical; solutions-dominant | A competing analysis |
| 4.28 Billion | 2025 | 2035 | 12.80% | Solution-type and application focus; longer horizon | A third published estimate |
Our analysis suggests the 4.40 Billion / 18.62% view is the most defensible near-term figure: it reconciles the hardware-heavy 2024 base with the rapid shift to cloud software and managed services that the 12.8% long-horizon model understates. The lower CAGR is best read as a maturity-adjusted tail beyond 2031, not a contradiction.
Segmentation splits along five non-geographic axes — component, deployment, application, communication channel and vertical — with cloud deployment and solutions revenue dominating the 2025 base.
| Parent Segment | Children |
|---|---|
| By Component | Hardware, Software, Professional Services, Managed Services |
| By Deployment | On-Premise, Cloud, Hybrid |
| By Application | In-Building, Wide-Area Outdoor, Distributed Recipient / Personal Alerting |
| By Communication Channel | SMS / Cell Broadcast, Voice & VoIP, Email & Desktop Pop-Ups, PA & Siren, Social & Web Feed, IoT Notifications |
| By End-User Vertical | Government & Public Safety, Education, Healthcare, Energy & Utilities, Transportation & Logistics, Industrial, Commercial Enterprise |
So what: the revenue center of gravity has moved from sirens and speakers toward subscription software. Buyers comparing quotes should normalize on five-year total cost, because a cheap hardware bid often carries expensive managed-service renewal.
No single region dominates; demand is distributed, with the Far West and Rocky Mountain regions posting the steepest growth while the Mideast and Southeast carry the largest installed bases on population density and campus concentration.
| Region | Market Share (%) |
|---|---|
| Far West | 0.19% |
| Rocky Mountain | 0.14% |
| Southwest | 0.15% |
| Southeast | 0.16% |
| New England | 0.1% |
| Mideast | 0.12% |
| Plains | 0.08% |
| Great Lakes | 0.06% |
Our analysis suggests regional growth is hazard-driven rather than wealth-driven: the fastest regions are those with recent catastrophic events, which compresses procurement timelines far more than budget cycles do.
Growth is driven primarily by federal mandate expansion and campus-safety enforcement, offset by interoperability gaps and rural fiscal constraints that slow deployment in exactly the jurisdictions most exposed to risk.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| IPAWS-Open 3.0 expansion (~1,800 authorities) | Driver | Strong | Compliance deadlines pull forward agency contracts |
| Clery Act penalties (up to 35,000 USD/violation) | Driver | Strong | Forces integrated campus alert platforms |
| AI/ML in emergency response | Driver | Moderate | Faster triage, multilingual WEA capacity |
| Cloud-native hybrid-work alerts | Driver | Moderate | Extends addressable buyer base to distributed staff |
| NG911 modernization | Driver | Moderate | Pulls PSAPs toward resilient cloud delivery |
| P25 / 5G interoperability gaps | Restraint | Moderate | Raises integration cost and risk in rural jurisdictions |
| Rural municipal budget shortfalls | Restraint | Moderate | Delays replacement of legacy siren estates |
| Alert fatigue and trust erosion | Restraint | Weak | Reduces engagement, weakens outcome measurement |
The balance favors growth decisively. Mandated compliance is non-discretionary spend, which insulates the market from general IT budget softness — a rare quality in enterprise software. The genuine constraint is not demand but implementation capacity in small jurisdictions.
The field is moderately fragmented, with Everbridge and Motorola Solutions leading on scale and federal footprint, and specialists competing on vertical depth or integration.
| Vendor | Position | Differentiation |
|---|---|---|
| Everbridge | Scale leader | Broad critical-event platform; 2024 take-private sharpened enterprise focus |
| Motorola Solutions | Incumbent infrastructure | P25 radio integration and public-safety channel reach |
| OnSolve | Strong challenger | Crisis management and threat intelligence fusion |
| Intrado Life & Safety | Public-sector anchor | Emergency call and notification convergence |
| BlackBerry AtHoc | Federal specialist | FedRAMP High authorization; IPAWS-compatible |
| Alertus Technologies | In-building specialist | Visual and audible redundancy devices in hospitals and campuses |
| Singlewire (InformaCast) | Education/healthcare | Network-native paging and rapid adoption |
| Regroup, Rave, AlertMedia | SME-focused | Cloud-first, low-friction deployment |
Moat analysis: the durable advantages are certification and integration surface, not feature breadth. FedRAMP High, IPAWS compatibility and P25 bridging are slow, expensive assets that lock out smaller entrants. Our analysis suggests consolidation pressure will concentrate on mid-tier vendors lacking federal credentials.
Selection should hinge on four criteria: verified compliance posture, channel redundancy, integration depth with existing radios and identity systems, and total five-year cost including managed services. Procurement risk concentrates in interoperability — a platform that cannot bridge P25 talk groups to broadband push-to-talk will underperform precisely in the wide-area scenarios it was bought for.
Switching costs are high and rising. Once alert templates, contact hierarchies and incident workflows are embedded across a campus or agency, migration costs rival re-implementation. Buyers should therefore negotiate data-portability and export clauses at signature, not renewal. Regulatory exposure is asymmetric: Clery Act penalties and 72-hour CISA incident reporting make inadequate notification a compliance liability rather than merely an operational gap. Operators should also instrument alert engagement data to counter fatigue, since unmeasured delivery cannot demonstrate duty of care.
The balance of evidence favors accelerated near-term spend moderated by a slower long-run tail. Mandate-driven procurement through 2028 will likely outrun the 18.6% consensus, then decelerate toward the 12–13% range as replacement cycles normalize. The strongest counter-argument is that rural budget shortfalls and P25/5G gaps could cap adoption in exactly the highest-hazard jurisdictions — a real risk, but one that shifts spending toward hosted and shared-service models rather than eliminating it.
Our analysis further suggests margin will migrate decisively from hardware to services and integration. Hardware is being commoditized by cloud architectures even as specialized devices retain niche indispensability. Vendors pricing on box sales will face compression; those bundling compliance consulting, AI configuration and 24/7 monitoring will defend pricing power.
Actionable strategy for operators and investors:
What would change our conclusion: a material slip in IPAWS-Open 3.0 funding, or evidence that Clery enforcement softens, would pull the forecast toward the lower 12.8% path. Conversely, sustained AI-triage adoption above 40% of PSAPs would justify an upward revision.
This study applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the notification value chain with emergency-management platform vendors, hardware OEMs (sirens, beacons, PA systems), cloud infrastructure and integration partners, and public-safety communications dealers. Decision-maker designations interviewed include Chief Information Security Officers, Directors of Emergency Management, Procurement and Contracting Leads, and Public Safety Communications Directors.
Findings were benchmarked against FEMA IPAWS program documentation, FCC Emergency Alert System rules, Department of Education Clery Act guidance, CISA interoperability publications, US Census and BLS employment data, and corporate filings including 10-K and SEC disclosures from listed vendors.
Top-down macroeconomic and vertical allocation modeling was run simultaneously with bottom-up modeling of vendor revenue, installed alerting-authority counts and per-seat subscription pricing, then reconciled against procurement award data.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up vendor revenue & subscription triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Hazard exposure, procurement award flows & population density | High |
| Competitive Landscape | Leading market players | Annual reports, certification registries & contract filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 18.62% from 2020-2034 |
| Segmentation |
|
The market was valued at approximately 4.40 Billion USD in 2025 and is projected to reach roughly 12.27 Billion USD by 2031, growing at a compound annual rate near 18.6% over the forecast period.
Healthcare and life sciences is the fastest-growing vertical at roughly 21.08% CAGR, driven by HIPAA-compliant hybrid architectures. Among components, professional and managed services grow fastest at about 18.95% CAGR.
Estimates differ mainly on scope definition. Broader studies include hardware infrastructure and services, producing larger bases and higher growth rates; narrower solution-focused studies exclude hardware replacement and report slower long-horizon growth near 12.8%.
FEMA IPAWS-Open 3.0 authorization requirements, FCC IP-based Emergency Alert System rules, Department of Education Clery Act penalties, and CISA 72-hour cyber-incident reporting obligations all compel organizations to maintain compliant notification capabilities.
Everbridge and Motorola Solutions lead on scale, alongside OnSolve, Intrado Life & Safety and BlackBerry AtHoc. Specialists including Alertus, Singlewire, Regroup, Rave and AlertMedia compete on vertical depth and cloud-first deployment.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the notification value chain with emergency-management platform vendors, hardware OEMs (sirens, beacons, PA systems), cloud infrastructure and integration partners, and public-safety communications dealers. Decision-maker designations interviewed include Chief Information Security Officers, Directors of Emergency Management, Procurement and Contracting Leads, and Public Safety Communications Directors.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Emergency Management Directors | 35% |
| CISO & IT Security Leads | 30% |
| Procurement & Contracting Leads | 20% |
| Public Safety Communications Directors | 15% |
| Company Type | Representation (%) |
|---|---|
| Alerting Platform & Software Vendors | 40% |
| Hardware OEMs (Sirens, Beacons, PA) | 30% |
| Cloud & Integration Partners | 18% |
| Public-Safety Dealers & Distributors | 12% |
Findings were benchmarked against FEMA IPAWS program documentation, FCC Emergency Alert System rules, Department of Education Clery Act guidance, CISA interoperability publications, US Census and BLS employment data, and corporate filings including 10-K and SEC disclosures from listed vendors.
Top-down macroeconomic and vertical allocation modeling was run simultaneously with bottom-up modeling of vendor revenue, installed alerting-authority counts and per-seat subscription pricing, then reconciled against procurement award data.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up vendor revenue & subscription triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Hazard exposure, procurement award flows & population density | High |
| Competitive Landscape | Leading market players | Annual reports, certification registries & contract filings | High |