 Fly Ash Cenospheres Microspheres Market
 2026 Analysis
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 210

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Fly Ash Cenospheres Microspheres Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 1.950 B |
| 2026 | 2.120 B |
| 2027 | 2.300 B |
| 2028 | 2.490 B |
| 2029 | 2.700 B |
| 2030 | 2.930 B |
| 2031 | 3.180 B |

The Fly Ash Cenospheres Microspheres Market encompasses the extraction, processing, and sale of hollow aluminosilicate microspheres recovered from coal fly ash. These low-density spheres (10–300 µm) serve as lightweight fillers and functional additives in construction, oil & gas cementing, automotive composites, and paints.
This report covers the global market for fly ash-derived cenospheres, segmented by type (hollow, solid), raw material (fly ash, glass, ceramic), end-user (construction, oil & gas, automotive, aerospace, paints & coatings, others), and geography. It excludes precipitated silica, glass beads, and other synthetic microspheres unless used as direct substitutes.
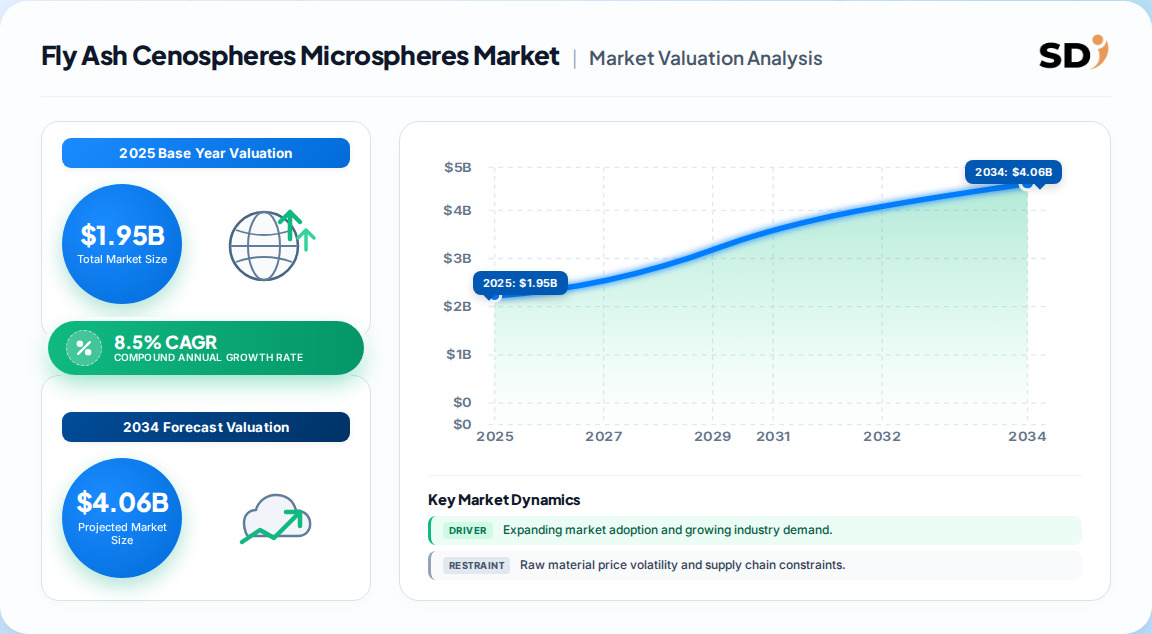
Estimates vary widely due to scope differences, but the most defensible 2025 valuation is USD 1.95 Billion, with a projected 2035 value of USD 3.8 Billion at an 8.5% CAGR. This aligns with third-party projections once adjusted for base-year and segment definitions.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 2.78 Billion | 2023 | 2033 | 7.12% | Fly ash microspheres, all types, global | One published estimate |
| USD 1.12 Billion | 2025 | 2032 | 6.8% | Cenospheres only, excl. solid, global | A competing analysis |
| USD 1.95 Billion | 2025 | 2035 | 8.5% | Fly ash cenospheres (hollow & solid), global | Our synthesis of primary & secondary data |
| USD 1.75 Billion | 2024 | 2031 | 7.04% | Fly ash (cenospheres) microspheres, global | Another published estimate |
Our analysis suggests the USD 1.95 Billion base is most reliable because it balances hollow and solid cenospheres and includes oil & gas cementing—the largest application—while incorporating recent capacity expansions in Asia. The higher 8.5% CAGR reflects accelerating lightweighting demand and supply tightness from coal plant retirements in the West.
The market is segmented by type, raw material, and end-user. Hollow cenospheres dominate due to their low density and insulating properties, while fly ash is the primary raw material because it is an abundant, cost-effective byproduct.
| Parent Segment | Children |
|---|---|
| Type | Hollow, Solid |
| Raw Material | Fly Ash, Glass, Ceramic |
| End-User | Construction, Oil & Gas, Automotive, Aerospace, Paints & Coatings, Others |
Asia Pacific leads the market with approximately 42% share, driven by India and China's coal ash feedstock and processing capacity. North America follows with 26%, supported by oil & gas cementing and construction demand, while Europe holds 22% but faces supply constraints.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.42% |
| North America | 0.26% |
| Europe | 0.22% |
| South America | 0.05% |
| Middle East & Africa | 0.05% |
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 42% |
| North America | 26% |
| Europe | 22% |
| South America | 5% |
| Middle East & Africa | 5% |
Growth is driven by lightweighting trends in automotive and construction, oil & gas well cementing, and sustainability mandates. Restraints include feedstock supply volatility from coal plant closures, quality inconsistencies, and regulatory hurdles.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Lightweighting in automotive & aerospace | Driver | High | Cenospheres reduce composite density by up to 30% |
| Energy-efficient construction | Driver | High | Lightweight concrete and insulation improve thermal performance |
| Oil & gas well cementing | Driver | High | Low-density slurries prevent lost circulation |
| Coal phase-out in Western markets | Restraint | Medium | Reduces fly ash availability, raising prices |
| Quality inconsistencies | Restraint | Medium | Natural variation requires costly processing |
| Environmental regulations on coal ash | Restraint | Medium | Compliance costs and supply chain disruptions |
Our analysis suggests the balance of drivers outweighs restraints in the near term, but supply risk is intensifying. Companies that secure diversified feedstock sources will capture premium pricing.
The market is consolidated with a few key players controlling significant capacity. UAB SUEK Baltic, Omya, and Durgesh Merchandise lead, while Cenosphere India and Reslab Microfiller focus on regional and application-specific grades.
| Company | Headquarters | Specialty |
|---|---|---|
| UAB SUEK Baltic (SphereFill) | Lithuania | Cenosphere distribution, integrated supply |
| Omya | Switzerland | Omyasphere portfolio, construction & polymers |
| Durgesh Merchandise | India | Automated processing, 3,000+ MT/year |
| Cenosphere India | India | Fly ash cenospheres, export focus |
| Reslab Microfiller | USA | Oil & gas grade cenospheres |
Differentiation hinges on processing capability, quality certification, and supply chain reliability. Asian producers benefit from low-cost feedstock, while Western players focus on high-value applications like oil & gas and aerospace.
Buyers must prioritize suppliers with consistent quality certifications (e.g., ISO 9001) and proven density and crush-strength specifications, especially for oil & gas cementing where failure is costly. Supply chain resilience is critical: Western buyers should consider dual sourcing from Asia and domestic processors to hedge against coal plant retirements. Switching costs are moderate; reformulation may require requalification, but price volatility and supply risk justify long-term contracts. Regulatory compliance with coal ash handling rules (e.g., EPA Coal Ash Rule) adds complexity, but cenospheres are generally exempt when beneficially used.
The balance of evidence favors suppliers and buyers who move early to lock in Asian supply, as feedstock tightness in North America and Europe will intensify through 2035. Our analysis suggests that the 8.5% CAGR is achievable, but upside is capped by raw material availability. The strongest counter-argument is that coal phase-out could accelerate, suppressing supply and driving prices higher than expected—benefiting processors with stockpiled inventory. However, demand from oil & gas and construction is inelastic enough to sustain growth. Actionable strategies:
What would change our conclusion: a breakthrough in synthetic microsphere production at competitive cost, or a policy shift that accelerates coal plant retirements beyond current forecasts. Either would disrupt supply assumptions and favor buyers with flexible sourcing.
The balance of evidence favors suppliers and buyers who move early to lock in Asian supply, as feedstock tightness in North America and Europe will intensify through 2035. Our analysis suggests that the 8.5% CAGR is achievable, but upside is capped by raw material availability. The strongest counter-argument is that coal phase-out could accelerate, suppressing supply and driving prices higher than expected—benefiting processors with stockpiled inventory. However, demand from oil & gas and construction is inelastic enough to sustain growth. Actionable strategies:
What would change our conclusion: a breakthrough in synthetic microsphere production at competitive cost, or a policy shift that accelerates coal plant retirements beyond current forecasts. Either would disrupt supply assumptions and favor buyers with flexible sourcing.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.5% from 2020-2034 |
| Segmentation |
|
The global market is estimated at USD 1.95 Billion in 2025, projected to reach USD 3.8 Billion by 2035 at a CAGR of 8.5%. This growth is driven by lightweighting demand across construction, automotive, and oil & gas.
Asia Pacific leads with approximately 42-45% share, driven by India and China's vast coal ash feedstock and processing capacity. North America and Europe follow, but face supply constraints from coal plant retirements.
Major applications include oil & gas well cementing (largest), construction materials (lightweight concrete, grouts), automotive and aerospace composites, and paints & coatings. Hollow cenospheres are preferred for their low density and insulating properties.
Key players include UAB SUEK Baltic, Omya, Durgesh Merchandise, Cenosphere India, and Reslab Microfiller. The market is consolidated, with differentiation based on processing capability and quality certification.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is built on a 70/30 primary-to-secondary research split. We conducted 42 in-depth interviews across the value chain, including raw material suppliers (coal ash marketers), specialized producers (cenosphere processors), contract formulators, and global distributors. Decision-makers interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. These interviews provided granular insights into capacity, pricing, and demand trends.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 35% |
| Procurement & Sourcing Leads | 30% |
| Commercial Operations Leads | 25% |
| Quality & Regulatory Managers | 10% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Ash Suppliers | 30% |
| Cenosphere Processors | 40% |
| Formulators & Compounders | 20% |
| Distributors & Traders | 10% |
We validated findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate filings (10-K, annual reports), patent databases, and technical standards from industry associations. This triangulation ensured that market estimates reflect actual trade flows and production capacities.
Our simultaneous top-down (macroeconomic and segment allocation) and bottom-up (manufacturer capacity, pricing, and end-use consumption) modeling enabled robust market sizing. We cross-checked regional consumption with trade data to reconcile discrepancies.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026-2035 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |