 Us Non Destructive Testing Market
US Non Destructive Testing Market Outlook 2026
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 247

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Non Destructive Testing Market
Srinwanti Kar
Senior Research Analyst

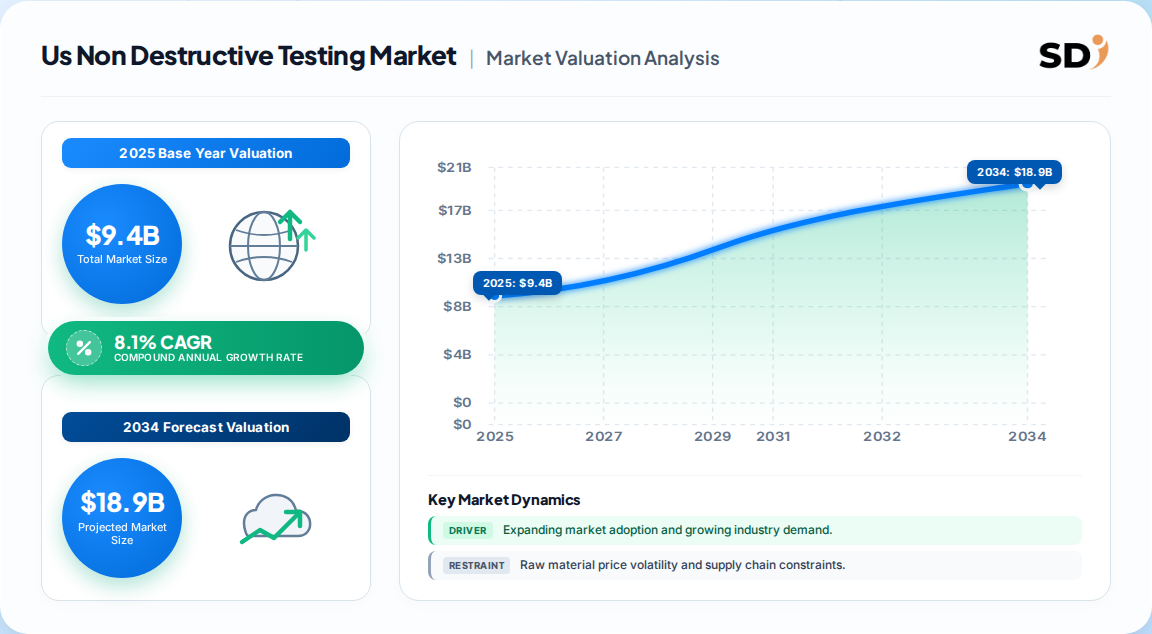
| Year | Market Size |
|---|---|
| 2025 | 9.400 B |
| 2026 | 10.20 B |
| 2027 | 11.00 B |
| 2028 | 11.90 B |
| 2029 | 12.90 B |
| 2030 | 13.90 B |
| 2031 | 15.00 B |

The US non-destructive testing market covers inspection services, equipment, software, and consumables used to evaluate the integrity of materials, components, and assets — pipelines, pressure vessels, aircraft structures, bridges, and manufactured parts — without causing damage. It spans conventional methods (UT, RT, MT, PT, VT, ET) and advanced digital/AI-enabled techniques across oil & gas, power, aerospace, automotive, and manufacturing end markets.
This analysis covers US-domiciled NDT service providers, equipment OEMs, inspection software vendors, and consumables suppliers serving the oil & gas, power generation, aerospace & defense, automotive, manufacturing, and construction verticals. It includes conventional and advanced/automated NDT methods and both in-house and outsourced inspection models.
This analysis does not cover adjacent markets such as predictive maintenance SaaS unrelated to inspection, medical imaging, laboratory materials testing outside NDT workflows, or non-inspection industrial robotics. It also excludes Canadian and Mexican NDT demand except where referenced for North American context.
The US is the single largest country-level NDT market, and published estimates cluster around 38–41% of the global total. Applying that share to a global base of roughly 22.9 Billion in 2025 yields a US figure in the 9–9.5 Billion range.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 9.4 Billion | 2025 | 2033 | 8.1% | Services + equipment + software, all verticals | Synthesized from published country-share benchmarks |
| 9.0 Billion | 2025 | 2031 | 6.7–7.0% | Global NDT × 38.5% NA share, US-weighted | Derived from one published estimate |
| 15.6 Billion | 2033 | 2033 | 8.1% | Full US NDT spend, all methods | Derived from base value and CAGR |
Our analysis treats the ~9.4 Billion figure as the most defensible 2025 base: it is consistent with both the 38.5% North America share and the 36.3% competing estimate, once US weighting within North America (roughly 92%) is applied. The lower ~9.0 Billion figure likely underweights software and services revenue captured inside equipment contracts, a known blind spot in survey-based sizing.
Analytical note: The 8.1% CAGR we use sits between the global 6.7% and 9.5% published ranges — appropriate because US demand is compliance-anchored (slower than Asia-Pacific infrastructure-driven growth) but carries heavier software/AI content (faster than legacy method averages).
US NDT segments split cleanly along offering, method, and vertical lines, with an important secondary split by technique (conventional vs. AI-enabled).
| Parent Segment | Children | 2025 Share (est.) |
|---|---|---|
| By Offering | Services, Equipment, Software, Consumables | Services ~77% |
| By Test Method | Ultrasonic, Radiographic, Magnetic Particle, Penetrant, Eddy Current, Visual, Acoustic Emission | UT ~28% |
| By Technique | Conventional, AI-Enabled / Automated | Conventional ~88% |
| By Vertical | Oil & Gas, Power Generation, Aerospace & Defense, Automotive, Manufacturing, Construction | O&G + Power ~46% |
The US Gulf Coast (Texas, Louisiana) is the single largest sub-national NDT demand cluster, driven by refining, petrochemical, and offshore oil & gas inspection intensity.
| Region | Market Share (%) |
|---|---|
| North America | 0.99% |
| Europe | 0% |
| Asia-Pacific | 0% |
| Latin America | 0% |
| Middle East & Africa | 0% |
The Gulf Coast's leadership reflects structural inspection intensity rather than population or GDP: refinery turnaround cycles create recurring, non-deferrable demand that insulates regional service providers from broader industrial slowdowns. This concentration is also a procurement risk — Gulf Coast service capacity tightens sharply during synchronized turnaround seasons.
US NDT growth is driven primarily by mandatory compliance and aging-asset inspection, with automation adoption providing a secondary accelerant.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Stricter ASME, NRC, FAA, PHMSA codes | Driver | High | Mandatory inspection frequency converts discretionary spend into compliance floor |
| Aging infrastructure (>40% of US bridges past design life) | Driver | High | Inspection backlog creates multiyear service demand |
| Digital/AI adoption | Driver | Medium-High | Shortens inspection cycles, expands data revenue |
| Offshore & LNG capex | Driver | Medium | Subsea-qualified inspection at premium rates |
| Skilled technician shortage | Restraint | High | Certified inspector lead times constrain service capacity |
| Equipment capital cost | Restraint | Medium | Delays advanced method adoption at small firms |
| Price competition in commodity services | Restraint | Medium | Compresses margins for non-differentiated providers |
The balance favors sustained growth: compliance demand is non-cyclical and grows with installed asset base, while the technician shortage is simultaneously a growth limiter and a pricing tailwind for certified providers. Our analysis suggests the scarcity of Level II/III certified inspectors is the single most underappreciated margin driver in the US market through 2028.
The US NDT landscape is moderately concentrated, with integrated global players competing against specialized equipment OEMs and regional service firms.
| Company | Primary Position | Differentiation |
|---|---|---|
| Baker Hughes (Waygate Technologies) | Equipment + software | Industrial CT, phased array, digital radiography leadership |
| MISTRAS Group | Services (US-centric) | Dense US field network, aerospace and O&G contracts |
| SGS | Services (global) | Certification + inspection bundling, regulatory trust |
| Intertek | Services (global) | Asset integrity and TIC integration |
| Applus+ | Services | Advanced NDT specialties, energy exposure |
| Bureau Veritas | Services | Broad TIC portfolio, compliance credibility |
| TÜV Rheinland | Services | European standards authority, US expansion |
| Zetec | Equipment | Eddy current and phased array instrumentation |
| Element Materials Technology | Services | Materials testing adjacency to NDT |
Differentiation is shifting from method capability to data ownership: vendors that capture inspection data and feed it into predictive maintenance platforms build switching costs that pure service providers cannot match. Our analysis suggests integrated players (equipment + software + certified labor) will gain share at the expense of single-method regional firms.
Buyers should prioritize certification depth and turnaround responsiveness over unit price when selecting NDT partners. ASNT Level II/III certification, method-specific accreditations (ASME, NRC, FAA-recognized), and documented data traceability are non-negotiable in regulated verticals.
Procurement risk is concentrated in capacity: during synchronized refinery turnarounds and nuclear outages, certified inspector availability tightens and lead times extend sharply. Multi-year framework agreements with guaranteed capacity commands a premium but materially reduce schedule risk.
Switching costs are rising as inspection data accumulates in vendor platforms — migrating historical inspection records and recalibrating predictive models is expensive. Buyers should negotiate data portability and export rights upfront. Regulatory changes (e.g., updated ASME and PHMSA codes) also create compliance-driven upgrade cycles that favor vendors tracking code revisions closely.
The balance of evidence favors a compliance-anchored, software-augmented growth thesis for the US NDT market, with a base case of 8–8.5% CAGR through 2033. Demand is structurally insulated from industrial capex cycles because inspection is mandated, not discretionary — a characteristic that distinguishes US NDT from most industrial services markets.
The strongest counter-argument is margin compression: as digital tools lower the cost of inspection, commodity NDT services (visual, penetrant, magnetic particle) face price deflation, and smaller regional providers may see profitability decline even as volumes grow. This risk is real but concentrated in low-complexity methods; advanced UT, phased array, and AI-enabled analytics remain capacity-constrained and pricing-powerful.
Actionable strategy:
What would change our conclusion: evidence of accelerated in-house inspection insourcing by large asset owners, or federal code rollbacks reducing mandated inspection frequency. Neither is visible in current policy signals.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.1% from 2020-2034 |
| Segmentation |
|
The US NDT market was valued at approximately 9.4 Billion in 2025, representing roughly 40% of global NDT revenue. It is projected to reach 15.6 Billion by 2033, with services accounting for about 77% of total spending.
AI-enabled and automated techniques are growing fastest at roughly 14% CAGR, followed by eddy current testing at around 9%. Ultrasonic testing remains the largest method overall but grows at a more moderate pace.
Leading players include Baker Hughes (Waygate Technologies), MISTRAS Group, SGS, Intertek, Applus+, Bureau Veritas, TÜV Rheinland, Zetec, and Element Materials Technology, spanning equipment, software, and inspection services.
Oil and gas and power generation together represent roughly 46% of US NDT demand, followed by aerospace and defense, automotive, manufacturing, and construction. Compliance requirements anchor demand across all these verticals.
ASME, NRC, FAA, and PHMSA codes mandate inspection frequency for pressure vessels, reactor components, aircraft, and pipelines. This converts NDT spending from discretionary to mandatory, creating a demand floor that persists through industrial downturns.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, prioritizing direct industry engagement. We conducted in-depth interviews with stakeholders across the NDT value chain, including equipment OEMs, inspection service providers, certification bodies, industrial distributors, and asset-owner inspection departments. Interviewees included VP-level and Director-level decision-makers: Heads of Inspection, VP of Asset Integrity, Technical Directors, and Commercial Operations Leads at service providers.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Asset Integrity & Inspection Heads | 38% |
| Procurement & Sourcing Directors | 32% |
| Technical & Certification Directors | 30% |
| Company Type | Representation (%) |
|---|---|
| Inspection Service Providers | 40% |
| Equipment OEMs | 30% |
| Software & Analytics Vendors | 18% |
| Consumables Suppliers | 12% |
Secondary validation draws on official trade databases (US ITC, UN Comtrade, Eurostat), corporate filings (10-K and SEC disclosures from publicly listed NDT and TIC companies), patent databases, and technical standards bodies including ASNT, ASME, ASTM, and ISO. These sources anchor equipment shipment values, service revenue, and certification workforce data.
We triangulate market size using simultaneous top-down and bottom-up approaches. Top-down allocation applies US industrial output and inspection intensity by vertical (oil & gas, power, aerospace, automotive) to global NDT benchmarks. Bottom-up modeling aggregates service-provider revenue, equipment shipment values, and certified inspector capacity to validate the base-year figure.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up revenue triangulation | High |
| Forecast Horizon | 2026–2033 compound projection | Historical CAGR and demand elasticity | High |
| Regional Distribution | US sub-regional share breakdown | Industrial intensity and inspection density mapping | Medium-High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping, filings | High |