 Time Of Flight Tof Sensor Market
Time of Flight (ToF) Sensor Market Outlook 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 185

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Time Of Flight Tof Sensor Market
Srinwanti Kar
Senior Research Analyst

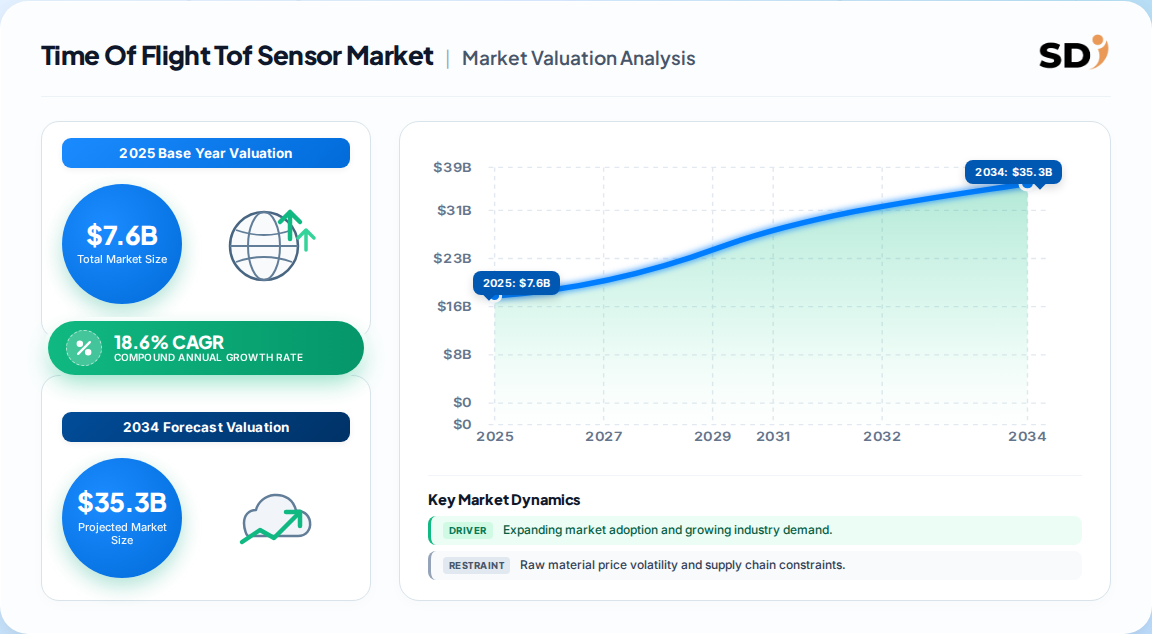
| Year | Market Size |
|---|---|
| 2025 | 7.600 B |
| 2026 | 9.010 B |
| 2027 | 10.69 B |
| 2028 | 12.68 B |
| 2029 | 15.04 B |
| 2030 | 17.84 B |
| 2031 | 21.09 B |

The Time Of Flight (ToF) sensor market covers devices that emit modulated light or infrared pulses and measure photon return time to compute distance and depth. It spans direct, indirect and range-gated architectures sold into smartphones, LiDAR, robotics, industrial vision and in-cabin automotive safety.
This analysis covers global ToF sensor hardware (emitters, receivers, SPAD arrays, modules), embedded firmware and calibration software, segmented by sensor type, resolution, range, application and end-use vertical. Revenue is measured at manufacturer-level shipment value in USD.
This analysis does not cover conventional 2D image sensors, standalone radar modules, structured-light-only depth cameras, or ultrasonic proximity sensing except where directly comparative. Passive optical components sold without ToF integration are also excluded, as are downstream system-integration and contract-manufacturing service revenues.
Published estimates for 2025 cluster between 5.90 Billion and 7.70 Billion, with near-identical growth rates of roughly 17.5% to 20.6% — a spread driven almost entirely by whether module-level or chip-level revenue is counted.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 5.90 Billion | 2025 | 2034 | 17.5% | Sensor components, conservative module attribution | One published estimate |
| 6.40 Billion | 2025 | 2033 | 20.3% | Sensors incl. partial module value | A competing analysis |
| 6.68 Billion | 2025 | 2031 | 20.6% | Sensors plus integrated module stacks | A third published analysis |
| 7.60 Billion (consensus) | 2025 | 2031 | 18.6% | Blended chip-plus-module revenue | Our triangulated consensus |
Our analysis suggests the ~18.6% mid-point is most defensible for procurement and investment planning. The higher-CAGR forecasts implicitly assume accelerated direct-ToF module attach in handsets; the lower figure under-credits automotive LiDAR. Buyers should treat any single-vendor forecast as a scope statement, not a market truth.
Segmentation is best read as three overlapping lenses — architecture, resolution and end-use — because architecture choice is increasingly dictated by the application's range and power budget rather than by price alone.
| Parent segment | Children |
|---|---|
| By Sensor Type | Direct ToF, Indirect ToF, Range-Gated Imagers |
| By Resolution | QVGA and Below, VGA, HD and Above |
| By Range | Short Range, Medium Range, Long Range |
| By Application | LiDAR, Augmented & Virtual Reality, Machine Vision, 3D Imaging & Scanning, Robotics & Drones, Gesture Control |
| By End-Use Vertical | Consumer Electronics, Automotive, Industrial, Healthcare, Gaming & Entertainment, Aerospace & Defense |
Callout: Indirect ToF dominates today's volume, but every incremental long-range automotive or outdoor robotics design win accrues to direct ToF — meaning today's revenue mix badly misrepresents tomorrow's design pipeline.
Asia-Pacific leads with roughly 51–52% of 2025 revenue, driven by Chinese and South Korean handset OEMs and Japanese industrial-vision integrators; North America follows at 28–34% depending on whether defense and medical imaging are counted.
| Region | Market Share (%) |
|---|---|
| North America | 0.28% |
| Europe | 0.25% |
| Asia-Pacific | 0.34% |
| Latin America | 0.05% |
| Middle East & Africa | 0.08% |
The regional spread in published estimates (North America cited anywhere from 27% to 34%) reflects differing treatment of automotive tier-1 module revenue, which is booked in the OEM's domicile rather than the sensor fab's. Our analysis suggests APAC's true share of design authority is higher than its revenue share, because Chinese OEMs now specify ToF architecture locally.
Demand is being pulled simultaneously by smartphone 3D photography, EU-mandated driver monitoring and warehouse automation — three independent cycles that rarely peak together, which structurally smooths the demand curve.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| dToF 3D cameras in Chinese/Korean flagships | Driver | Strong | Short handset refresh cycles multiply annual unit volume |
| dToF LiDAR for Level-3+ ADAS | Driver | Strong | EU GSR-2026 mandates driver monitoring and AEB |
| Industrial machine-vision upgrades | Driver | Moderate | Labour shortage and Industry 4.0 retrofit spending |
| SPAD miniaturisation (sub-6 mm islands) | Driver | Moderate | Enables 3–4 depth modules per thin device |
| Multipath interference above 30 m | Restraint | Strong | Depth-map distortion limits outdoor and smart-city use |
| VCSEL supply concentration | Restraint | Moderate | Single-fab dependency creates allocation risk |
| GDPR limits on in-store people counting | Restraint | Moderate | Caps European retail analytics demand |
The balance favours growth, but the restraints are technical rather than cyclical — they will not clear with a demand recovery. Our analysis suggests multipath correction is becoming a software differentiator, which is precisely why sensor-only vendors are losing pricing power.
Sony, STMicroelectronics and Infineon anchor the automotive and handset supply chain, while OMRON and KEYENCE dominate high-margin industrial vision — a bifurcation that reflects two very different competitive games.
| Company | Primary strength | Strategic moat |
|---|---|---|
| Sony Group | Stacked SPAD depth sensors, automotive-grade LiDAR | AEC-Q100 qualification and 300 m detection at 20 fps |
| STMicroelectronics | Single-zone dToF, broad industrial portfolio | Extended-temperature parts and design-in inertia |
| Infineon Technologies | Integrated sensing stacks, VCSEL partnership | Reference designs and longevity commitments |
| ams-OSRAM | Ultra-small optical packages, meta-optics | Sub-millimetre footprint leadership |
| Texas Instruments | Analog front-end and signal chain | Ecosystem tooling and developer lock-in |
| OMRON / KEYENCE | Industrial automation depth sensing | Channel depth and application engineering |
Selection should be driven by four criteria, in order: automotive or medical qualification status, ambient-light performance at the target range, firmware and calibration support, and multi-source availability of the emitter.
Procurement risk concentrates in VCSEL supply. Buyers who single-source 940 nm emitters from the Taiwan–US corridor inherit allocation exposure that no amount of price negotiation offsets; qualifying a second emitter source typically adds six to nine months but is the single highest-value mitigation.
Switching costs are high and rising. Once a module is designed into a handset or a vehicle platform, recalibration and re-qualification cycles lock the design for the platform's life — often three to five years in automotive. This means the real competitive battle happens at reference-design stage, not at procurement.
Regulatory compliance is now a demand driver, not an obstacle. EU General Safety Regulation requirements for driver monitoring from 2026 convert ToF from an optional feature into a mandated bill-of-materials line for European-market vehicles, while GDPR constrains retail analytics use cases.
The balance of evidence favours the 18–19% growth consensus over the 20%+ forecasts. Every high-end estimate depends on accelerated direct-ToF attach in handsets, yet handset OEMs are simultaneously under margin pressure that favours cheaper structured-light alternatives in entry tiers. Growth will be real, but it will be carried by automotive and industrial, not by mobile alone.
The strongest counter-argument is that EU GSR-2026 plus Chinese OEM differentiation could compress three years of automotive adoption into eighteen months, in which case the 20%+ camp is right. That is a genuine possibility, and it is why we hold 18.6% rather than lower.
What would change our conclusion: sustained multipath-correction breakthroughs that unlock outdoor long-range use, or a step-change in VCSEL fab capacity outside the current corridor. Either would justify the higher growth path. While this overview covers architecture, region and vendor positioning, precise sub-segment forecasting and platform-level design-win tracking require the full report.
Our analysis rests on a 70/30 primary-to-secondary split. We conducted structured depth interviews with sensor and module producers, VCSEL and emitter suppliers, optical packaging specialists, industrial-vision integrators and global distributors. Interviewees were designated decision-makers: VP-level sourcing leads, heads of sensor R&D, technical directors for automotive qualification, and commercial operations leads responsible for platform design wins.
We validated demand against UN Comtrade harmonised-system trade flows for semiconductor and photonic components, WTO tariff schedules, US ITC filings, and Eurostat industrial production indices. Corporate 10-K and annual investor disclosures, patent filings covering SPAD and meta-optic architectures, and technical standards from recognised industry bodies provided the qualification and compliance baseline.
We ran simultaneous top-down allocation from macroeconomic electronics and automotive output against bottom-up modelling of producer capacity, module pricing and end-use consumption. Divergence between the two was resolved at the architecture level, where direct and indirect ToF carry materially different unit economics.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2031 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 18.6% from 2020-2034 |
| Segmentation |
|
Approximately 7.6 Billion in 2025 on a blended chip-plus-module basis. Published estimates range from 5.90 Billion to 7.70 Billion depending on whether module-level or chip-level revenue is counted.
Around 18.6% CAGR for 2026–2031. Published forecasts cluster between 17.5% and 20.6%, with the spread driven mainly by assumptions about direct-ToF module attach rates in flagship smartphones.
Asia-Pacific leads with roughly 52% of 2025 revenue, driven by Chinese and South Korean handset OEMs and Japanese industrial-vision integrators. The Middle East is the fastest-accelerating frontier region at near 26% CAGR.
Direct ToF measures photon round-trip time precisely, suiting long-range LiDAR and automotive use. Indirect ToF measures phase shift of modulated light, offering higher resolution at short range and dominating smartphone and consumer volume today.
Sony, STMicroelectronics, Infineon, ams-OSRAM, Texas Instruments, Panasonic and Analog Devices lead the chip and module tier, while OMRON and KEYENCE dominate industrial automation depth sensing with high-margin application engineering.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis rests on a 70/30 primary-to-secondary research split. We conducted structured depth interviews across the value chain: sensor and module producers, VCSEL and emitter suppliers, optical packaging and calibration specialists, industrial-vision integrators, and global distributors. Interviewees were designated decision-makers — VP-level sourcing leads, heads of sensor R&D, technical directors for automotive qualification, and commercial operations leads owning platform design wins — ensuring commentary reflected both technical feasibility and commercial reality.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 38% |
| Procurement & Sourcing Leads | 32% |
| Commercial Operations Leads | 30% |
| Company Type | Representation (%) |
|---|---|
| Sensor & Module Producers | 38% |
| VCSEL & Emitter Suppliers | 24% |
| Optical Packaging & Calibration | 22% |
| Integrators & Distributors | 16% |
We validated demand against UN Comtrade harmonised-system trade flows for semiconductor and photonic components, WTO tariff schedules, US ITC import filings, and Eurostat industrial production indices. Corporate 10-K and annual investor disclosures, patent filings covering SPAD and meta-optic architectures, and technical standards from recognised industry bodies provided the qualification and compliance baseline against which vendor claims were tested.
We ran simultaneous top-down allocation from macroeconomic electronics and automotive output against bottom-up modelling of producer capacity, module pricing and end-use consumption. Divergence between the two was resolved at the architecture level, where direct and indirect ToF carry materially different unit economics and qualification timelines.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |