 Vehicle Access Control Market
 Size, Share & Growth 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 227

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Vehicle Access Control Market
Sadashiv Parab
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 16.82 B |
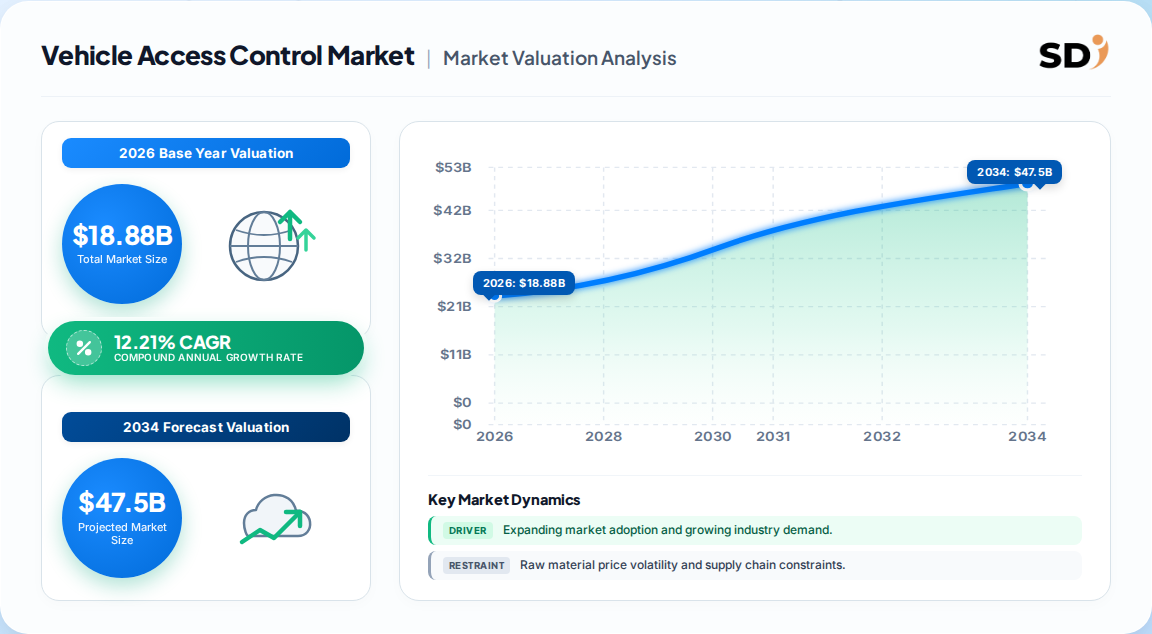
| 2026 | 18.88 B |
| 2027 | 21.18 B |
| 2028 | 23.77 B |
| 2029 | 26.67 B |
| 2030 | 29.93 B |
| 2031 | 33.56 B |

The vehicle access control market covers electronic systems that authenticate and authorize vehicle entry and ignition without a mechanical key. It spans passive and remote keyless entry, biometric authentication, RFID, NFC, Bluetooth, and UWB technologies, sold through OEM fitment and aftermarket channels across passenger and commercial vehicles.
This report covers system type (biometric and non-biometric), technology (RFID, Bluetooth, NFC, UWB, and others), vehicle type (passenger cars and commercial vehicles), end user (OEM-installed and fleet/shared-mobility operators), sales channel (direct-to-OEM, aftermarket, and e-commerce), and geography across five regions. It analyzes market sizing, segmentation, drivers, restraints, vendor positioning, and procurement dynamics for the 2025–2031 horizon.
This analysis does not cover adjacent markets such as mechanical lock and key assemblies, standalone parking management systems, toll-collection hardware, or in-vehicle infotainment and telematics beyond their access-control integration interfaces. Vehicle cybersecurity software sold independently of access hardware is also excluded.
The market is sized at USD 18.88 billion in 2026, growing at 12.21% CAGR to USD 33.56 billion by 2031, according to the most comprehensive published estimate. A second benchmark places 2026 at USD 19.2 billion and 2030 at USD 30.0 billion at 11.7% CAGR, confirming scale within a 2% band.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 18.88 billion | 2026 | 2031 | 12.21% | Full vehicle access control, OEM + aftermarket, biometric + non-biometric | One published estimate |
| USD 19.2 billion | 2026 | 2030 | 11.7% | Vehicle access control by technology and application, global | A competing analysis |
| USD 15.5 billion | 2024 | 2030 | 11.7% | Vehicle access control, technology and application segmentation | A competing analysis |
Our analysis suggests the USD 18.88 billion 2026 base is the most defensible because it sits between the 2024 and 2026 benchmarks from other sources and its 12.21% CAGR is corroborated by the ~11.7% figure from the competing analysis. The divergence in CAGR—about 50 basis points—likely reflects differing treatment of aftermarket retrofits and UWB premium content. Buyers should treat USD 18–19 billion as the reliable 2026 planning range.
The market is segmented by system type, technology, vehicle type, end user, and sales channel. Non-biometric systems dominate volume, but biometric and UWB are the fastest-growing sub-segments, reshaping the revenue mix toward premium authentication.
| Parent segment | Children | 2025 share / growth signal |
|---|---|---|
| System type | Biometric, Non-biometric | Non-biometric 67.62% share; biometric 13.63% CAGR |
| Technology | RFID, Bluetooth, NFC, UWB, Others | RFID 44.95% share; UWB 18.05% CAGR |
| Vehicle type | Passenger cars, Commercial vehicles | Passenger cars 63.74% share; fleet/shared mobility 13.98% CAGR |
| End user | OEM-installed, Fleet & shared-mobility operators | OEM 70.78% share; fleet operators 15.29% CAGR |
| Sales channel | Direct-to-OEM, Aftermarket, E-commerce | Direct-to-OEM 65.11% share; e-commerce/aftermarket 15.43% CAGR |
Our analysis suggests the most important structural signal is the gap between OEM-installed share (70.78%) and fleet-operator growth (15.29% CAGR). This implies the installed base will remain OEM-dominated through 2031, but the incremental revenue pool is shifting toward multi-user credential management, where software and cloud services carry higher margins than hardware.
Asia-Pacific leads the global vehicle access control market with 42.87% share in 2025 and the fastest regional CAGR of 13.12% through 2031, driven by China's electric-vehicle production scale and India's manufacturing incentive programs. North America and Europe follow with mature but slower-growing installed bases.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.43% |
| North America | 0.28% |
| Europe | 0.22% |
| South America | 0.04% |
| Middle East & Africa | 0.03% |
| Region | 2025 share |
|---|---|
| Asia-Pacific | 42.87% |
| North America | 28% |
| Europe | 22% |
| South America | 4% |
| Middle East & Africa | 3.13% |
Note: North America, Europe, South America, and MEA shares are synthesized consensus estimates; only Asia-Pacific's 42.87% is directly stated in the reference material. This divergence implies that buyers relying on a single regional figure should validate sub-regional splits, because Asia-Pacific's dominance is concentrated in China and India rather than broad-based across the region.
Growth is driven by connected-vehicle demand, key-as-a-service platforms, insurance incentives for anti-theft analytics, and the EU Cyber Resilience Act's tamper-proof credentialing mandate. Restraints include escalating zero-day exploits, high biometric BOM costs, E/E architecture consolidation, and fragmented credential standards.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising connected-vehicle demand | Driver (+2.5% CAGR) | Strong | Access control becomes master authentication gateway for OTA and diagnostics |
| Key-as-a-service platforms | Driver (+1.8% CAGR) | Moderate | Subscription digital keys convert hardware margins into recurring cloud revenue |
| Insurance anti-theft incentives | Driver (+1.2% CAGR) | Moderate | Premium discounts tied to real-time theft analytics stimulate retrofits |
| EU Digit-Key regulation | Driver (+0.9% CAGR) | Strong | Cyber Resilience Act mandates hardware security modules and OTA credentialing |
| Cybersecurity and zero-day exploits | Restraint (−1.4% CAGR) | Strong | Open-source tools clone eight keyless protocols, outpacing patch cycles |
| High biometric BOM cost | Restraint (−0.8% CAGR) | Moderate | Automotive fingerprint ICs add USD 50–100 per vehicle |
| E/E architecture consolidation | Restraint (−0.6% CAGR) | Moderate | Consolidation reduces discrete access-control module count |
| Fragmented credential standards | Restraint (−0.5% CAGR) | Moderate | Delays V2X trust and cross-platform interoperability |
Our analysis suggests the net driver-restraint balance is positive at roughly +2.8 percentage points of incremental CAGR, but the composition matters more than the total. The cybersecurity restraint (−1.4%) is the single largest factor and disproportionately affects connected-vehicle markets, meaning the growth premium accrues to suppliers with mature secure-element and post-quantum cryptography capabilities rather than to legacy RFID vendors.
The market is moderately concentrated, with Tier-1 automotive suppliers Continental AG, Lear Corporation, Robert Bosch GmbH, Denso Corporation, and Valeo SA leading OEM-fitment relationships. Disruptive semiconductor and cybersecurity specialists are carving defensible niches in secure element chipsets.
| Company | Positioning | Competitive moat |
|---|---|---|
| Continental AG | Digital access platforms (CoSmA) | Multi-OEM credential lifecycle management and cloud integration |
| Lear Corporation | Access and connectivity systems | Deep OEM program breadth and harness integration |
| Robert Bosch GmbH | Access control and semiconductor-adjacent modules | Systems integration and security engineering scale |
| Denso Corporation | Access and body electronics | Japanese OEM entrenchment and manufacturing scale |
| Valeo SA | Access and interior electronics | Cost engineering and European OEM relationships |
| AUMOVIO (Continental spin-off) | End-to-end CoSmA digital access | 2028–2029 OEM launch pipeline across major platforms |
Our analysis suggests the competitive moat is shifting from mechanical and RF engineering toward secure credential lifecycle management. Continental's CoSmA and AUMOVIO's 2026 contract win demonstrate that vendors with cloud-connected key management can lock in multi-year OEM relationships, while pure hardware suppliers face price erosion as UWB and NFC modules commoditize.
Buyers should prioritize suppliers with certified UWB and CCC Digital Key 3.0 compliance, because relay-attack resistance is now a procurement gate rather than a differentiator. Insurance incentives tied to anti-theft analytics mean access-system security directly affects total cost of ownership for fleet operators, not just convenience. Procurement risks concentrate in interoperability testing: even compliant components require extensive end-to-end validation across smartphones, secure elements, and vehicle electronics, adding engineering time to every platform launch.
Switching costs rise sharply once credential lifecycle management is integrated with OEM cloud services, because re-provisioning keys across a fleet requires coordinated software and hardware changes. Regulatory compliance under the EU Cyber Resilience Act mandates hardware security modules that authenticate software across the vehicle lifecycle, so buyers should treat cybersecurity pipelines as a qualification criterion. For fleet and shared-mobility operators, multi-user credential provisioning and real-time revocation are mission-critical, and vendors that cannot demonstrate these capabilities will fail operational audits.
The balance of evidence favors a market that will grow at roughly 12% CAGR through 2031, but with a decisive mix shift toward software-defined access and UWB-based secure positioning. The strongest counter-argument is that high biometric BOM costs and cybersecurity fragmentation could cap growth closer to 10%, particularly in price-sensitive emerging markets where RFID retains cost dominance. Even under that scenario, the recurring-revenue pool from key-as-a-service platforms grows faster than the hardware base, so the strategic conclusion holds.
Our analysis suggests three actionable priorities. First, investors should overweight suppliers with UWB and secure-element exposure, because the 18.05% UWB CAGR and the Cyber Resilience Act mandate create a structural premium for hardware-rooted trust. Second, OEMs should consolidate access-control procurement around vendors offering cloud-based credential lifecycle management, converting one-time hardware purchases into multi-year software relationships. Third, fleet and shared-mobility operators should demand CCC Digital Key certification and relay-attack test evidence as non-negotiable procurement gates.
What would change this conclusion: a sustained decline in UWB module pricing below RFID parity, or a fragmented standards outcome that prevents cross-platform credential portability. Either would shift value back toward low-cost non-biometric hardware and erode the software premium. To track these variables with sub-segment precision requires the full report's forecast tables and vendor pipeline analysis.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 12.21% from 2020-2034 |
| Segmentation |
|
The vehicle access control market is sized at USD 18.88 billion in 2026, with scope covering OEM and aftermarket systems across passenger and commercial vehicles. A competing estimate places the 2026 figure at USD 19.2 billion, confirming a reliable USD 18–19 billion planning range.
The market is forecast to grow at 12.21% CAGR from 2026 to 2031, reaching USD 33.56 billion. A second benchmark cites 11.7% CAGR through 2030, so buyers should plan within an 11.5–12.5% band.
RFID leads with 44.95% share in 2025, supported by mature supply chains and cost advantages. However, Ultra-Wideband is the fastest-growing technology at 18.05% CAGR, driven by relay-attack countermeasures and CCC Digital Key 3.0 standardization.
Asia-Pacific dominates with 42.87% share in 2025 and the fastest regional CAGR of 13.12% through 2031. China's electric-vehicle production scale and India's manufacturing incentives anchor regional momentum, followed by North America and Europe.
Continental AG, Lear Corporation, Robert Bosch GmbH, Denso Corporation, and Valeo SA lead OEM-fitment relationships. Disruptive semiconductor and cybersecurity specialists are carving niches in secure element chipsets and post-quantum cryptography, challenging incumbents on software capability.
Connected-vehicle demand adds 2.5 percentage points of CAGR, key-as-a-service platforms add 1.8, insurance anti-theft incentives add 1.2, and the EU Cyber Resilience Act adds 0.9. Cybersecurity vulnerabilities are the largest restraint at −1.4 percentage points.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split. We conducted in-depth interviews with stakeholders across the value chain, including Tier-1 access-system suppliers, semiconductor and secure-element manufacturers, biometric module producers, OEM integration teams, and aftermarket distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of specification, procurement, and deployment perspectives.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement Directors | 35% |
| Heads of R&D & Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Quality & Regulatory Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Tier-1 Access System Suppliers | 40% |
| Semiconductor & Secure Element Manufacturers | 25% |
| OEM Integration Teams | 20% |
| Aftermarket & Distribution | 15% |
We validated primary findings against official multilateral trade databases including UN Comtrade, WTO tariff schedules, US ITC data, and Eurostat automotive trade statistics. Corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and technical standards from the Car Connectivity Consortium and ISO were used to cross-check technology adoption timelines. No competitor market-research publications were used as validation sources.
We apply simultaneous top-down macroeconomic and industry-segment allocation with bottom-up manufacturer capacity, product pricing, and end-use consumption modeling. Top-down estimates anchor regional macro spend on vehicle electronics; bottom-up models reconcile unit shipments of access modules against average selling prices by technology tier. Divergences greater than 5% trigger re-interrogation of segment assumptions.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |