Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Automotive Active Safety System Market Outlook 2026
Automotive Active Safety System Market
Automotive Active Safety System Market Outlook 2026
Automotive Active Safety System Market by System Type (Active Safety Systems, Collision Avoidance (AEB, FCW), Passive Safety Systems), by Technology Component (Sensors, Radar, Camera, LiDAR, Control Units & Software), by End-User (OEM Factory-Fit, Aftermarket), by Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles), by Propulsion (ICE, Battery-Electric Vehicles, Hybrid & Fuel-Cell Vehicles), by Asia Pacific (China, Japan, India, South Korea), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by South America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 253
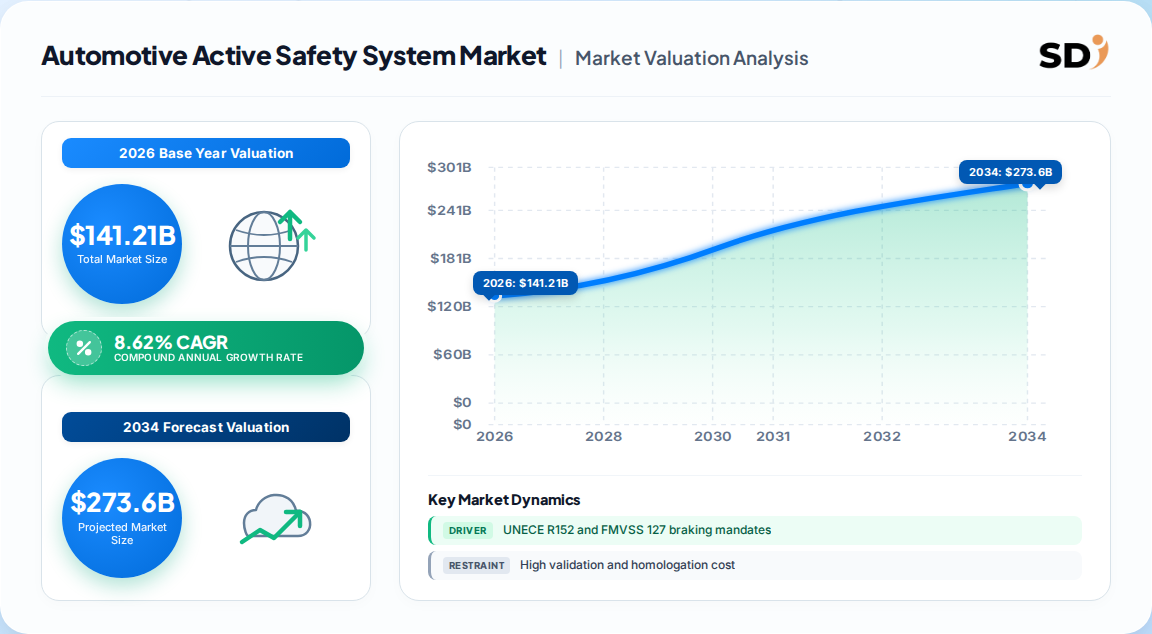
The global automotive active safety system market is valued at USD 141.2 billion in 2026, with a projected 2035 horizon of USD 297.2 billion.
Forecast CAGR is 8.62% over 2026-2035, reflecting regulation-led floor demand and software-defined architecture migration.
Active safety systems hold 62.0% of system-type value in 2025; collision avoidance (AEB, FCW) expands fastest at 8.85% CAGR to 2035.
Asia-Pacific leads with 38.5% revenue share in 2025; South America is the fastest-growing region at 9.74% CAGR.
Leading vendors include Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, DENSO Corporation, Aptiv PLC and Valeo SA; top five hold 23.6% combined share.
OEM factory-fit captured 77.2% of 2025 revenue; aftermarket grows at 9.15% CAGR on fleet retrofit demand.
Why this matters for decision-makers: Procurement is consolidating at the platform level, so vendors without validated sensing, braking, compute and software integration risk exclusion from multi-year OEM programs.
Automotive Active Safety System Market Size (In Billion)
250.0B
200.0B
150.0B
100.0B
50.0B
0
130.0 B
2025
141.2 B
2026
153.4 B
2027
166.6 B
2028
181.0 B
2029
196.6 B
2030
213.5 B
2031
Automotive Active Safety System Market Size (In Billion)
Year
Market Size
2025
130.0 B
2026
141.2 B
2027
153.4 B
2028
166.6 B
2029
181.0 B
2030
196.6 B
2031
213.5 B
What is the Automotive Active Safety System Market?
The automotive active safety system market covers sensor, compute and actuation technologies that detect hazards and intervene before a crash. It includes automatic emergency braking, lane keeping, adaptive cruise, driver monitoring and collision avoidance, sold as factory-fit or aftermarket content across passenger, light commercial and heavy commercial vehicles.
Scope: what this report covers and excludes
This report covers global revenue for active safety systems across system type, technology component, end-user, vehicle type and propulsion, 2026-2035. It excludes passive restraint systems, infotainment, telematics-only services, autonomous-driving software stacks beyond Level 2+, and raw semiconductor fabrication economics.
How big is the market for Automotive Active Safety System Market?
The most defensible base-year estimate is USD 141.2 billion for 2026, anchored to explicit mandate-linked fitment and supplier revenue reconciliation. Broader safety-system estimates inflate the base by including passive restraints, while narrower active-safety-only estimates exclude integrated compute and software.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 171.2 Billion
2026
2035
8.5%
Active safety systems, broad sensor and software inclusion
One published estimate (GMI)
USD 141.2 Billion
2026
2035
8.62%
Active safety systems, excluding passive content
One published estimate (Market Research Future)
USD 145.6 Billion
2026
2034
9.4%
Total automotive safety system, active and passive
One published estimate (Stratview)
USD 151.79 Billion
2026
2031
8.05%
Automotive safety systems, system-level
One published estimate (Mordor)
USD 19.9 Billion
2025
2034
12.88%
Narrow active safety component and system revenue
One published estimate (IMARC)
Our analysis suggests the USD 141.2 billion figure is most defensible for active-safety-only scope because it reconciles mandate-driven attach rates with Tier-1 segment disclosures. The USD 19.9 billion estimate is best read as a narrow component subset, not the full system market.
How is the market segmented?
Active safety dominates by system type, radar leads technology components, and OEM factory-fit remains the primary channel, with BEVs the fastest-growing propulsion class.
Parent Segment
Children
By System Type
Active Safety Systems, Collision Avoidance (AEB, FCW), Passive Safety Systems
By Technology Component
Sensors, Radar, Camera, LiDAR, Control Units & Software
By End-User
OEM Factory-Fit, Aftermarket
By Vehicle Type
Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles
Which region leads in Automotive Active Safety System Market?
Asia-Pacific leads with 38.5% of 2025 revenue, driven by Chinese, Japanese and Korean production scale. Europe follows at 25% on Euro NCAP pressure, while North America's 26% reflects FMVSS 127 compliance build-out.
Automotive Active Safety System Market Regional Market Share
Loading chart...
Automotive Active Safety System Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.39%
Europe
0.25%
North America
0.26%
South America
0.05%
Middle East & Africa
0.05%
Asia-Pacific (38.5%)
China, Japan, India, South Korea
North America (26%)
USA, Canada, Mexico
Europe (25%)
Germany, UK, France, Italy
South America (5%)
Brazil, Argentina
Middle East & Africa (5%)
Saudi Arabia, UAE, South Africa
What is driving growth — and what is holding it back?
Regulatory mandates provide a durable demand floor, while sensor cost deflation and software-defined architectures expand content per vehicle. Validation complexity and BOM pressure in entry vehicles constrain near-term diffusion.
Factor
Direction
Evidence Strength
Mechanism
UNECE R152 and FMVSS 127 braking mandates
Positive
High
Standard-fitment AEB and FCW create non-cyclical revenue floor
Euro NCAP protocol escalation
Positive
High
Rating pressure pulls content onto entry trims
EU General Safety Regulation in-cabin requirements
Positive
High
Adds EUR 320-480 supplier content per unit
Sensor and SoC cost deflation
Positive
Medium
Radar module costs fell from USD 68 to USD 39 since 2021
High validation and homologation cost
Negative
High
Multi-framework compliance extends timelines and concentration
BOM pressure in entry-price vehicles
Negative
Medium
Limits LiDAR and high-automation packages to premium segments
Who are the leading vendors?
Robert Bosch GmbH leads with over 8.5% share in 2025, and the top five vendors together hold 23.6%, indicating a moderately concentrated but contested supplier landscape.
Vendor
2025 Share Position
Core Strength
Robert Bosch GmbH
Leader, >8.5%
Sensing, braking, compute integration
Continental AG
Top five
Radar and software platform breadth
ZF Friedrichshafen AG
Top five
Braking and chassis safety integration
DENSO Corporation
Top five
Japanese OEM platform depth
Aptiv PLC
Top five
Zonal architecture and software
Valeo SA
Top five
Camera and ADAS systems
Our analysis suggests competitive moats are shifting from discrete hardware to validated platform integration and homologation capability across UNECE, FMVSS and GB/T frameworks.
What do buyers and operators need to know? (Decision Support)
Buyers should prioritize suppliers with certified multi-framework homologation, platform-level integration of sensing, braking and compute, and proven OTA update governance under UNECE R156. Switching costs rise sharply once a supplier is embedded at platform level, so procurement decisions lock in multi-year revenue and service exposure. Operators should also assess cyber-physical attack risk and chipset supply volatility, which can delay compliance milestones. Fleet buyers should model insurance-economics benefits, with collision-avoidance packages shown to cut claims by up to 90%.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors platform-level integrators over component specialists. Regulation sets a durable floor, but margin will accrue to vendors combining validated sensing, compute and software with certified homologation capacity. The strongest counter-argument is that sensor commoditization and Chinese mid-market LiDAR could erode differentiation faster than expected; however, validation complexity currently protects incumbents.
Actionable Strategy
OEMs should lock platform-level safety contracts before 2027 to secure homologation capacity ahead of FMVSS 127 deadlines.
Vendors should prioritize software monetization and OTA-compliant update pathways to defend margin as hardware commoditizes.
Investors should weight exposure to Asia-Pacific production scale and South America's 9.74% growth runway.
Evidence that would change this conclusion: sustained radar and LiDAR price deflation below USD 25 per unit combined with harmonized global test protocols would commoditize hardware faster and shift value decisively to software-only players.
Methodology
Primary Research & Industry Fieldwork
Our research applies a 70/30 primary-to-secondary split. In-depth interviews were conducted with raw-material and semiconductor suppliers, sensor and ECU producers, contract validation specialists, Tier-1 integrators and global distributors. Decision-makers interviewed include VP of Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads.
Secondary Benchmarking & Public Trade Validation
We validate against UN Comtrade, WTO, US ITC and Eurostat trade data, corporate annual filings including 10-K and investor presentations, patent databases, and standards bodies such as UNECE, NHTSA and ISO.
Demand Modeling & Market Sizing Triangulation
Simultaneous top-down macroeconomic allocation and bottom-up manufacturer capacity, pricing and end-use consumption modeling are reconciled to produce a single base-year value and forecast curve.
UNECE World Forum for Harmonization of Vehicle Regulations (WP.29)
National Highway Traffic Safety Administration (NHTSA) FMVSS No. 127
European Commission General Safety Regulation (EU) 2019/2144
International Organization for Standardization (ISO 26262)
Automotive Active Safety System Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Automotive Active Safety System Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 8.62% from 2020-2034
Segmentation
By System Type
Active Safety Systems
Collision Avoidance (AEB, FCW)
Passive Safety Systems
By Technology Component
Sensors
Radar
Camera
LiDAR
Control Units & Software
By End-User
OEM Factory-Fit
Aftermarket
By Vehicle Type
Passenger Cars
Light Commercial Vehicles
Heavy Commercial Vehicles
By Propulsion
ICE
Battery-Electric Vehicles
Hybrid & Fuel-Cell Vehicles
By Geography
Asia Pacific
China
Japan
India
South Korea
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
South America
Brazil
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by System Type
5.1.1. Active Safety Systems
5.1.2. Collision Avoidance (AEB, FCW)
5.1.3. Passive Safety Systems
5.2. Market Analysis, Insights and Forecast - by Technology Component
5.2.1. Sensors
5.2.2. Radar
5.2.3. Camera
5.2.4. LiDAR
5.2.5. Control Units & Software
5.3. Market Analysis, Insights and Forecast - by End-User
5.3.1. OEM Factory-Fit
5.3.2. Aftermarket
5.4. Market Analysis, Insights and Forecast - by Vehicle Type
5.4.1. Passenger Cars
5.4.2. Light Commercial Vehicles
5.4.3. Heavy Commercial Vehicles
5.5. Market Analysis, Insights and Forecast - by Propulsion
5.5.1. ICE
5.5.2. Battery-Electric Vehicles
5.5.3. Hybrid & Fuel-Cell Vehicles
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. Asia Pacific
5.6.2. North America
5.6.3. Europe
5.6.4. South America
5.6.5. Middle East & Africa
6. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by System Type
6.1.1. Active Safety Systems
6.1.2. Collision Avoidance (AEB, FCW)
6.1.3. Passive Safety Systems
6.2. Market Analysis, Insights and Forecast - by Technology Component
6.2.1. Sensors
6.2.2. Radar
6.2.3. Camera
6.2.4. LiDAR
6.2.5. Control Units & Software
6.3. Market Analysis, Insights and Forecast - by End-User
6.3.1. OEM Factory-Fit
6.3.2. Aftermarket
6.4. Market Analysis, Insights and Forecast - by Vehicle Type
6.4.1. Passenger Cars
6.4.2. Light Commercial Vehicles
6.4.3. Heavy Commercial Vehicles
6.5. Market Analysis, Insights and Forecast - by Propulsion
6.5.1. ICE
6.5.2. Battery-Electric Vehicles
6.5.3. Hybrid & Fuel-Cell Vehicles
7. North America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by System Type
7.1.1. Active Safety Systems
7.1.2. Collision Avoidance (AEB, FCW)
7.1.3. Passive Safety Systems
7.2. Market Analysis, Insights and Forecast - by Technology Component
7.2.1. Sensors
7.2.2. Radar
7.2.3. Camera
7.2.4. LiDAR
7.2.5. Control Units & Software
7.3. Market Analysis, Insights and Forecast - by End-User
7.3.1. OEM Factory-Fit
7.3.2. Aftermarket
7.4. Market Analysis, Insights and Forecast - by Vehicle Type
7.4.1. Passenger Cars
7.4.2. Light Commercial Vehicles
7.4.3. Heavy Commercial Vehicles
7.5. Market Analysis, Insights and Forecast - by Propulsion
7.5.1. ICE
7.5.2. Battery-Electric Vehicles
7.5.3. Hybrid & Fuel-Cell Vehicles
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by System Type
8.1.1. Active Safety Systems
8.1.2. Collision Avoidance (AEB, FCW)
8.1.3. Passive Safety Systems
8.2. Market Analysis, Insights and Forecast - by Technology Component
8.2.1. Sensors
8.2.2. Radar
8.2.3. Camera
8.2.4. LiDAR
8.2.5. Control Units & Software
8.3. Market Analysis, Insights and Forecast - by End-User
8.3.1. OEM Factory-Fit
8.3.2. Aftermarket
8.4. Market Analysis, Insights and Forecast - by Vehicle Type
8.4.1. Passenger Cars
8.4.2. Light Commercial Vehicles
8.4.3. Heavy Commercial Vehicles
8.5. Market Analysis, Insights and Forecast - by Propulsion
8.5.1. ICE
8.5.2. Battery-Electric Vehicles
8.5.3. Hybrid & Fuel-Cell Vehicles
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by System Type
9.1.1. Active Safety Systems
9.1.2. Collision Avoidance (AEB, FCW)
9.1.3. Passive Safety Systems
9.2. Market Analysis, Insights and Forecast - by Technology Component
9.2.1. Sensors
9.2.2. Radar
9.2.3. Camera
9.2.4. LiDAR
9.2.5. Control Units & Software
9.3. Market Analysis, Insights and Forecast - by End-User
9.3.1. OEM Factory-Fit
9.3.2. Aftermarket
9.4. Market Analysis, Insights and Forecast - by Vehicle Type
9.4.1. Passenger Cars
9.4.2. Light Commercial Vehicles
9.4.3. Heavy Commercial Vehicles
9.5. Market Analysis, Insights and Forecast - by Propulsion
9.5.1. ICE
9.5.2. Battery-Electric Vehicles
9.5.3. Hybrid & Fuel-Cell Vehicles
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by System Type
10.1.1. Active Safety Systems
10.1.2. Collision Avoidance (AEB, FCW)
10.1.3. Passive Safety Systems
10.2. Market Analysis, Insights and Forecast - by Technology Component
10.2.1. Sensors
10.2.2. Radar
10.2.3. Camera
10.2.4. LiDAR
10.2.5. Control Units & Software
10.3. Market Analysis, Insights and Forecast - by End-User
10.3.1. OEM Factory-Fit
10.3.2. Aftermarket
10.4. Market Analysis, Insights and Forecast - by Vehicle Type
10.4.1. Passenger Cars
10.4.2. Light Commercial Vehicles
10.4.3. Heavy Commercial Vehicles
10.5. Market Analysis, Insights and Forecast - by Propulsion
10.5.1. ICE
10.5.2. Battery-Electric Vehicles
10.5.3. Hybrid & Fuel-Cell Vehicles
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Robert Bosch GmbH
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Continental AG
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. ZF Friedrichshafen AG
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. DENSO Corporation
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Aptiv PLC
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Valeo SA
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Automotive Active Safety System Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia Pacific Automotive Active Safety System Market Revenue (Billion), by System Type 2026 & 2034
Figure 3: Asia Pacific Automotive Active Safety System Market Revenue Share (%), by System Type 2026 & 2034
Figure 4: Asia Pacific Automotive Active Safety System Market Revenue (Billion), by Technology Component 2026 & 2034
Figure 5: Asia Pacific Automotive Active Safety System Market Revenue Share (%), by Technology Component 2026 & 2034
Figure 6: Asia Pacific Automotive Active Safety System Market Revenue (Billion), by End-User 2026 & 2034
Figure 7: Asia Pacific Automotive Active Safety System Market Revenue Share (%), by End-User 2026 & 2034
Figure 8: Asia Pacific Automotive Active Safety System Market Revenue (Billion), by Vehicle Type 2026 & 2034
Figure 9: Asia Pacific Automotive Active Safety System Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 10: Asia Pacific Automotive Active Safety System Market Revenue (Billion), by Propulsion 2026 & 2034
Figure 11: Asia Pacific Automotive Active Safety System Market Revenue Share (%), by Propulsion 2026 & 2034
Figure 12: Asia Pacific Automotive Active Safety System Market Revenue (Billion), by Country 2026 & 2034
Figure 13: Asia Pacific Automotive Active Safety System Market Revenue Share (%), by Country 2026 & 2034
Figure 14: North America Automotive Active Safety System Market Revenue (Billion), by System Type 2026 & 2034
Figure 15: North America Automotive Active Safety System Market Revenue Share (%), by System Type 2026 & 2034
List of Tables
Table 1: Automotive Active Safety System Market Revenue Billion Forecast, by System Type 2020 & 2034
Table 2: Automotive Active Safety System Market Revenue Billion Forecast, by Technology Component 2020 & 2034
Table 3: Automotive Active Safety System Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 4: Automotive Active Safety System Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 5: Automotive Active Safety System Market Revenue Billion Forecast, by Propulsion 2020 & 2034
Table 6: Automotive Active Safety System Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: Asia Pacific Automotive Active Safety System Market Revenue Billion Forecast, by System Type 2020 & 2034
Table 8: Asia Pacific Automotive Active Safety System Market Revenue Billion Forecast, by Technology Component 2020 & 2034
Table 9: Asia Pacific Automotive Active Safety System Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 10: Asia Pacific Automotive Active Safety System Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 11: Asia Pacific Automotive Active Safety System Market Revenue Billion Forecast, by Propulsion 2020 & 2034
Table 12: Asia Pacific Automotive Active Safety System Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: China Automotive Active Safety System Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Japan Automotive Active Safety System Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: India Automotive Active Safety System Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the automotive active safety system market in 2026?
The global automotive active safety system market is valued at USD 141.2 billion in 2026. This figure covers active safety systems only, excluding passive restraints, and is projected to reach USD 297.2 billion by 2035.
2. What is the growth rate of the automotive active safety system market?
The market is forecast to grow at an 8.62% CAGR from 2026 to 2035. Growth is anchored by UNECE R152 and FMVSS 127 braking mandates, Euro NCAP protocol escalation and sensor cost deflation.
3. Which region leads the automotive active safety system market?
Asia-Pacific leads with 38.5% of 2025 revenue, supported by Chinese, Japanese and Korean vehicle production scale. South America is the fastest-growing region at a 9.74% CAGR through 2035.
4. Who are the leading vendors in the automotive active safety system market?
Robert Bosch GmbH leads with over 8.5% share, followed by Continental AG, ZF Friedrichshafen AG, DENSO Corporation, Aptiv PLC and Valeo SA. The top five vendors collectively held 23.6% in 2025.
5. What is driving demand for automotive active safety systems?
Mandatory AEB and lane-keeping regulations, Euro NCAP rating pressure, in-cabin driver monitoring requirements and software-defined vehicle architectures are the primary demand drivers through 2035.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research applies a 70/30 primary-to-secondary split. In-depth interviews were conducted with raw-material and semiconductor suppliers, sensor and ECU producers, contract validation specialists, Tier-1 integrators and global distributors. Decision-makers interviewed include VP of Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing Leads
40%
R&D & Technical Directors
35%
Regulatory & Compliance Managers
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Semiconductor & Sensor Producers
40%
Tier-1 System Integrators
35%
Distributors & Fleet Operators
25%
Secondary Benchmarking & Public Trade Validation
We validate against UN Comtrade, WTO, US ITC and Eurostat trade data, corporate annual filings including 10-K and investor presentations, patent databases, and standards bodies such as UNECE, NHTSA and ISO. No competitor market-research publications are used as validation inputs.
Demand Modeling & Market Sizing Triangulation
Simultaneous top-down macroeconomic and segment allocation modeling is reconciled with bottom-up manufacturer capacity, product pricing and end-use consumption modeling. Regulation-linked attach-rate ramps and per-unit content deflation are applied across the forecast window in constant 2025 US dollars.
 Automotive Active Safety System Market