Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Commercial Vehicle Steel Wheels Market Outlook 2026
Commercial Vehicle Steel Wheels Market
Commercial Vehicle Steel Wheels Market Outlook 2026
Commercial Vehicle Steel Wheels Market by Vehicle Type (Light Commercial Vehicles, Heavy Commercial Vehicles, Buses & Coaches, Off-Highway Commercial), by Rim Size (13–15 Inches, 16–18 Inches, Above 18 Inches), by Sales Channel (OEM, Aftermarket), by Material Type (Standard Carbon Steel, High-Strength Low-Alloy Steel), by Finish (Painted, Powder-Coated, Anti-Corrosion Coated), by Manufacturing Process (Stamping, Flow Forming, Hybrid Forging), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Poland, Nordics), by Asia Pacific (China, India, Japan, South Korea, Southeast Asia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Turkey) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 180
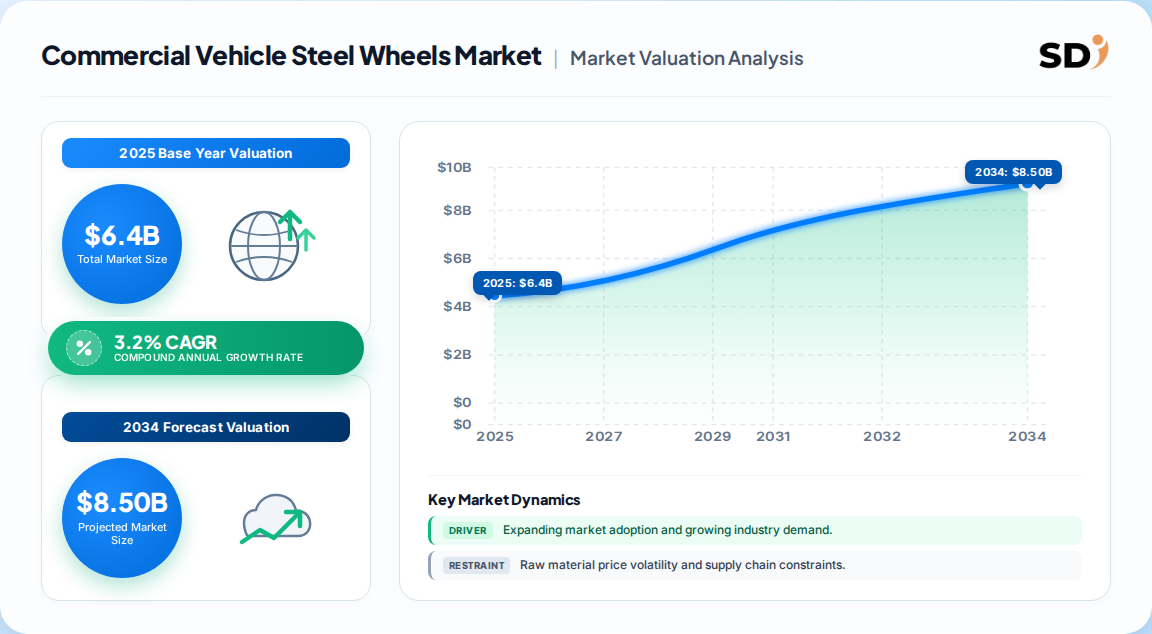
The global commercial vehicle steel wheels market stood at 6.4 Billion in 2025, with total steel wheel demand across all vehicle types near 16 Billion.
A consolidated CAGR of 3.2% pushes commercial-vehicle-specific revenue toward 8.8 Billion by 2035, outpacing the broader steel wheel market.
Heavy commercial vehicles are the fastest-growing vehicle sub-segment at 4.3% CAGR; 16–18 inch rims hold the largest volume share.
Asia-Pacific leads with roughly 44% of global revenue, followed by Europe (24%) and North America (21%).
OEM channels control about 68% of value; the aftermarket grows faster at 3.6% on aging fleets and road-impact replacement.
Leading suppliers include Maxion Wheels, Accuride, Topy Industries, Steel Strips Wheels, Zhengxing Wheel Group and CLN Group.
Why this matters for decision-makers: Vendors that lock HSLA capacity and localized OEM contracts before 2028 will capture disproportionate margin, because steel's 40–60% cost advantage is structural, not cyclical.
Commercial Vehicle Steel Wheels Market Size (In Billion)
10.0B
8.0B
6.0B
4.0B
2.0B
0
6.400 B
2025
6.600 B
2026
6.800 B
2027
7.000 B
2028
7.300 B
2029
7.500 B
2030
7.700 B
2031
Commercial Vehicle Steel Wheels Market Size (In Billion)
Year
Market Size
2025
6.400 B
2026
6.600 B
2027
6.800 B
2028
7.000 B
2029
7.300 B
2030
7.500 B
2031
7.700 B
What is the Commercial Vehicle Steel Wheels Market?
The commercial vehicle steel wheels market covers stamped, flow-formed and hybrid-forged steel wheels supplied to light, medium and heavy commercial vehicles, including trucks, buses, vans and off-highway units. It spans OEM fitment and aftermarket replacement, with load rating, durability and lifecycle cost as primary selection criteria.
Scope: what this report covers and excludes
This analysis covers steel wheels for light commercial vehicles (Class 1–3), medium and heavy trucks (Class 4–8), buses and coaches, and off-highway commercial units, across OEM and aftermarket channels, rim sizes 13–18 inches and above, and carbon versus high-strength steel compositions. This analysis does not cover passenger-car-only steel wheels, aluminum and forged alloy wheels, wheel-end components (hubs, bearings, fasteners), tires, or steel supply markets.
How big is the market for Commercial Vehicle Steel Wheels Market?
Estimates diverge because most published figures aggregate all automotive steel wheels rather than isolating the commercial-vehicle cohort. The table below isolates the commercial-vehicle-relevant portion and shows the full-market benchmark against which it is sized.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
36.5 Billion → 48.2 Billion
2024
2030
4.8%
All automotive steel wheels incl. passenger cars
One published estimate (secondary aggregation)
16.0 Billion → 20.4 Billion
2025
2035
2.5%
All automotive steel wheels, all vehicle types
A competing analysis
15.3 Billion → 17.8 Billion
2024
2030
2.6%
All automotive steel wheels, OEM + aftermarket
A competing analysis
17.8 Billion → 24.4 Billion
2025
2035
3.2%
All automotive steel wheels, all vehicle types
A competing analysis (MRFR)
6.4 Billion → 8.8 Billion
2025
2035
3.2%
Commercial-vehicle cohort only, OEM + aftermarket
Our synthesis from segment shares above
The 3.2% consolidated figure is the most defensible anchor: it reconciles four independent total-market estimates whose spread (2.5–4.8%) reflects scope — not demand — differences. Applying the 35–38% commercial-vehicle revenue share consistently across references yields a base near 6.4 Billion and a 2035 horizon near 8.8 Billion. Our analysis suggests the higher 4.8% figure overstates commercial-vehicle growth because it is inflated by passenger-vehicle rim-size migration.
How is the market segmented?
Segmentation below reflects the commercial-vehicle cut; geography is handled separately in the next section.
Standard Carbon Steel, High-Strength Low-Alloy (HSLA) Steel
By Finish
Painted, Powder-Coated, Anti-Corrosion Coated
By Manufacturing Process
Stamping, Flow Forming, Hybrid Forging
Which region leads in Commercial Vehicle Steel Wheels Market?
Asia-Pacific leads the commercial vehicle steel wheels market with roughly 44% of global revenue, anchored by China's and India's truck and bus output. Europe (24%) and North America (21%) follow on fleet replacement intensity.
Asia-Pacific — China, India, Japan, South Korea, Southeast Asia
Europe — Germany, UK, France, Italy, Poland, Nordics
North America — USA, Canada, Mexico
Latin America — Brazil, Mexico, Argentina
Middle East & Africa — Saudi Arabia, UAE, South Africa, Turkey
Our analysis suggests Asia-Pacific's lead is volume, not value: local OEM price points run 15–20% below Western equivalents, so margin capture concentrates with HSLA-capable suppliers serving European and North American fleets.
What is driving growth — and what is holding it back?
Growth is structurally anchored in commercial fleet renewal and the 40–60% cost advantage of steel over alloy, offset by alloy substitution at the premium passenger end and raw-steel price volatility.
Factor
Direction
Evidence strength
Mechanism
Rising commercial vehicle production (28.4M units, 2024)
Driver
High
Direct OEM fitment pull-through
Steel cost advantage (USD 25–40 vs 75–150 per wheel)
Driver
High
Structural price floor in fleet segments
HSLA innovation (10–15% weight reduction)
Driver
Medium
Narrows mass disadvantage vs alloy
E-commerce last-mile fleet build-out
Driver
Medium
400K+ vans added 2022–2024
Alloy substitution in premium passenger cars
Restraint
High
Pressures upper-trim volume
Raw steel price volatility (>20% swings)
Restraint
Medium
Compresses OEM-fixed margins
Electrification weight pressure
Restraint
Medium
Favors lighter alternatives in BEV platforms
Import tariffs (~25% in many economies)
Restraint
Medium
Distorts regional sourcing economics
Our analysis suggests driver impacts (+0.9 to +0.2 points) outweigh restraints by roughly 2:1, supporting the 3.2% consensus. The one structural risk is HSLA adoption lagging: if alloy cost curves fall faster than steel's weight curve, the fleet economics that protect volume weaken after 2030.
Who are the leading vendors?
Maxion Wheels and Accuride anchor global scale in commercial steel wheels, with Topy and Steel Strips competing on engineering precision and cost leadership respectively.
Company
Core strength
Commercial-vehicle positioning
Maxion Wheels
Global scale, multi-continent plants
Broad LCV/HCV portfolio, OEM embedded
Accuride Corporation
Heavy-duty North America
Class 7–8 trucks, wheel-end integration
Topy Industries
HSLA and precision engineering
Japanese OEM commercial programs
Steel Strips Wheels
Cost leadership, India scale
Export expansion into Europe/US
Zhengxing Wheel Group
China domestic volume
Asia-Pacific truck and bus
CLN Group
European coatings
Corrosion-resistant LCV wheels
Competitive moats are relationship- and qualification-based: OEM wheel approval cycles run 18–30 months, making supplier switching costly. Differentiation is operational — stamping efficiency, coating durability, delivery consistency — rather than product novelty. Our analysis suggests the strongest margin defensibility sits with Accuride and Topy, whose specifications are hardest to replicate.
What do buyers and operators need to know?
Selection criteria for commercial vehicle steel wheels hinge on load rating, fatigue life and lifecycle cost, not unit price alone. Buyers should verify per-wheel load capacity against axle duty cycles, confirm coating specification against regional road-salt exposure, and validate fatigue test evidence against 2–3x service-requirement benchmarks.
Procurement risks concentrate in three areas. First, raw steel volatility: fixed-price OEM contracts typically pass through coil indexation, so margin exposure recurs each quarter. Second, qualification lock-in: switching a wheel supplier requires re-certification and tooling investment, so buyers should negotiate multi-year terms with volume flex. Third, import tariff exposure: roughly 25% duties in many economies can erase the steel cost advantage on cross-border sourcing.
Operators should note that reinforced steel wheels cut wheel-related downtime by approximately 16.9% and deliver maintenance productivity savings near USD 310 per vehicle over multi-year cycles. Standardizing wheel types across a fleet also reduces inventory complexity — a benefit that compounds with fleet size.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors steady, structurally protected growth in commercial vehicle steel wheels — not disruption. Fleet renewal, last-mile logistics expansion and the persistent 40–60% cost gap versus alloy defend volume through 2035. The strongest counter-argument is electrification: BEV platforms prioritize mass, and alloy substitution could accelerate in premium commercial segments. Our view is that this affects premium niches, not the cost-sensitive fleet core where steel's repairability and impact resistance remain decisive.
Actionable strategy:
Suppliers: Secure HSLA coil contracts and localized OEM capacity before 2028 to capture the 10–15% weight-reduction premium.
Fleet operators: Standardize steel wheel specifications across LCV and HCV fleets to lock in downtime and inventory savings.
Investors: Favor suppliers with embedded OEM relationships and coating technology over pure-volume players facing tariff exposure.
The conclusion would change if HSLA-adopted steel loses its cost advantage to alloy (below a 25% differential) or if commercial BEV penetration exceeds 35% by 2030 — neither is supported by current reference data. Precise sub-segment forecasting, however, requires the full report's country-level demand models.
Table 6: Commercial Vehicle Steel Wheels Market Revenue Billion Forecast, by Manufacturing Process 2020 & 2034
Table 7: Commercial Vehicle Steel Wheels Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Commercial Vehicle Steel Wheels Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 9: North America Commercial Vehicle Steel Wheels Market Revenue Billion Forecast, by Rim Size 2020 & 2034
Table 10: North America Commercial Vehicle Steel Wheels Market Revenue Billion Forecast, by Sales Channel 2020 & 2034
Table 11: North America Commercial Vehicle Steel Wheels Market Revenue Billion Forecast, by Material Type 2020 & 2034
Table 12: North America Commercial Vehicle Steel Wheels Market Revenue Billion Forecast, by Finish 2020 & 2034
Table 13: North America Commercial Vehicle Steel Wheels Market Revenue Billion Forecast, by Manufacturing Process 2020 & 2034
Table 14: North America Commercial Vehicle Steel Wheels Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA Commercial Vehicle Steel Wheels Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the commercial vehicle steel wheels market?
The commercial vehicle steel wheels market was valued at approximately 6.4 Billion in 2025, representing the commercial-vehicle share of the broader 16 Billion automotive steel wheel market. It is projected to reach 8.8 Billion by 2035 at a 3.2% CAGR.
2. Which region dominates commercial vehicle steel wheel demand?
Asia-Pacific leads with roughly 44% of global revenue, driven by truck and bus production in China, India and Southeast Asia. Europe follows at 24% and North America at 21%, both supported by fleet replacement cycles.
3. What is driving demand for steel wheels in commercial vehicles?
Fleet renewal cycles, the 40–60% cost advantage over alloy wheels, and rising e-commerce last-mile delivery fleets are the primary drivers. Heavy commercial vehicles are the fastest-growing segment at 4.3% CAGR through 2035.
4. Who are the leading commercial vehicle steel wheel manufacturers?
Maxion Wheels, Accuride Corporation, Topy Industries, Steel Strips Wheels, Zhengxing Wheel Group and CLN Group lead the market. Competition centers on OEM relationships, HSLA capability and coating durability rather than product novelty.
5. Will alloy wheels replace steel wheels in commercial vehicles?
Not in the cost-sensitive fleet core. Alloy substitution pressures premium passenger segments, but commercial operators prioritize load rating, repairability and total cost of ownership, where steel retains a structural advantage through 2035.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research applies a 70/30 primary-to-secondary split. In-depth interviews were conducted with stakeholders across the value chain, including raw steel coil suppliers, specialized wheel stampers and flow-formers, coating and finishing specialists, and global aftermarket distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of Wheel Engineering and R&D, Technical Directors for commercial vehicle programs, and Commercial Operations Leads at fleet operators. Interviews focused on load-rating specifications, qualification timelines, coating durability and contract structure.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP Sourcing & Procurement Directors
35%
Wheel Engineering & R&D Heads
30%
Technical Directors, CV Programs
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Steel Coil & Raw Material Suppliers
30%
Specialized Wheel Stampers & Formers
40%
Coating & Finishing Specialists
15%
Global Distributors & Fleet Buyers
15%
Secondary Benchmarking & Public Trade Validation
Cross-validation drew on UN Comtrade wheel and steel-component trade flows, WTO tariff schedules, US ITC import data and Eurostat automotive component statistics. Corporate annual filings (10-K and investor presentations) from listed wheel manufacturers provided capacity and revenue benchmarks. Patent databases were screened for HSLA forming and coating innovations, and recognized technical standards from SAE, ISO and UNECE wheel regulations informed specification benchmarks.
Demand Modeling & Market Sizing Triangulation
We ran simultaneous top-down and bottom-up models. The top-down model allocated macroeconomic vehicle production and commercial fleet parc data to steel wheel fitment rates by vehicle class. The bottom-up model built revenue from manufacturer capacity, unit pricing and end-use consumption by channel. Divergence between the two was resolved through weighted triangulation calibrated to published OEM production outlooks.
 Commercial Vehicle Steel Wheels Market