 Automotive Textiles Market
: Size, Trends & Forecast 2026
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 272

Sadashiv Parab
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Automotive Textiles Market
Sadashiv Parab
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 32.80 B |
| 2026 | 33.90 B |
| 2027 | 35.00 B |
| 2028 | 36.20 B |
| 2029 | 37.40 B |
| 2030 | 38.60 B |
| 2031 | 39.90 B |

Automotive textiles are engineered fabrics used in vehicle interiors, exteriors, and safety systems—covering upholstery, airbags, seat belts, carpets, headliners, and composites. They must meet stringent durability, flammability, and comfort standards. The market encompasses woven, nonwoven, and composite materials supplied to OEMs and Tier 1 manufacturers globally.
This report analyzes the global automotive textiles market across product types (woven, nonwoven, composites) and applications (upholstery, safety devices, floor coverings, tires, engine components). It covers OEM and aftermarket demand across five regions. This analysis does not cover industrial textiles, medical textiles, or packaging textiles unless directly integrated into automotive applications. It excludes raw fiber production and textile machinery.
Estimates converge around $32–33 billion for 2025, but long-term forecasts diverge on CAGR (3.3% vs. 3.4%) and horizon (2033 vs. 2035). The table below compares leading published estimates.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| $32.8B → $42.4B | 2025 | 2033 | 3.3% | Woven, composites, nonwovens; upholstery, safety, floor | One published estimate |
| $32.87B → $45.92B | 2025 | 2035 | 3.4% | Woven, nonwoven, composites; broader application set | Competing analysis |
| $46.17B → $75.94B | 2025 | 2035 | 5.1% | Automotive fabrics; includes PRIC and tires | Alternative scope |
Our analysis suggests the 3.3–3.4% CAGR band is most defensible for the core automotive textiles market, aligning with global vehicle production growth of ~2–3% annually. The higher 5.1% figure likely reflects a broader definition including pre-assembled interior components and tire cord fabrics. Buyers should anchor on the $42–46 billion range for 2033–2035 planning.
The market segments primarily by product type and application, with composites and upholstery leading in 2025.
| Parent Segment | Children | 2025 Share / Note |
|---|---|---|
| By Type | Woven, Nonwoven, Composites | Composites 39.4% |
| By Application | Upholstery, Safety Devices, Floor Coverings, Tires, Engine Components | Upholstery 55.7% |
| By Vehicle Type | Passenger Cars, LCVs, Heavy Trucks, Buses & Coaches | Passenger cars largest |
Composites gain share due to lightweighting mandates. Nonwovens expand in acoustic insulation and filtration. Upholstery remains the revenue anchor but faces pricing pressure from recycled polyester adoption.
Asia Pacific leads with 48.6% revenue share in 2025, driven by China's dominance in vehicle production and export-oriented textile manufacturing. North America and Europe follow, with mature but innovation-focused markets.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.49% |
| North America | 0.23% |
| Europe | 0.19% |
| South America | 0.05% |
| Middle East & Africa | 0.04% |
| Parent Region | Key Countries | Share (2025) |
|---|---|---|
| Asia Pacific | China, Japan, India, South Korea | 48.6% |
| North America | USA, Canada, Mexico | ~23% |
| Europe | Germany, UK, France, Italy | ~19% |
| Latin America | Brazil, Mexico, Argentina | ~5% |
| Middle East & Africa | Saudi Arabia, UAE, South Africa | ~4% |
China's share reflects both domestic OEM demand and export of textile components. This divergence implies supply chain strategies must prioritize Asian sourcing while maintaining regional flexibility for tariff and logistics risks.
Lightweighting, safety regulations, and EV adoption drive demand; raw material volatility and moisture retention challenges restrain growth.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Lightweighting for fuel efficiency | Driver | High | Textiles replace heavier materials; EV range extension |
| Safety regulations (airbags, seat belts) | Driver | High | Mandated inclusion in all vehicles |
| Sustainability / recycled materials | Driver | Medium | OEM commitments; EU Digital Product Passport |
| Raw material price volatility | Restraint | High | Petrochemical feedstock fluctuations |
| Moisture retention / mold risk | Restraint | Low | Material limitations; quality concerns |
| Substitute materials (leather, polymers) | Restraint | Medium | Competition from synthetic alternatives |
The balance favors growth, but margin pressure from raw materials is acute. Our analysis suggests vendors with backward integration into recycled fiber production will outperform.
The competitive landscape is moderately consolidated, with Tier 1 automotive suppliers and specialized textile manufacturers competing on innovation and OEM relationships.
| Company | Headquarters | Focus Area | Differentiation |
|---|---|---|---|
| Adient | USA | Seating systems | Integrated interior solutions |
| Lear Corporation | USA | Seating, electrical | Scale and OEM partnerships |
| Faurecia (Forvia) | France | Interiors, emissions | Sustainability leadership |
| Toyota Boshoku | Japan | Interiors, filtration | Keiretsu integration with Toyota |
| Sage Automotive Interiors | USA | Upholstery fabrics | Design and customization |
| Aunde SA | Germany | Seat covers, fabrics | European OEM stronghold |
Competitive moats derive from long-term OEM contracts, design capability, and vertical integration. Smaller players face pressure to consolidate or specialize in niche materials.
Procurement strategies must balance cost, compliance, and innovation. Key selection criteria include flammability certification (FMVSS 302, ISO 3795), durability under UV and abrasion, and recycled content verification for EU market access. Switching costs are high due to tooling and validation cycles (12–18 months), so buyers should prioritize suppliers with demonstrated R&D pipelines.
Regulatory risk is rising: the EU Digital Product Passport (mandatory for textiles by ~2030) will require traceable material provenance. Operators should audit supply chains for carbon reporting readiness. Our analysis suggests early movers on digital traceability will secure preferred supplier status.
The balance of evidence favors cautious optimism: 3.3–3.4% CAGR is steady but not transformative. The strongest counter-argument is that EV adoption could accelerate lightweighting demand beyond forecasts, or conversely, that substitution by molded plastics could erode textile share in non-visible components. We judge the former more likely given regulatory tailwinds.
Actionable Strategy:
What would change our conclusion: A sharp decline in global vehicle production (below 80 million units annually) or a technology breakthrough in bio-based textiles that disrupts polyester demand would lower the growth trajectory. Conversely, faster EV adoption and stricter safety mandates could push CAGR above 4%.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.3% from 2020-2034 |
| Segmentation |
|
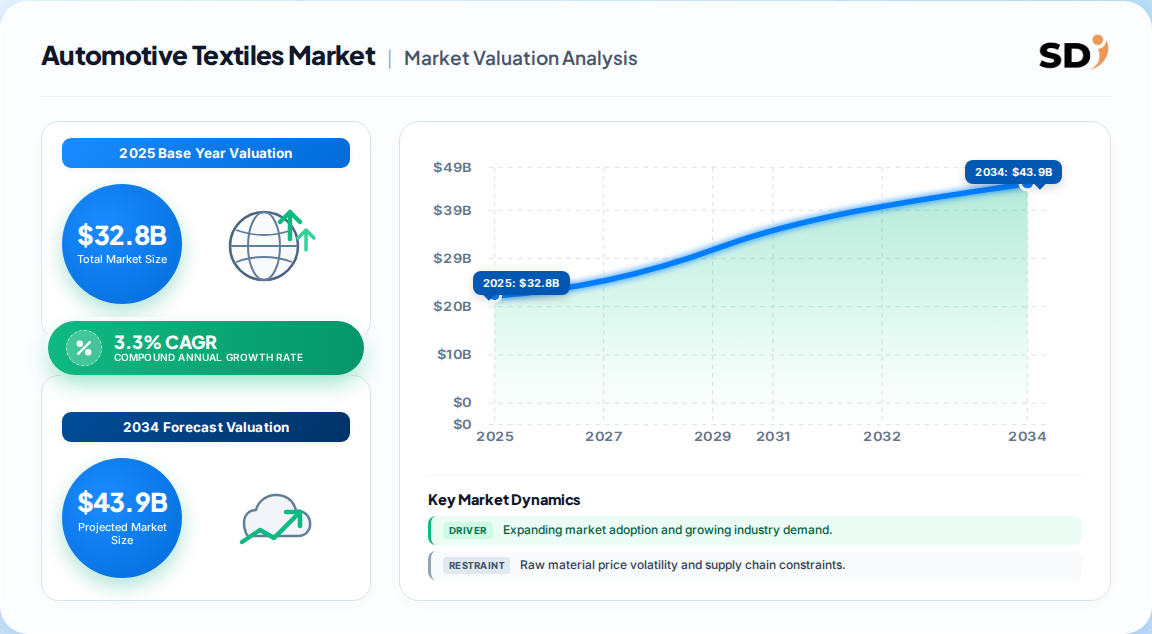
The global automotive textiles market was valued at approximately $32.8 billion in 2025, with estimates ranging up to $46.2 billion depending on scope definitions that include or exclude pre-assembled components and tire fabrics.
The market is projected to grow at a CAGR of 3.3% from 2026 to 2033, reaching $42.4 billion by 2033. Some competing analyses forecast 3.4% through 2035, reflecting minor scope differences.
Asia Pacific leads with approximately 48.6% revenue share in 2025, driven by China's vehicle production scale and export-oriented textile manufacturing. North America and Europe follow with mature, innovation-focused markets.
The market segments by type (woven, nonwoven, composites) and application (upholstery, safety devices, floor coverings, tires, engine components). Composites held 39.4% share and upholstery 55.7% in 2025.
Key players include Adient, Lear Corporation, Faurecia, Toyota Boshoku, Sage Automotive Interiors, Aunde SA, and Borgers AG. Competition centers on OEM relationships, design innovation, and sustainability credentials.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is built on a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the value chain, including raw material suppliers (polyester, nylon, recycled fibers), specialized textile producers, Tier 1 automotive interior integrators, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. These interviews validated pricing structures, capacity utilization, and adoption timelines for sustainable materials.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement VPs | 35% |
| R&D and Technical Directors | 40% |
| Commercial Operations Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Fiber Producers | 40% |
| Specialized Textile Manufacturers | 35% |
| Tier 1 Integrators & Distributors | 25% |
We triangulated primary insights against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards from ISO and SAE International. These sources provided validation for production volumes, trade flows, and regulatory compliance requirements.
We employed simultaneous Top-Down and Bottom-Up modeling. Top-down allocation used macroeconomic indicators (vehicle production, GDP, urbanization rates) to size regional demand. Bottom-up modeling aggregated manufacturer capacity, product pricing, and end-use consumption across vehicle segments. Discrepancies were resolved through iterative reconciliation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection to 2033/2035 | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |