Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Driverless Cars Market Size, CAGR & 2031 Outlook
Driverless Cars Market Size, CAGR & 2031 Outlook
Driverless Cars Market
Driverless Cars Market Size, CAGR & 2031 Outlook
Driverless Cars Market by Level of Automation (Level 1, Level 2, Level 3, Level 4, Level 5), by Vehicle Type (Hatchbacks, Sedans, SUVs and MPVs), by Propulsion Type (ICE, BEV, HEV), by Mobility Form (Personal Ownership, Shared Mobility), by Component (Hardware, Software, Services), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Netherlands), by Asia Pacific (China, Japan, South Korea, India, Singapore), by Latin America (Brazil, Argentina, Chile), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 236
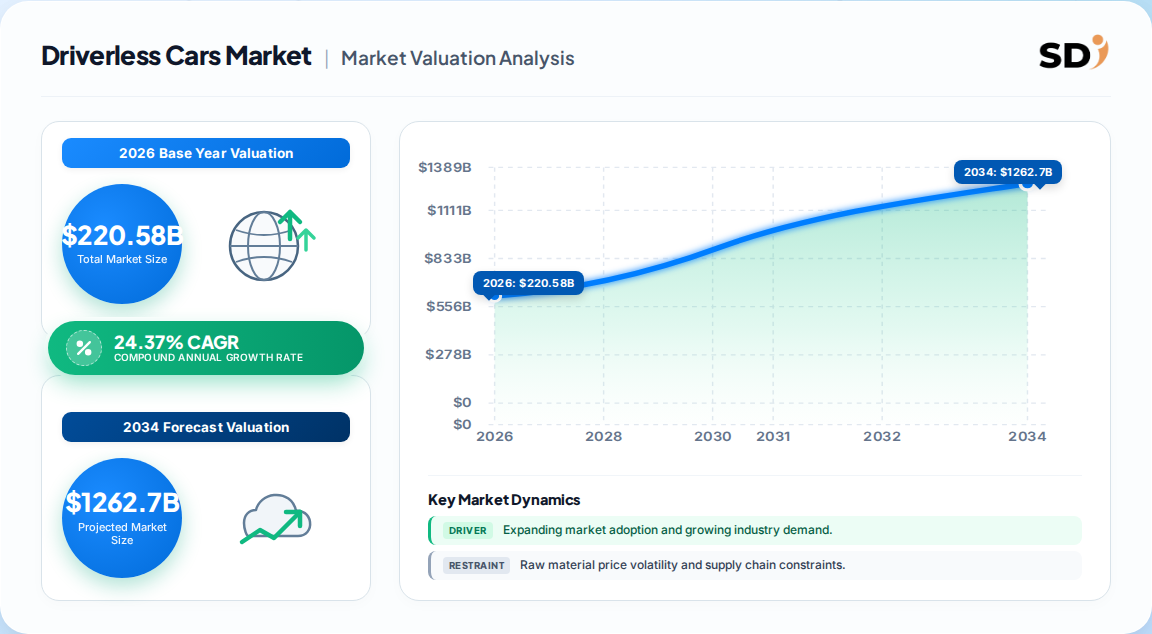
Globally, the driverless cars market is valued at 220.58 Billion in 2026, projected to reach 656.37 Billion by 2031 at a 24.37% CAGR.
Level 1 driver assistance dominates with 43.47% share (2025), yet Level 5 full automation is forecast to expand fastest at a 24.39% CAGR to 2031.
SUVs and MPVs captured 78.81% of demand in 2025, while hatchbacks post the steepest growth at 25.11% CAGR.
North America leads with 38.71% revenue share (2025); Asia Pacific is the fastest-growing region at 25.05% CAGR.
Personal ownership still accounts for 74.35% of value, but shared mobility grows at 25.13% CAGR through 2031.
Hardware retains 55.57% of component value, although software is the fastest-expanding layer at 25.07% CAGR.
Why this matters for decision-makers: Software and shared-mobility economics will determine long-run margin pools — vendors anchored purely in hardware commoditization face structural margin compression and must pivot toward recurring, OTA-delivered revenue.
Driverless Cars Market Size (In Billion)
750.0B
600.0B
450.0B
300.0B
150.0B
0
177.2 B
2025
220.6 B
2026
274.3 B
2027
341.2 B
2028
424.4 B
2029
527.8 B
2030
656.4 B
2031
Driverless Cars Market Size (In Billion)
Year
Market Size
2025
177.2 B
2026
220.6 B
2027
274.3 B
2028
341.2 B
2029
424.4 B
2030
527.8 B
2031
656.4 B
What is the Driverless Cars Market?
The driverless cars market covers vehicles and enabling systems — sensors, compute, software and services — that perform driving tasks with limited or no human intervention, spanning Levels 1 through 5 automation across personal and shared mobility use cases.
Scope: what this report covers and excludes
This analysis covers passenger and commercial vehicles segmented by automation level, vehicle type, propulsion, mobility form and component, with a global forecast horizon of 2026–2031. Market value is expressed in USD and volume in units.
This analysis does not cover adjacent markets such as autonomous drones, industrial AGVs, standalone LiDAR component sales outside automotive applications, or non-automotive robotics.
How big is the market for Driverless Cars Market?
Two credible published estimates diverge materially, primarily because they define the category differently — one anchors on autonomy hardware and software value, the other on broader autonomous vehicle revenue including services.
Autonomous vehicles incl. passenger and commercial, broader application scope
A competing analysis
Our analysis suggests the higher figure is the more defensible basis for automotive-specific planning, because it isolates driverless cars from commercial-vehicle and defense adjacencies and reflects ADAS-fitment commoditization already visible in 2025 volumes. The lower estimate's wider application base dilutes per-vehicle value, making it less useful for component-level forecasting.
How is the market segmented?
The market segments along five non-geographic axes, with automation level and component being the most commercially decisive for suppliers.
Parent Segment
Children
Level of Automation
Level 1, Level 2, Level 3, Level 4, Level 5
Vehicle Type
Hatchbacks, Sedans, SUVs & MPVs
Propulsion Type
ICE, BEV, HEV
Mobility Form
Personal Ownership, Shared Mobility
Component
Hardware, Software, Services
Level 1's 43.47% share signals that revenue today is still regulatory-compliance driven, not full-autonomy driven. This implies suppliers should monetize ADAS volume now while positioning software stacks for the Level 3 transition.
Which region leads in Driverless Cars Market?
North America leads the driverless cars market with 38.71% revenue share in 2025, supported by mature robo-taxi commercialization and permissive state-level testing regimes; Asia Pacific follows as the fastest-growing region at a 25.05% CAGR.
Driverless Cars Market Regional Market Share
Loading chart...
Driverless Cars Market Regional Market Share
Region
Market Share (%)
North America
0.39%
Europe
0.24%
Asia-Pacific
0.28%
Latin America
0.05%
Middle East & Africa
0.04%
North America — USA, Canada, Mexico
Europe — Germany, UK, France, Italy, Netherlands
Asia Pacific — China, Japan, South Korea, India, Singapore
Latin America — Brazil, Argentina, Chile
Middle East & Africa — UAE, Saudi Arabia, South Africa
Asia Pacific's growth premium is concentrated in Chinese mega-city robo-taxi pilots and Japanese Level 4 regulatory reform. Europe's trajectory is shaped by mandatory ADAS regulation, which pulls forward volume but compresses per-unit hardware pricing.
What is driving growth — and what is holding it back?
Growth is driven by robo-taxi commercialization, mandatory ADAS safety regulation in the EU and China, and falling LiDAR and AI-compute costs; restraints center on fragmented US state regulation and public trust following high-profile incidents.
Factor
Direction
Evidence Strength
Mechanism
Robo-taxi pilot expansion (China, Japan)
Driver
Strong
+4.2% CAGR impact; municipal licensing and positive unit economics
ADAS safety mandates (EU, China, UN R157)
Driver
Strong
+3.8% CAGR; standard fitment builds sensor scale economies
Falling LiDAR and AI compute costs
Driver
Moderate-Strong
+3.5% CAGR; enables mid-tier Level 3 launches
5G-V2X corridor roll-outs
Driver
Moderate
+3.1% CAGR; freight platooning and route optimization
The balance favors growth: regulatory mandates create a compliance floor under demand, while cost deflation converts that floor into volume. The critical unknown is whether public-trust restraint outpaces the cost curve in dense urban markets.
Who are the leading vendors?
The competitive field spans vertically integrated technology platforms, legacy OEMs scaling ADAS, and China-based robo-taxi operators — a medium-concentration structure where software ecosystems, not hardware, define moats.
Player Archetype
Representative Examples
Strategic Position
Robotaxi platform operators
Waymo, Baidu Apollo Go
Early commercial scale, real-world data advantage
Legacy OEMs with L3 programs
Mercedes-Benz, Toyota, Nissan, Hyundai
Regulatory certification and manufacturing scale
Compute and sensor suppliers
NVIDIA, Hesai
Component-level cost leadership
Mobility-software integrators
Hyundai Pleos, fleet platforms
SDV software and fleet management layers
Differentiation is shifting toward data-network effects: operators with the largest paid-ride volumes compound perception-model advantage. Legacy OEMs retain distribution and certification moats, but risk ceding the software layer to third parties.
What do buyers and operators need to know?
Procurement decisions should weight software upgradability and regulatory certification over headline sensor specifications, because perception stacks improve via OTA updates while hardware depreciates. Buyers should verify UN R157 and EU 2019/2144 compliance pathway evidence before committing to fleet volumes, and confirm municipal licensing status in target cities rather than relying on national frameworks.
Switching costs are highest at the software and data layer — fleets locked into a proprietary autonomy stack face multi-year migration costs — so contract terms on data ownership and interoperability deserve scrutiny. Insurance and liability allocation remains an unresolved operational risk in mixed-autonomy corridors.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors the high-growth scenario: a 24%+ CAGR is credible because regulatory mandates have converted a discretionary technology into a compliance requirement, creating non-optional demand. The strongest counter-argument is that Level 1 dominance today reflects ADAS fitment, not genuine driverless capability — meaning headline market value may overstate readiness for Level 4+ commercialization.
Our position: investors should underwrite the software and shared-mobility sub-segments rather than aggregate market growth, since those layers capture the compounding economics of OTA upgrades and fleet utilization. Hardware suppliers should expect price deflation even as volumes rise.
Operators: Secure municipal licensing and data-ownership terms early in Asia Pacific mega-cities, where unit economics already approach breakeven.
Vendors: Prioritize OTA-upgradable software stacks to convert one-time vehicle sales into recurring revenue streams.
The evidence that would change this conclusion: sustained regulatory fragmentation in the US beyond 2027, or a material public-trust shock that stalls licensing in more than two major markets simultaneously.
Driverless Cars Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Driverless Cars Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 24.37% from 2020-2034
Segmentation
By Level of Automation
Level 1
Level 2
Level 3
Level 4
Level 5
By Vehicle Type
Hatchbacks
Sedans
SUVs and MPVs
By Propulsion Type
ICE
BEV
HEV
By Mobility Form
Personal Ownership
Shared Mobility
By Component
Hardware
Software
Services
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Netherlands
Asia Pacific
China
Japan
South Korea
India
Singapore
Latin America
Brazil
Argentina
Chile
Middle East & Africa
UAE
Saudi Arabia
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Level of Automation
5.1.1. Level 1
5.1.2. Level 2
5.1.3. Level 3
5.1.4. Level 4
5.1.5. Level 5
5.2. Market Analysis, Insights and Forecast - by Vehicle Type
5.2.1. Hatchbacks
5.2.2. Sedans
5.2.3. SUVs and MPVs
5.3. Market Analysis, Insights and Forecast - by Propulsion Type
5.3.1. ICE
5.3.2. BEV
5.3.3. HEV
5.4. Market Analysis, Insights and Forecast - by Mobility Form
5.4.1. Personal Ownership
5.4.2. Shared Mobility
5.5. Market Analysis, Insights and Forecast - by Component
5.5.1. Hardware
5.5.2. Software
5.5.3. Services
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Level of Automation
6.1.1. Level 1
6.1.2. Level 2
6.1.3. Level 3
6.1.4. Level 4
6.1.5. Level 5
6.2. Market Analysis, Insights and Forecast - by Vehicle Type
6.2.1. Hatchbacks
6.2.2. Sedans
6.2.3. SUVs and MPVs
6.3. Market Analysis, Insights and Forecast - by Propulsion Type
6.3.1. ICE
6.3.2. BEV
6.3.3. HEV
6.4. Market Analysis, Insights and Forecast - by Mobility Form
6.4.1. Personal Ownership
6.4.2. Shared Mobility
6.5. Market Analysis, Insights and Forecast - by Component
6.5.1. Hardware
6.5.2. Software
6.5.3. Services
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Level of Automation
7.1.1. Level 1
7.1.2. Level 2
7.1.3. Level 3
7.1.4. Level 4
7.1.5. Level 5
7.2. Market Analysis, Insights and Forecast - by Vehicle Type
7.2.1. Hatchbacks
7.2.2. Sedans
7.2.3. SUVs and MPVs
7.3. Market Analysis, Insights and Forecast - by Propulsion Type
7.3.1. ICE
7.3.2. BEV
7.3.3. HEV
7.4. Market Analysis, Insights and Forecast - by Mobility Form
7.4.1. Personal Ownership
7.4.2. Shared Mobility
7.5. Market Analysis, Insights and Forecast - by Component
7.5.1. Hardware
7.5.2. Software
7.5.3. Services
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Level of Automation
8.1.1. Level 1
8.1.2. Level 2
8.1.3. Level 3
8.1.4. Level 4
8.1.5. Level 5
8.2. Market Analysis, Insights and Forecast - by Vehicle Type
8.2.1. Hatchbacks
8.2.2. Sedans
8.2.3. SUVs and MPVs
8.3. Market Analysis, Insights and Forecast - by Propulsion Type
8.3.1. ICE
8.3.2. BEV
8.3.3. HEV
8.4. Market Analysis, Insights and Forecast - by Mobility Form
8.4.1. Personal Ownership
8.4.2. Shared Mobility
8.5. Market Analysis, Insights and Forecast - by Component
8.5.1. Hardware
8.5.2. Software
8.5.3. Services
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Level of Automation
9.1.1. Level 1
9.1.2. Level 2
9.1.3. Level 3
9.1.4. Level 4
9.1.5. Level 5
9.2. Market Analysis, Insights and Forecast - by Vehicle Type
9.2.1. Hatchbacks
9.2.2. Sedans
9.2.3. SUVs and MPVs
9.3. Market Analysis, Insights and Forecast - by Propulsion Type
9.3.1. ICE
9.3.2. BEV
9.3.3. HEV
9.4. Market Analysis, Insights and Forecast - by Mobility Form
9.4.1. Personal Ownership
9.4.2. Shared Mobility
9.5. Market Analysis, Insights and Forecast - by Component
9.5.1. Hardware
9.5.2. Software
9.5.3. Services
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Level of Automation
10.1.1. Level 1
10.1.2. Level 2
10.1.3. Level 3
10.1.4. Level 4
10.1.5. Level 5
10.2. Market Analysis, Insights and Forecast - by Vehicle Type
10.2.1. Hatchbacks
10.2.2. Sedans
10.2.3. SUVs and MPVs
10.3. Market Analysis, Insights and Forecast - by Propulsion Type
10.3.1. ICE
10.3.2. BEV
10.3.3. HEV
10.4. Market Analysis, Insights and Forecast - by Mobility Form
10.4.1. Personal Ownership
10.4.2. Shared Mobility
10.5. Market Analysis, Insights and Forecast - by Component
10.5.1. Hardware
10.5.2. Software
10.5.3. Services
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Driverless Cars Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Driverless Cars Market Volume Breakdown (Units, %) by Region 2026 & 2034
Figure 3: North America Driverless Cars Market Revenue (Billion), by Level of Automation 2026 & 2034
Figure 4: North America Driverless Cars Market Volume (Units), by Level of Automation 2026 & 2034
Figure 5: North America Driverless Cars Market Revenue Share (%), by Level of Automation 2026 & 2034
Figure 6: North America Driverless Cars Market Volume Share (%), by Level of Automation 2026 & 2034
Figure 7: North America Driverless Cars Market Revenue (Billion), by Vehicle Type 2026 & 2034
Figure 8: North America Driverless Cars Market Volume (Units), by Vehicle Type 2026 & 2034
Figure 9: North America Driverless Cars Market Revenue Share (%), by Vehicle Type 2026 & 2034
Figure 10: North America Driverless Cars Market Volume Share (%), by Vehicle Type 2026 & 2034
Figure 11: North America Driverless Cars Market Revenue (Billion), by Propulsion Type 2026 & 2034
Figure 12: North America Driverless Cars Market Volume (Units), by Propulsion Type 2026 & 2034
Figure 13: North America Driverless Cars Market Revenue Share (%), by Propulsion Type 2026 & 2034
Figure 14: North America Driverless Cars Market Volume Share (%), by Propulsion Type 2026 & 2034
Figure 15: North America Driverless Cars Market Revenue (Billion), by Mobility Form 2026 & 2034
Figure 16: North America Driverless Cars Market Volume (Units), by Mobility Form 2026 & 2034
List of Tables
Table 1: Driverless Cars Market Revenue Billion Forecast, by Level of Automation 2020 & 2034
Table 2: Driverless Cars Market Volume Units Forecast, by Level of Automation 2020 & 2034
Table 3: Driverless Cars Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 4: Driverless Cars Market Volume Units Forecast, by Vehicle Type 2020 & 2034
Table 5: Driverless Cars Market Revenue Billion Forecast, by Propulsion Type 2020 & 2034
Table 6: Driverless Cars Market Volume Units Forecast, by Propulsion Type 2020 & 2034
Table 7: Driverless Cars Market Revenue Billion Forecast, by Mobility Form 2020 & 2034
Table 8: Driverless Cars Market Volume Units Forecast, by Mobility Form 2020 & 2034
Table 10: Driverless Cars Market Volume Units Forecast, by Component 2020 & 2034
Table 11: Driverless Cars Market Revenue Billion Forecast, by Region 2020 & 2034
Table 12: Driverless Cars Market Volume Units Forecast, by Region 2020 & 2034
Table 13: North America Driverless Cars Market Revenue Billion Forecast, by Level of Automation 2020 & 2034
Table 14: North America Driverless Cars Market Volume Units Forecast, by Level of Automation 2020 & 2034
Table 15: North America Driverless Cars Market Revenue Billion Forecast, by Vehicle Type 2020 & 2034
Table 16: North America Driverless Cars Market Volume Units Forecast, by Vehicle Type 2020 & 2034
North America Driverless Cars Market Revenue Billion Forecast, by Propulsion Type 2020 & 2034
Frequently Asked Questions
1. How big is the driverless cars market in 2026?
The global driverless cars market is valued at 220.58 Billion in 2026, projected to reach 656.37 Billion by 2031, representing a 24.37% CAGR over the forecast period.
2. Which region grows fastest in driverless cars?
Asia Pacific is the fastest-growing region at a 25.05% CAGR through 2031, driven by robo-taxi pilots in Chinese mega-cities and Japanese Level 4 regulatory reform.
3. What is the largest automation segment?
Level 1 driver assistance held 43.47% of market share in 2025, reflecting widespread ADAS fitment mandates, while Level 5 automation grows fastest at 24.39% CAGR.
4. What are the main restraints on the driverless cars market?
Patchwork US state-level AV regulation and public mistrust following high-profile robotaxi incidents are the principal restraints, alongside high development and deployment costs.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
We apply a 70/30 primary-to-secondary research split, grounding every forecast in direct industry dialogue. In-depth interviews span raw-material and sensor suppliers, Tier-1 autonomy system producers, vehicle OEM integration teams, and global fleet distributors. Decision-makers interviewed include VP-level Sourcing leads, Heads of Autonomous Driving R&D, Technical Directors, and Commercial Operations Leads, ensuring both technical feasibility and commercial intent are captured.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Autonomy R&D & Technical Directors
40%
Procurement & Sourcing Leads
35%
Regulatory & Compliance Managers
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Sensor & Compute Hardware Suppliers
40%
Vehicle OEMs & Autonomy Integrators
35%
Fleet Operators & Mobility Platforms
25%
Secondary Benchmarking & Public Trade Validation
Findings are validated against official multilateral sources including UN Comtrade, WTO tariff databases, US ITC filings, and Eurostat automotive trade statistics. Corporate 10-K and annual investor disclosures, patent databases, and recognized technical standards bodies inform capability and capacity assumptions. No competitor research publications are used as validation inputs.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down allocation (macroeconomic output, automotive segment shares, regulatory fitment rates) and Bottom-Up modeling (manufacturer capacity, sensor and compute bill-of-materials, end-use consumption). Divergence between the two models is reconciled at segment level before any forecast is published.
 Driverless Cars Market